There's the version of tax resolution the late-night commercials sell you. Then there's how it actually works. I'm Darrin Mish, a Tampa tax attorney. I've spent 32 years on the inside of these cases. Here's the real version.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your accountant probably owns a license to BNA Income Tax Planner. They might even open it every year. What they're not doing is using it the way strategic tax planners do – running scenarios in July, modeling entity conversions in September, testing retirement contribution limits before year-end. Most CPAs treat tax software like a calculator when it should be a laboratory. The difference between those two approaches is typically six figures over a decade.
Why Professional Tax Software Sits Unused
The bna tax planner was designed for professionals who actually plan. Not professionals who prepare.
That distinction matters more than most business owners realize. When BNA Software launched the web-based version in the early 2000s, they built it for forward-looking analysis. Multi-year projections. Scenario testing. What-if modeling that answers questions in June, not April.
But most tax practices bill by the return. Not by the plan.
The economic incentives are backward. Compliance work is predictable. Planning work requires relationship depth, ongoing communication, and clients who understand the difference between a $2,500 tax return and a $15,000 tax strategy engagement.
So the software gathers digital dust. Your CPA runs one baseline scenario in March to estimate your liability, then moves to the next client. The projection tools, retirement plan modeling, and entity structure comparisons never get touched.
What the Software Actually Does
The bna tax planner handles complexity most spreadsheets can't. It models:
- Multi-year tax projections across changing tax laws and bracket structures
- Entity type comparisons showing C-corp versus S-corp versus partnership treatment side by side
- Retirement plan contributions including defined benefit plans, 401(k)s, and SEPs
- AMT calculations that catch high-income W-2 earners and option exercisers
- State tax integration for business owners with multi-state operations
The interface isn't beautiful. The learning curve isn't shallow. But the calculations are sound, and the scenario comparison tools do work most advisors charge separately for.
The Planning Calendar Most CPAs Skip
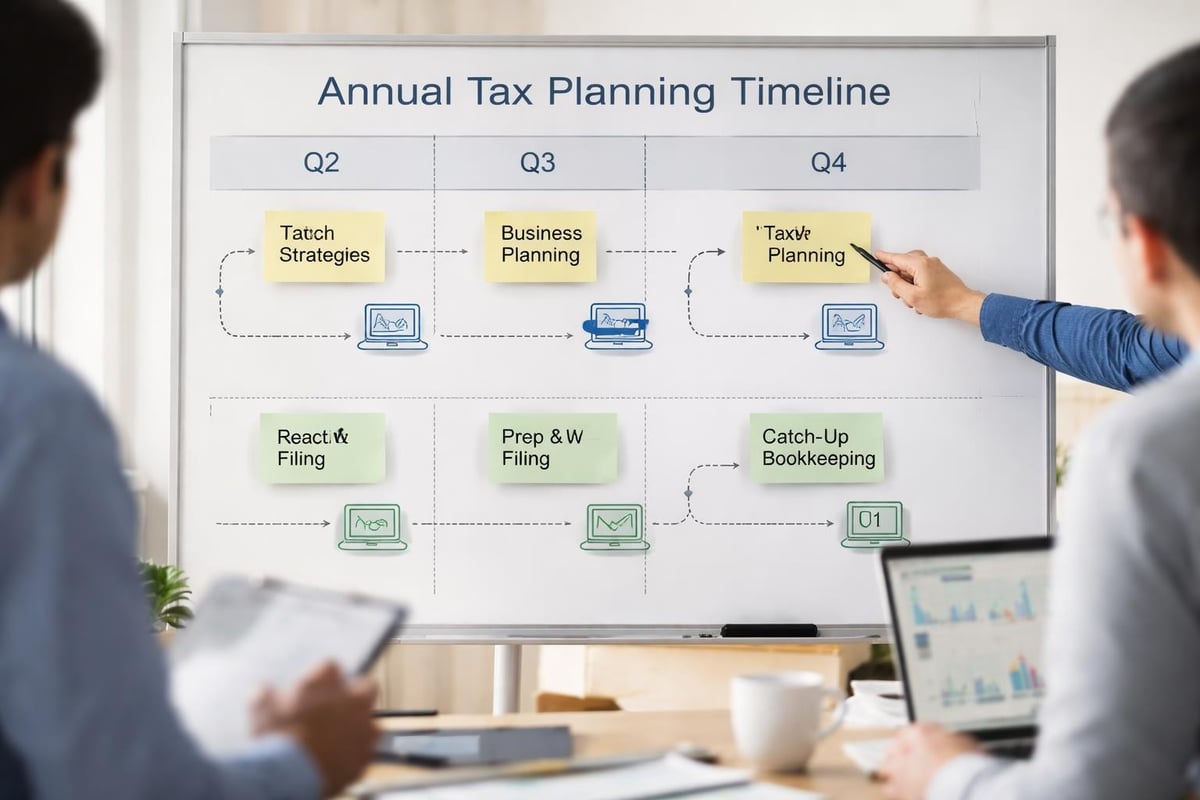
Tax planning happens on a schedule. The bna tax planner supports that schedule if someone bothers to open it more than once.
First Quarter: Baseline and Prior Year Reconciliation
January through March should establish your baseline. Not for filing – for planning.
You're comparing last year's actual results against what the software projected. Where did it miss? What changed? Did you take distributions the model didn't account for? Did revenue spike in Q4 and push you into new brackets?
This reconciliation feeds next year's accuracy. The software learns your pattern. Seasonal businesses need different modeling than steady-growth SaaS companies. Professional service firms with lumpy revenue need quarterly adjustments.
Most tax pros skip this entirely. They pull last year's return, enter current year estimates, generate a projection, and call it planning.
Second Quarter: Mid-Year Strategy Review
May through July is decision season. You have six months of actual data. You can see where the year is heading.
This is when the bna tax planner earns its license fee. You model:
- Retirement plan contributions at different levels to see bracket impact
- Equipment purchases under Section 179 and bonus depreciation
- Entity conversions if you're still running a Schedule C that should be an S-corp
- Income timing for project-based businesses that can shift revenue
The multi-year projection capabilities matter here because smart planning considers 2026 and 2027 together. Accelerating income into a low-tax year or deferring it into a future year with higher deductions changes your three-year effective rate significantly.
But only if someone runs the numbers before the decisions get made.
Third Quarter: Execution and Adjustment
August through October is implementation. The strategies you modeled in Q2 get executed in Q3.
The software tracks this. You update actual income through September, adjust Q4 estimates, and verify the strategies are working as projected. If they're not, you pivot.
Example: You modeled a $60,000 defined benefit plan contribution in June. By September, revenue is tracking 15% below projection. You run the numbers again. Maybe the contribution drops to $45,000 or gets deferred entirely.
Without software designed for this kind of iterative planning, you're guessing. With it, you're managing to a target.
Fourth Quarter: Final Optimization
November and December are execution months. Everything that didn't happen in Q3 happens now or never.
The bna tax planner shows you exactly where you stand. You know your projected liability within a few hundred dollars. You know which moves still make sense and which don't.
Most business owners get this conversation in mid-December: "You're going to owe $80,000. Maybe buy some equipment." That's not planning. That's panic.
| Quarter | Activity | BNA Tax Planner Function |
|---|---|---|
| Q1 | Baseline setup and reconciliation | Prior year comparison, entity selection |
| Q2 | Strategy modeling and scenario testing | Multi-year projections, retirement plans |
| Q3 | Mid-year execution and adjustment | Updated actuals, revised projections |
| Q4 | Final optimization and compliance prep | Year-end moves, final liability calculation |
Features Your CPA Probably Ignores
The bna tax planner includes tools most preparers never touch. Not because they're complicated – because they require strategic thinking, not data entry.
Scenario Comparison Engine
The software runs unlimited scenarios in parallel. You can model five different retirement plan structures, three entity types, and multiple income timing strategies simultaneously.
Then you compare them side by side. Not in separate spreadsheets you're trying to reconcile. In one view that shows effective tax rate, cash flow impact, and multi-year totals.
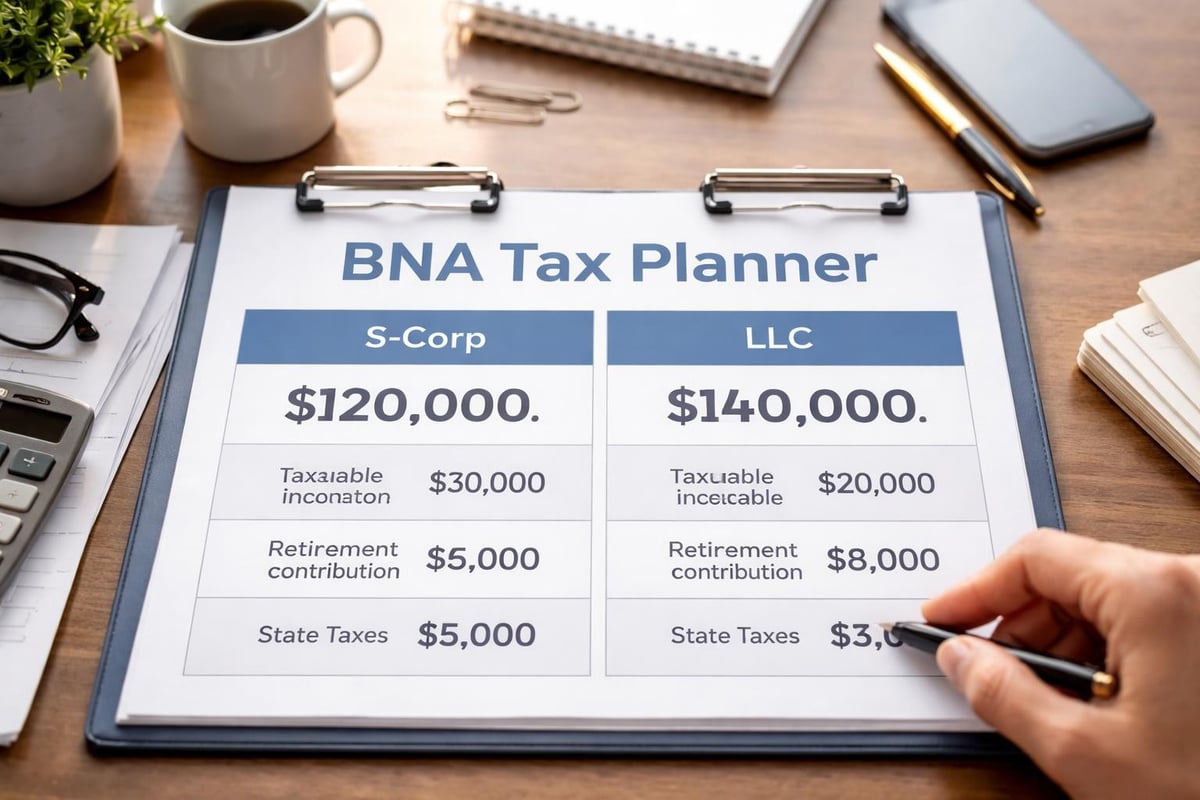
This is where planning becomes valuable. A business owner looking at S-corp versus C-corp treatment doesn't need theory. They need numbers. Specific numbers based on their actual income, their state, their industry.
The comparison engine delivers that in about 20 minutes of work. Assuming someone does the work.
Retirement Plan Modeling
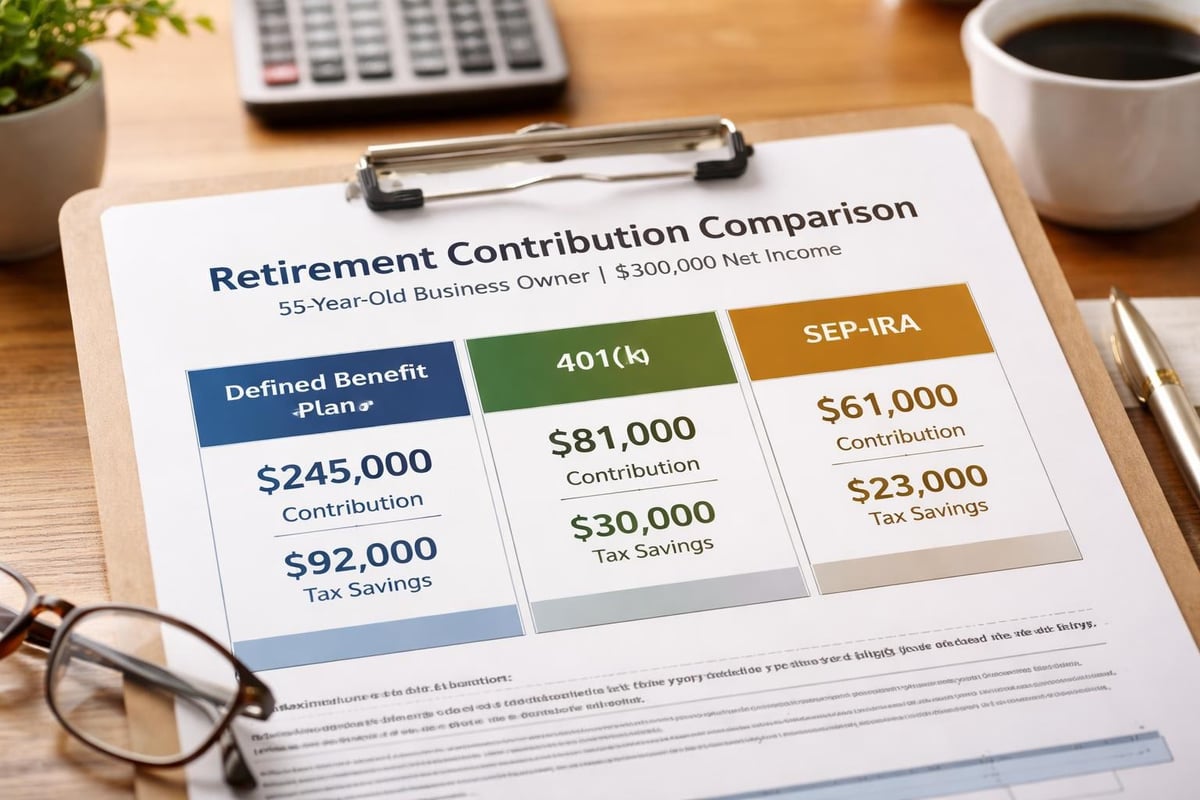
Defined benefit plans are the most powerful tax strategy most business owners never use. The bna tax planner models them correctly – including age-based contribution limits, actuary requirements, and multi-year funding obligations.
It also models:
- Solo 401(k) plans with employee and profit-sharing components
- SEP-IRAs for simplicity-focused owners
- Cash balance plans for older business owners playing catch-up
- Backdoor Roth conversions for high-income W-2 earners
Most CPAs default to whatever plan the client already has. Strategic advisors model alternatives and show the difference in real dollars.
State Tax Integration
Multi-state taxation breaks most spreadsheet models. The bna tax planner handles it natively.
You enter where you live, where the business operates, and where you have nexus. The software calculates apportionment, credits, and net liability across jurisdictions.
For business owners with remote employees, multiple locations, or income from different states, this feature alone justifies the license cost. Assuming the advisor actually uses it.
AMT and NIIT Calculations
Alternative Minimum Tax and Net Investment Income Tax calculations require separate forms, separate calculations, and separate planning strategies.
The software tracks both automatically. It flags when you're approaching AMT territory. It shows NIIT exposure before you realize capital gains or take partnership distributions.
These aren't obscure edge cases. AMT hits W-2 earners with equity compensation. NIIT hits passive real estate investors and business owners with portfolio income. Both are predictable. Both are modelable. Neither gets addressed until tax time by most preparers.
The Software Limitations Nobody Mentions
The bna tax planner is a professional tool. Professional tools have professional limitations.
Interface design hasn't changed much since 2005. It works, but it's not intuitive. First-time users need training. Even experienced users need the help documentation for edge cases.
The learning curve is real. This isn't TurboTax. It assumes you understand tax code, entity structures, and planning concepts. A business owner can't buy a license and expect to figure it out over a weekend.
Subscription costs add up. While detailed pricing information varies by firm size and features, professional tax software represents a meaningful annual expense. For solo practitioners, the cost-benefit calculation depends entirely on whether they're actually doing planning work.
It doesn't replace strategic thinking. The software models what you tell it to model. If you feed it garbage assumptions, it returns garbage projections. If you don't know which scenarios to test, the comparison engine doesn't help.
According to software evaluation research, these limitations matter more to occasional users than dedicated planning practices. For advisors who live in the software daily, the quirks become familiar. For advisors who open it once per client per year, every session feels like relearning.
How Strategic Planners Use It Differently
The difference between compliance-focused and planning-focused tax practices shows up in how they use software like the bna tax planner.
Compliance shops enter data, generate projections, and deliver estimates. One scenario. Current year only. Filing season focused.
Planning practices run the software as part of ongoing advisory relationships. They model:
- Entity structure changes before you commit to them
- Retirement plan designs before you sign with a provider
- Multi-year income and deduction timing before you make business decisions
- State tax consequences before you hire remote employees or open new locations
The software supports both approaches. The economics reward one much more than the other.
Integration with Other Planning Tools
Smart advisors don't use the bna tax planner in isolation. They combine it with financial planning software, entity modeling tools, and cash flow forecasting.
The tax projection feeds into retirement planning. Retirement planning feeds back into tax strategy. Cash flow constraints limit what strategies make sense even if they're tax-optimal on paper.
This integrated approach requires more than software. It requires an advisor who thinks across domains. Who understands that paying zero tax by zeroing out income isn't actually a win if you need to take distributions to live.
Professional tax planning services treat software as one tool in a larger process. Not the process itself.
What This Means for Your Business
If your CPA owns the bna tax planner or similar professional software, ask them how they're using it for your business.
Good answers include:
- "I ran three entity structure scenarios in July and here's what we found"
- "I modeled your retirement plan options and the defined benefit plan saves $35,000 annually"
- "I updated the projection last month when your Q3 revenue came in high"
Bad answers include:
- "I use it to prepare your return"
- "I'll run your projection in February"
- "The software handles the calculations"
The first set indicates strategic planning. The second indicates compliance work dressed up as planning.
Moving from Compliance to Strategy
Most business owners don't need to understand how the bna tax planner works. They need an advisor who uses it properly.
That means finding someone who:
- Plans proactively instead of reacting to last year's return
- Models scenarios before recommending strategies
- Updates projections quarterly as your business changes
- Integrates tax planning with business decisions and personal financial planning
- Charges appropriately for planning work instead of hiding it in compliance fees
The tax code provides planning opportunities every year. Section 199A qualified business income deductions. Retirement plan contribution limits that adjust for inflation. State tax credits for hiring and expansion. Equipment depreciation strategies that shift year to year.
None of these opportunities announce themselves. They exist in the code, waiting for someone to model them against your specific situation and show you the numbers.
Professional software like the bna tax planner makes that modeling possible. Professional advisors make it happen.
The Real Cost of Bad Tax Planning
Tax software prevents mistakes. It doesn't create strategies.
A business owner running $800,000 through a Schedule C instead of an S-corp pays roughly $12,000 annually in unnecessary self-employment tax. The bna tax planner would flag this immediately. But only if someone runs the entity comparison.
A 52-year-old professional with $400,000 of net income could contribute $150,000 to a defined benefit plan. They're probably contributing $27,000 to a SEP-IRA because nobody modeled the alternative. That's $40,000 in lost tax savings annually.
A multi-state business paying California tax on income that should be apportioned to Nevada loses five figures to poor state tax planning. The software handles the apportionment calculation perfectly. If someone asks it to.
These aren't hypothetical examples. They're patterns we see constantly when business owners seek tax planning help after years of compliance-only service.
What Actually Drives Tax Savings
Software enables planning. Planning drives decisions. Decisions create savings.
The bna tax planner is excellent at step one. Most CPAs stop there.
Strategic tax planning requires:
- Understanding business operations well enough to know which strategies fit
- Modeling multiple scenarios to find optimal approaches
- Timing decisions to maximize multi-year benefits
- Coordinating with other professionals when entity changes or retirement plans require legal or financial planning input
- Following through on implementation instead of just recommending ideas
The software supports all of this. It doesn't execute any of it.
That's why the same tool produces wildly different results in different hands. A compliance-focused practitioner generates accurate projections. A strategy-focused practitioner generates actionable plans that cut tax bills by 20-40% compared to default approaches.
The tool is the same. The thinking is different.
| Compliance Approach | Strategic Approach |
|---|---|
| One projection per year | Quarterly updates and scenario testing |
| Current year focus | Multi-year optimization |
| Default entity structure | Modeled entity comparisons |
| Standard retirement plans | Customized plan design |
| Reactive December planning | Proactive mid-year decisions |
Questions to Ask Your Current Advisor
You don't need to become a tax expert. You need to know whether you have one.
Ask your CPA:
- What tax software do you use for projection and planning work?
- How many scenarios did you model for my business this year?
- When did you last update my tax projection?
- Have you modeled different entity structures for my situation?
- What retirement plan options have you compared for me?
The answers tell you whether they're planning or preparing.
If they're using professional software like the bna tax planner but only for compliance work, you're paying for a Ferrari and driving it like a Corolla. The car works fine. You're just not using what you paid for.
If they're not using projection software at all, they're estimating your taxes in spreadsheets. That works until it doesn't. Usually around the time you owe a surprise $60,000 and discover your quarterly estimates were wrong all year.
The Software Your Advisor Should Use
The bna tax planner isn't the only professional tax software. It's one of the established options with a long track record.
Alternatives include Thomson Reuters, CCH ProSystem, Drake, and others. Each has different features, interfaces, and pricing models. All share the same requirement: someone has to actually use them for planning, not just preparation.
According to industry coverage, the shift to web-based platforms made these tools more accessible and easier to update. That solved technical problems. It didn't solve the incentive problem that keeps planning work rare.
The right question isn't which software your advisor uses. It's whether they use any professional planning tool and how often they run it for your benefit.
Professional tax software creates planning opportunities most business owners never see. The bna tax planner and similar tools model scenarios, compare strategies, and project multi-year impacts with accuracy spreadsheets can't match. But the software only works when someone uses it strategically, not just at tax time. Taxt approaches tax planning as an ongoing process, running projections quarterly, modeling entity structures proactively, and testing retirement strategies before you commit to them – turning what most CPAs use for compliance into a planning tool that actually cuts your tax bill.