I hear from people every week who think their tax problem is the end of the world. It usually isn't. I'm Darrin Mish. I've resolved over $100 million in tax debt for clients. Here's what you should know.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Most business owners think about how to get your tax return only when they need to prove income for a mortgage or refinance. That's backward thinking. Your prior year returns are diagnostic tools that reveal planning failures, missed deductions, and structural problems your CPA never flagged.
The real question isn't just accessing the document. It's what you do with it once you have it.
Why You Actually Need Your Old Returns
You don't need last year's return to reminisce about April stress. You need it to see what conventional tax prep missed.
When you get your tax return from previous years, you're looking at a completed transaction. The strategies are locked. The deductions are final. But the patterns show you where money leaked out through lazy structuring.
Here's what prior returns reveal:
- Entity structure inefficiencies (S-corp vs. LLC classification errors)
- Retirement contribution gaps that cost you deductions
- Missed depreciation elections on equipment and property
- Health insurance deduction failures for self-employed owners
- Home office deductions left on the table
Most CPAs file returns. They don't analyze them. The IRS provides transcripts online within minutes, but transcripts only show line items. You need the complete return with schedules to see the full picture.
Your 2025 return, filed this year, is your roadmap for 2026 planning. Not next March. Now.
The Three Ways to Get Your Tax Return
The IRS makes it easier than most business owners realize. The challenge isn't access-it's knowing which version you need.
Option One: Tax Return Transcript
This is the fast route. You can request a transcript online and receive it immediately or within five to ten days by mail.
Tax return transcripts show:
- Adjusted gross income
- Taxable income
- Filing status
- Major line items from each schedule
Transcripts work for mortgage applications and student loan verifications. They don't work for planning analysis because they omit the detail that matters-depreciation methods, carryforward calculations, basis adjustments.
If you need to verify what you filed, transcripts are sufficient. If you're looking for planning opportunities, they're worthless.
Option Two: Return Copy from IRS
This is the complete document. Every schedule, every form, every election. It's also slower and costs money.
The IRS charges $43 per tax year for copies of returns. Processing takes 75 days. You file Form 4506 by mail or fax.
Most business owners shouldn't need this option because they should maintain copies themselves. But if you fired your CPA and they're holding your files hostage, this is your nuclear option.
The better move: Never let this happen. When you get your tax return prepared, demand all supporting schedules and calculations. Store them yourself.
Option Three: Your Own Records
This should be your default. The day your return is filed, you should receive a complete copy with all schedules, depreciation worksheets, and supporting calculations.
If your current preparer doesn't provide this automatically, you're working with the wrong firm. At Taxt, complete documentation is standard because planning requires complete information.
Keep seven years of returns accessible. Not in a box. Not at your accountant's office. In your possession, digital and organized.
What Business Owners Miss When They Get Your Tax Return
Having the return isn't the same as understanding it. Most business owners scan the refund line or balance due and file the document away. That's leaving money on the table.
The Entity Classification Trap
Your return shows how you're classified for tax purposes. Many business owners form LLCs and never make an S-corporation election. They pay self-employment tax on 100% of their net income when they should only pay it on reasonable compensation.
Compare these scenarios for $200,000 net income:
| Entity Type | Self-Employment Tax | Income Tax | Total Tax |
|---|---|---|---|
| LLC (default) | $28,260 | $32,000 | $60,260 |
| S-Corp ($80K salary) | $12,240 | $32,000 | $44,240 |
| Annual Savings | – | – | $16,020 |
This shows up on your return as Schedule C versus Form 1120-S. If you're still filing Schedule C with significant income, you're overpaying. Every year.
The election deadline is March 15 for current-year treatment. Most CPAs mention this once during formation and never again.
Retirement Contribution Failures
Your return shows what you contributed. It doesn't show what you could have contributed.
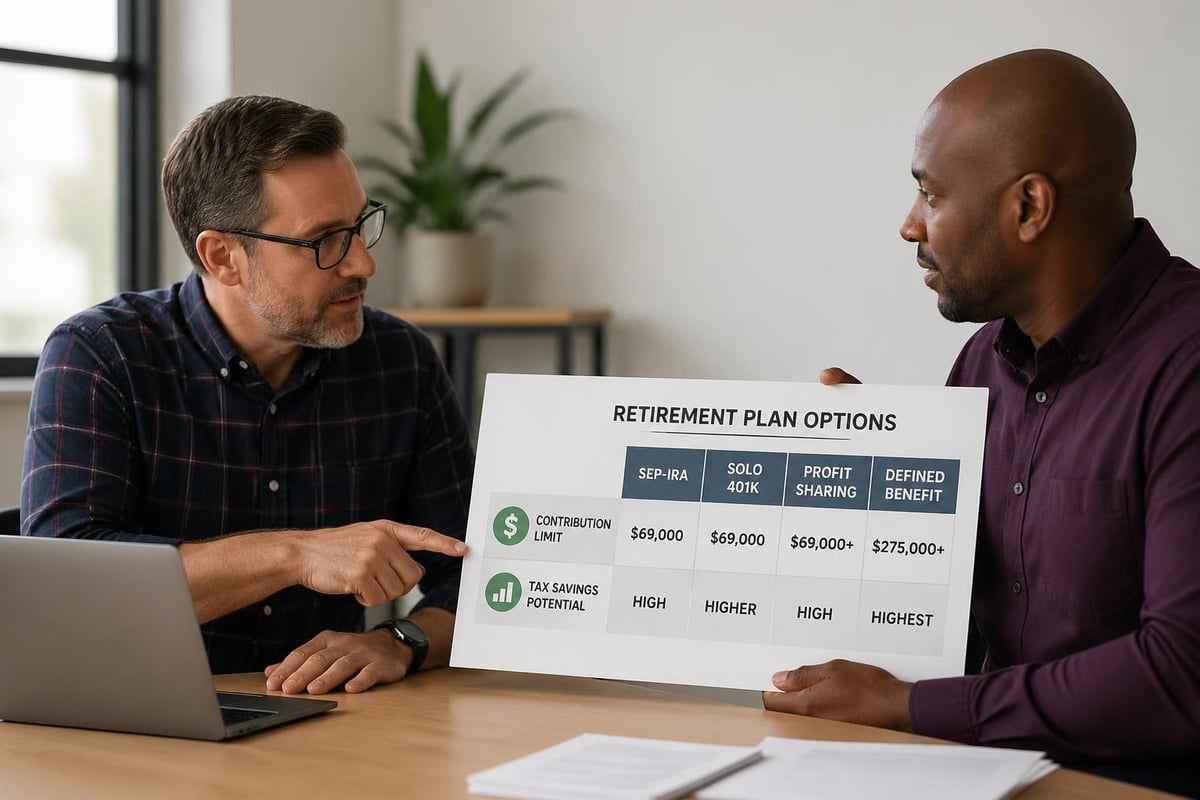
Business owners with profitable S-corporations can establish profit-sharing plans that allow contributions up to $69,000 in 2026 (or $76,500 if over 50). These contributions are deductible and reduce taxable income dollar-for-dollar.
Most returns show:
- SEP-IRA contributions of $23,000 or less
- No defined benefit plan despite income that supports $200,000+ contributions
- Simple IRA instead of 401(k) with profit sharing
- Missed spousal IRA opportunities
The contribution limits are clear. The filing requirements are straightforward. But conventional CPAs stick with simple structures and leave five-figure deductions unclaimed.
Depreciation Election Mistakes
Section 179 and bonus depreciation let you deduct equipment purchases immediately instead of depreciating them over years. Your return shows which elections you made-or didn't make.
When you get your tax return and review Form 4562, you should see:
- Section 179 deduction: Up to $1,220,000 in 2026
- Bonus depreciation: 40% of remaining basis in 2026 (phasing down from prior years)
- Regular depreciation: For items that don't qualify
Most returns show regular depreciation only. Business owners buy vehicles, computers, and equipment but take deductions over five to seven years when they could deduct 60-100% immediately.
This isn't aggressive. It's statutory. But you need to elect it, and you need supporting documentation.
The Strategic Review Process
Getting your return is step one. Analyzing it is where planning begins.
Step One: Compare Year Over Year
Pull your last three returns. Look for trend lines in gross receipts, net income, and effective tax rate.
Red flags:
- Effective rate increasing despite similar income (missed deductions)
- Gross receipts growing but net income flat (expense categorization problems)
- Consistent refunds or payments (withholding and estimated payment failures)
Your effective tax rate should improve as your income grows if you're implementing planning strategies. If it's staying flat or increasing, you're not optimizing structure.
Step Two: Test Entity Structure
Calculate what your tax would have been under different entity classifications. Most business owners never run this analysis.
You can check your refund status to verify processing, but that doesn't tell you if you overpaid by thousands due to wrong structure. You need comparative modeling.
For every $100,000 of net income above $80,000, wrong entity classification costs approximately $7,500 in unnecessary self-employment tax. If you've operated for five years as the wrong entity type, that's $37,500 you can't recover.
The calculation is simple. The missed opportunity is expensive.
Step Three: Audit Your Deductions
Your return shows what you deducted. It doesn't show what you missed.
Common missed deductions for business owners:
- Home office (actual vs. simplified method comparison)
- Vehicle expenses (standard mileage vs. actual, depreciation limits)
- Health insurance (above-the-line deduction for self-employed)
- Retirement plan contributions (multiple plan types available)
- Startup costs and organizational expenses (first-year elections)
The home office deduction alone can generate $5,000-$15,000 in deductions if you're using actual expenses instead of the simplified method. But most preparers default to simplified because it's easier.
Easier for them. Costly for you.
Step Four: Review Carryforwards
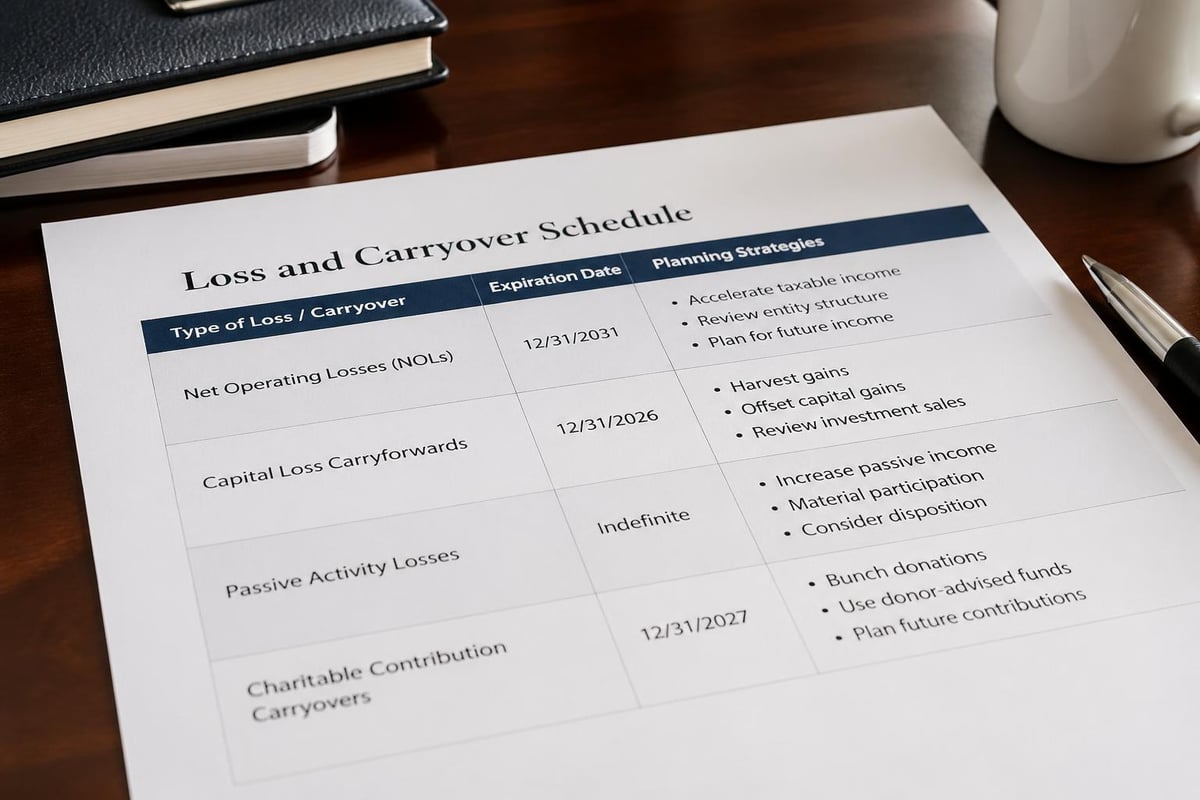
Your return shows unused deductions that carry forward-net operating losses, capital losses, charitable contributions, passive activity losses.
These are future planning tools. If you have $50,000 in passive activity losses carrying forward, you need rental real estate income to unlock those deductions. If you have capital loss carryforwards, you need to plan capital gains recognition.
Most business owners don't know these carryforwards exist. They show up in return footnotes and supporting statements, not on the main form.
The Timing Element Nobody Mentions
When you get your tax return matters for planning purposes. April filing doesn't leave time for current-year adjustments.
The Extension Advantage
Most business owners view extensions as procrastination. That's compliance thinking, not planning thinking.
Filing an extension gives you until October 15 to file your 2025 return. That creates an overlap with Q3 2026 where you can see both years simultaneously and make coordinating moves.
Extension planning opportunities:
- See Q2 2026 results before finalizing 2025 return
- Coordinate retirement contributions across both years
- Time income and deduction recognition
- Make entity election changes before September deadlines
The last-minute filing guidance focuses on compliance. Strategic planners use extensions deliberately.
You still pay estimated tax by April 15. You just don't finalize return positions until you have more information.
Amended Return Planning
If you discover missed opportunities after filing, you can amend. Form 1040-X gives you three years from the original filing date.
Amendments work for:
- Missed deductions (home office, vehicle, equipment)
- Wrong entity classification elections
- Retirement contribution corrections
- Depreciation method changes (with limitations)
Amendments don't work for planning changes that required current-year elections. Once you file without a Section 179 election, you can't amend to add it. The election was due with the original return.
This is why review before filing matters more than review after. The deadline is real.
What Your CPA Isn't Telling You
Most tax preparers optimize for compliance, not tax reduction. They prepare returns that won't trigger audits. They file on time. They answer IRS notices.
They don't proactively analyze structure, test entity classifications, or model alternative scenarios.
When business owners ask me how to get your tax return reviewed properly, the question reveals the problem. You shouldn't need to ask. Strategic review should be built into the service.
The review your preparer should provide includes:
| Review Element | Compliance Prep | Strategic Planning |
|---|---|---|
| Entity structure analysis | Never | Annually |
| Retirement plan optimization | Rarely | Always |
| Multi-year tax projection | Never | Standard |
| Depreciation method testing | Default election | Scenario modeling |
| Estimated payment planning | Penalty avoidance | Cash flow optimization |
| Carryforward tracking | Automated | Actively utilized |
If your current provider delivers only the left column, you're getting commodity service at custom pricing.
The IRS filing guidance covers mechanics. It doesn't cover strategy. That's the difference between tax preparation and tax planning.
The Document Retention Framework
When you get your tax return, storage matters as much as access. The IRS can audit returns for three years (six years for substantial underreporting, indefinitely for fraud or unfiled returns).
Your retention system should include:
- Tax returns (all schedules)
- Supporting documentation (receipts, invoices, contracts)
- Depreciation schedules and worksheets
- Entity formation documents
- Retirement plan documentation
- Prior year carryforward calculations
Paper isn't sufficient. Fire, flood, or simple loss creates problems during audits or when changing preparers.
Digital storage with cloud backup ensures access regardless of circumstances. When you verify your return was received, you're checking IRS processing, not confirming your own records are complete.
Those are separate obligations. Both matter.
Using Returns for Proactive Planning
The diagnostic value of prior returns extends beyond finding mistakes. They're baseline data for multi-year strategy.
Your 2023, 2024, and 2025 returns show income trends, deduction patterns, and structural decisions. Those patterns let you model 2026, 2027, and 2028 scenarios.
Multi-year planning questions your returns answer:
- When should we convert traditional IRA to Roth? (Income dip years)
- When should we recognize deferred income? (Lower rate years)
- When should we accelerate equipment purchases? (High income years)
- When should we harvest capital losses? (Before carryforward expiration)
Single-year preparation optimizes the current return. Multi-year planning optimizes lifetime tax liability. The difference is tens or hundreds of thousands of dollars over a business lifecycle.
Your returns provide the historical data. Forward modeling provides the strategy. Most preparers only do the first part.
The Money-Back Test
When you get your tax return from a planning-focused firm versus a compliance-focused firm, one tangible difference separates them: guarantees.
Compliance firms guarantee they'll file on time and respond to notices. They don't guarantee they'll reduce your tax liability.
Planning firms guarantee savings. If the plan doesn't reduce your tax below what you would have paid with basic preparation, you shouldn't pay for the planning.
This isn't marketing language. It's the difference between delivering value and delivering compliance.
The support resources should explain not just how to access your documents but how to use them for planning. If the FAQ section covers "Where's my refund?" but not "How do I optimize entity structure?", you're working with the wrong type of firm.
Returns are inputs to planning, not outputs of compliance. Treat them accordingly.
The April Mistake
Most business owners think tax planning happens in April when they get your tax return. That's the worst time to plan because you're out of time.
April is when you discover what happened. Planning happens in June through December for the current year and January through March for final adjustments.
The strategic calendar:
- June-July: Review prior year return, identify missed opportunities
- August-September: Model current year scenarios, adjust estimated payments
- October-November: Implement equipment purchases, retirement contributions
- December: Final income/deduction timing moves
- January-March: Last-minute retirement contributions, entity elections
If you're not looking at your return until April 2027 for 2026 taxes, you've missed 12 months of planning opportunities.
The planning moves that matter happen while the year is open, not after it closes. Your prior return shows you what to fix. The current year is when you fix it.
Prior year returns reveal planning failures, but only if you review them strategically instead of filing them away after checking the refund line. The patterns in your returns show entity structure problems, missed deductions, and retirement contribution gaps that cost five or six figures annually. Taxt delivers strategic tax planning that guarantees measurable savings through systematic analysis of what conventional preparation misses, with complete documentation and multi-year modeling built into every engagement.