Stop losing sleep over your tax situation. I'm Darrin Mish — a tax attorney in Tampa who's spent 32 years handling exactly this kind of problem. Here's what you need to know.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Most business owners confuse tax preparation with tax planning. They think learning how to prepare tax means gathering receipts in April and hoping their accountant finds deductions. That's compliance theater, not strategy.
Real tax preparation happens in May, not April. It starts the day after you file when you have 12 months to execute moves that actually matter. Your effective tax rate is determined by January decisions, entity structures set in February, retirement contributions locked in March.
The business owners who pay the least aren't lucky. They're systematic.
When Tax Preparation Actually Begins
You don't prepare tax returns in spring. You prepare tax positions throughout the year.
The IRS knows this. Their year-round tax planning guidance emphasizes quarterly reviews and proactive documentation. Yet most business owners still treat tax prep like a deadline rather than a discipline.
The Real Timeline for How to Prepare Tax
Traditional tax preparation follows a panic schedule. Gather documents in March, meet with your CPA in April, file an extension, scramble until October. You're preparing a return, not preparing a tax strategy.
Strategic preparation runs on a different clock:
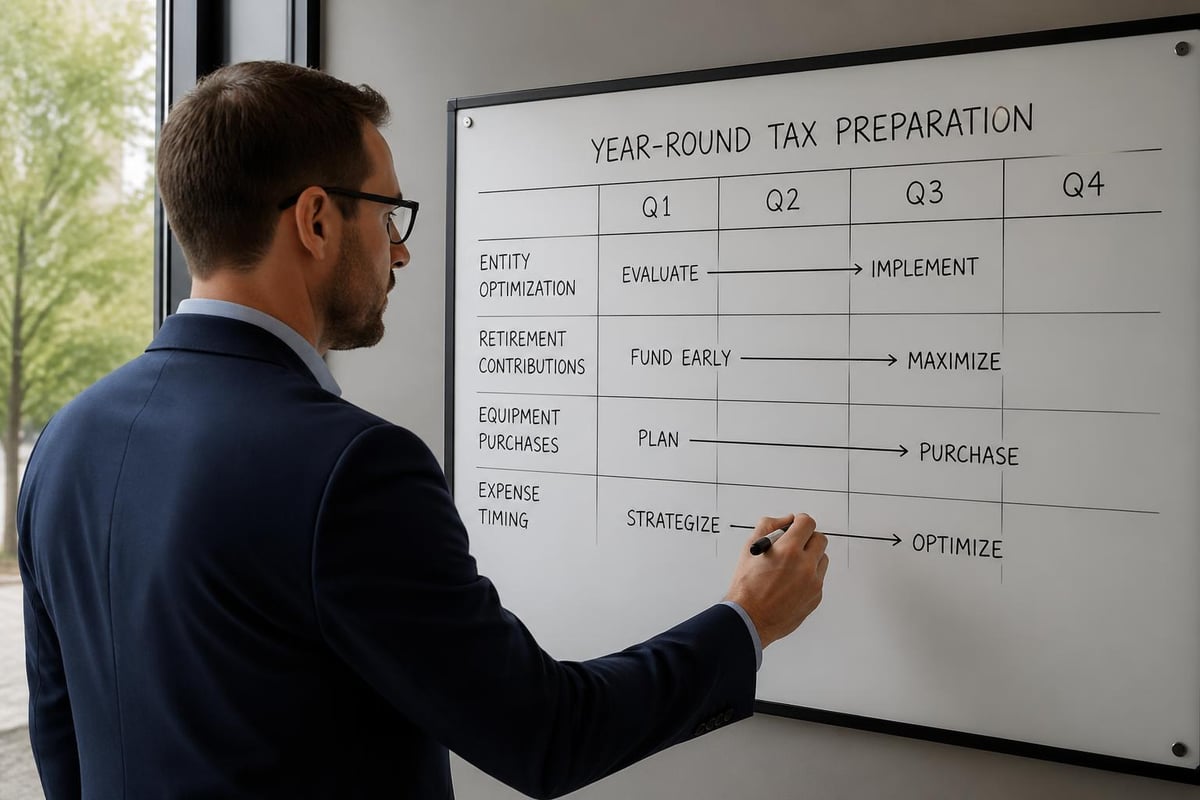
- May-July: Entity structure review, estimated payment calibration, retirement plan optimization
- August-October: Equipment purchases, expense acceleration, income deferral strategies
- November-December: Final contributions, basis adjustments, loss harvesting
- January-March: Documentation assembly, return preparation, next-year strategy mapping
This isn't theoretical. It's how businesses systematically reduce effective rates below statutory minimums.
The Documentation System Nobody Teaches
Learning how to prepare tax properly requires infrastructure most CPAs never mention. You need systems that capture planning opportunities in real time, not after the fact.
Your documentation should flow automatically:
- Transaction categorization at point of entry, not during reconciliation
- Mileage tracking through GPS automation, not handwritten logs
- Receipt digitization within 24 hours, not quarterly box sorting
- Basis tracking for every asset, updated with every transaction
The business owners with the cleanest audits aren't more organized by nature. They built systems that make documentation unavoidable.
Entity Structure and Tax Preparation Strategy
Your entity choice determines which deductions you can take before you earn dollar one. This is the foundation of how to prepare tax with actual strategic leverage.
S-Corp vs. LLC: The Math That Matters
Most business owners elect S-Corp status because someone told them to. They don't understand the actual mechanics or when the structure stops making sense.
| Entity Type | Self-Employment Tax | Reasonable Salary Requirement | Retirement Contribution Limits |
|---|---|---|---|
| Sole Prop/LLC | 15.3% on all profit | None | $69,000 (2026 SEP-IRA) |
| S-Corporation | Only on W-2 wages | Yes, IRS scrutinized | $69,000 + profit-sharing potential |
| C-Corporation | No SE tax on owner | Market-rate compensation | $276,000+ (defined benefit plans) |
The break-even point for S-Corp election sits around $60,000 in net profit. Below that, the compliance cost exceeds the tax savings. Above $250,000, you need to model defined benefit plans and family employment strategies.
This is advanced planning, not basic compliance. Most CPAs prepare returns within existing structures. They don't proactively model restructuring scenarios.
Qualified Business Income Deduction Planning
The Section 199A deduction gives you 20% off qualified business income, but the phase-outs start at $383,900 for married filers in 2026. Proper preparation means managing that threshold before November.
You need to know how to prepare tax positions around these cliffs:
- Income timing: Defer December invoicing to January, accelerate January expenses to December
- W-2 optimization: Increase reasonable compensation to stay below specified service business limitations
- Asset aggregation: Group rental properties with operating businesses to meet participation tests
These moves require quarterly modeling. Your April tax preparer can't execute strategies that needed December implementation.
Retirement Contributions as Tax Preparation
The business owners paying effective rates below 20% aren't finding exotic deductions. They're maxing out retirement vehicles most owners ignore.
Beyond the 401(k): Cash Balance Plans
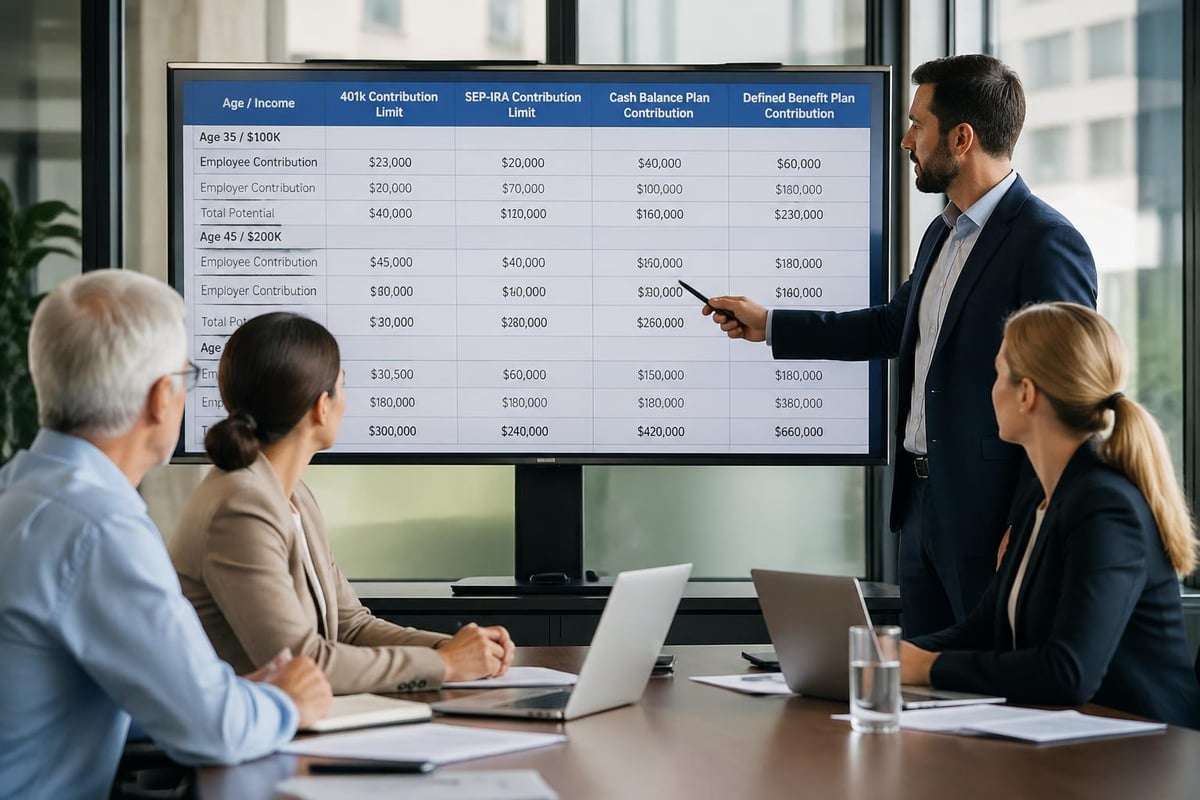
Standard 401(k) limits hit $69,000 in 2026 for those over 50. That's meaningful but insufficient for high-income business owners trying to shelter $400,000+ in annual profit.
Cash balance plans let you contribute based on actuarial calculations, not statutory limits. A 55-year-old business owner can shelter $250,000+ annually with the right plan design.
The preparation requirement: you need two years of stable income history and commitment to fund consistently. This isn't a last-minute strategy. It's structural tax planning that compounds over decades.
Backdoor Roth Conversions and Mega Backdoor Strategies
Traditional tax preparation ignores Roth conversion opportunities. Strategic preparation builds them into quarterly cash flow planning.
The mega backdoor Roth lets you contribute after-tax dollars to a 401(k) beyond the $69,000 limit, then convert them to Roth immediately. You can shelter an additional $50,000+ annually with no income limitations.
Requirements your tax preparer won't mention:
- Your 401(k) plan must allow after-tax contributions
- The plan must permit in-service distributions or conversions
- You need cash flow to make contributions beyond the standard limits
- You must track basis meticulously to avoid double taxation
This is how business owners build eight-figure tax-free retirement accounts. But it requires plan design modifications most CPAs never suggest.
The Quarterly Estimated Payment Strategy
Underpayment penalties hit 8% annually in 2026. Safe harbor rules require 90% of current year tax or 110% of prior year if your AGI exceeded $150,000.
Learning how to prepare tax means understanding these aren't suggestions. They're thresholds that determine whether you're paying the Treasury or the Treasury is penalizing you.
How to Calculate Estimated Payments Strategically
Most business owners divide last year's tax by four and call it done. That's compliance, not optimization.
Strategic quarterly payments account for:
- Income timing variations: Higher Q4 income means higher Q4 payments, not equal quarterly splits
- Deduction acceleration: Large Q3 equipment purchases reduce Q3 and Q4 estimated needs
- Credit generation: Energy credits, R&D credits, employer credits offset quarterly obligations
You should recalculate estimates after every significant business event. New contract signed in July? Adjust Q3 payment. Major expense in September? Reduce Q4 payment.
The IRS filing guidance covers the mechanics of submission, but it doesn't teach you the strategy of timing.
Expense Documentation and Substantiation
The Tax Cuts and Jobs Act eliminated most miscellaneous itemized deductions. What remains must be substantiated with contemporaneous documentation.
"Contemporaneous" is the word that kills most audits. You need records created at the time of expense, not reconstructed during examination.
Business Meal Deduction Rules in 2026
Meals remain 50% deductible for ordinary and necessary business purposes. Entertainment is still dead. The line between them determines audit outcomes.
Deductible meal scenarios:
- Client meetings where business is discussed (requires documentation of attendees and business purpose)
- Travel meals while away from your tax home overnight on business
- Employee meals provided for employer convenience at workplace
Non-deductible entertainment masquerading as meals:
- Golf outings with clients (even if you discuss business)
- Sporting event tickets (even if clients attend)
- Concert tickets for client entertainment
Your tax preparer files the return. You create the documentation trail. Most business owners get this backward.
Home Office Deduction Mechanics
The home office deduction survived tax reform because it's not a miscellaneous itemized deduction. It's a direct business expense reduction if you meet the exclusive use test.
Exclusive and Regular Use Requirements
Your home office must be used regularly and exclusively for business. "Exclusive" means nothing else happens in that space. Not occasionally. Not mostly business. Nothing.
The IRS doesn't care if you have a dedicated room. They care about exclusive use. A corner of your bedroom fails the test. A converted spare bedroom passes.
Calculation methods in 2026:
| Method | Calculation | Maximum Deduction | Documentation Required |
|---|---|---|---|
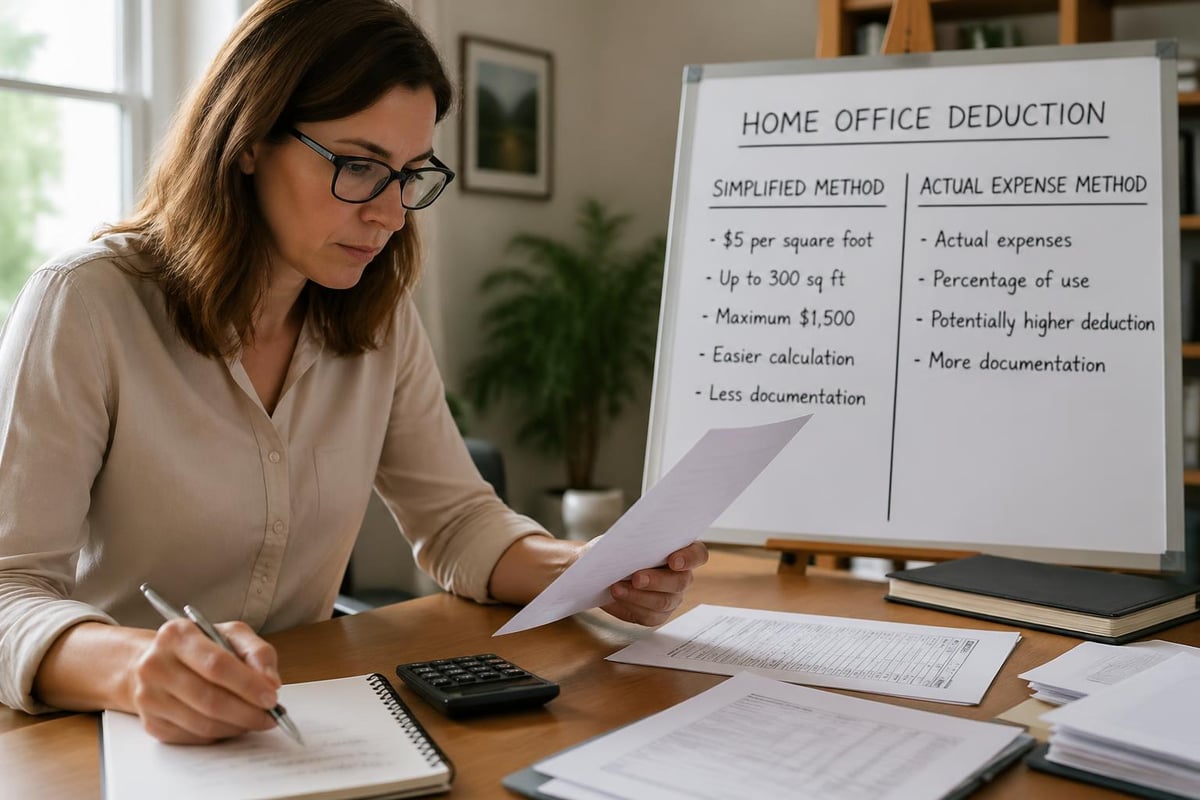
| Simplified | $5 per sq ft | $1,500 | Square footage measurement |
| Actual Expense | Percentage of home expenses | Unlimited | All home expenses, detailed allocation |
The simplified method is easier. The actual expense method saves more for high-cost homes. Understanding how to prepare tax means modeling both scenarios before choosing.
Vehicle Expense Elections and Depreciation
You choose between standard mileage or actual expense in the first year you use a vehicle for business. That election constrains future years.
Standard mileage in 2026: 67 cents per mile. Simple tracking, limited upside. Actual expense: total costs multiplied by business use percentage. Complex tracking, higher deduction potential.
Section 179 and Bonus Depreciation for Vehicles
Vehicles over 6,000 pounds gross vehicle weight qualify for full Section 179 expensing. That's $1,220,000 in 2026 for qualifying property.
Your tax preparer won't tell you to buy a heavy SUV. But if you need a vehicle anyway, understanding weight thresholds changes the tax math completely.
Luxury vehicle depreciation caps still limit passenger vehicles. First-year depreciation for cars is capped around $20,000. The same vehicle over 6,000 pounds? Full expensing of the entire purchase price.
This isn't tax evasion. It's understanding Code sections your compliance-focused CPA doesn't optimize.
How to Prepare Tax with Professional Help
You don't need to understand every Code section. You need to know what questions your tax professional should be asking.
Most business owners hire based on price and proximity. The selection criteria should start with credential verification and planning capability.
Credentials That Actually Matter
Anyone can prepare tax returns. Only specific credentials allow representation before the IRS.
Authorized representatives:
- Enrolled Agents (EA)
- Certified Public Accountants (CPA)
- Tax Attorneys
Enrolled Agents specialize in tax exclusively. CPAs often focus on accounting and audits first, tax second. Tax attorneys handle planning, controversy, and complex entity structures.
The right credential depends on your needs. For straightforward compliance, an EA suffices. For entity structuring and multi-state issues, you want a tax attorney who understands how to prepare tax strategies across jurisdictions.
Choosing between tax professionals requires understanding what strategic planning actually looks like versus basic return preparation.
Questions Your Tax Preparer Should Ask
Your first meeting with a tax professional reveals their planning sophistication. They should ask about:
- Three-year income projections: Planning requires forward-looking analysis, not backward-looking compliance
- Entity structure optimization: Are you in the right structure for your current income level?
- Retirement goals and timeline: Contribution strategies change based on retirement proximity
- Family employment opportunities: Legitimate employment of children and spouses creates deductions
- Equipment and capital expenditure plans: Timing these purchases changes tax outcomes
If your preparer only asks for last year's documents, you hired a compliance clerk, not a planning advisor.
State Tax Considerations in Multi-State Operations
Federal tax preparation is complex. Multi-state operations multiply that complexity geometrically.
Most business owners ignore state tax planning until they face an audit. By then, nexus has been established, liabilities have accrued, and penalty abatement is your only strategy.
Nexus Standards After Wayfair
Physical presence no longer determines state tax obligations. Economic nexus thresholds mean you can owe tax in states you've never visited.
Standard economic nexus: $100,000 in sales or 200 transactions. But thresholds vary by state, and some states add factor presence tests that trigger nexus below economic thresholds.
When you're learning how to prepare tax across multiple states, you need to track:
- Sales by destination state
- Physical presence days for income tax nexus
- Property locations for property tax obligations
- Payroll by work location for employer obligations
Your federal tax preparer might not track state obligations. Most don't. This is where strategic planning separates from compliance checking.
Record Retention and Audit Defense
The IRS generally has three years to audit returns. Substantial understatement of income extends that to six years. Fraud eliminates the statute entirely.
Your record retention should assume audit, not hope for avoidance.
What to Keep and How Long
Standard retention schedule:
- Tax returns: Permanently
- Substantiating documents: 7 years minimum
- Asset basis records: Until statute expires on disposition year plus 3 years
- Employment tax records: 4 years minimum
Digital storage eliminates the space excuse. Cloud-based systems with automated retention policies remove the discipline requirement.
The business owners who win audits didn't get lucky. They maintained contemporaneous records that support every position taken. For help setting up systems that work, Taxt’s support resources walk through documentation best practices most CPAs never formalize.
Tax Law Changes and Planning Adjustments
Tax law shifts constantly. The Tax Cuts and Jobs Act provisions start expiring in 2026. Bonus depreciation phases down. Individual rate cuts sunset. Planning strategies that worked in 2024 might fail in 2027.
Understanding how to prepare tax means building flexibility into your planning infrastructure. You need systems that adapt to law changes, not strategies that assume static rules.
Monitoring Legislative Changes
Tax legislation moves slowly until it doesn't. The 2017 TCJA passed in December and took effect January 1, 2018. Business owners had weeks to restructure.
You should monitor:
- Proposed regulations: These signal IRS interpretation before finalization
- Revenue procedures and revenue rulings: These provide IRS positions on specific transactions
- Tax Court decisions: These establish precedent for contested positions
- State conformity updates: States often decouple from federal changes
Most business owners learn about tax changes from their preparer in April. By then, you've missed 12 months of planning runway. The wealthy understand overlooked strategies because they monitor changes proactively.
Estimated Tax Payment Timing Strategies
Quarterly estimated payments create planning opportunities most business owners miss. The payments aren't truly quarterly-they're due in uneven intervals.
The Uneven Quarterly Schedule
2026 estimated tax deadlines for calendar-year taxpayers:
- April 15 (covering January-March income)
- June 16 (covering April-May income)
- September 15 (covering June-August income)
- January 15, 2027 (covering September-December income)
Notice the final quarter extends into the following year. This creates a four-week window where you can make retirement contributions, purchase equipment, or accelerate expenses that reduce the required January payment.
Strategic timing means keeping cash liquid until you finalize fourth-quarter planning moves. Most business owners pay estimates mechanically. Smart operators treat the January payment as their final planning checkpoint.
Self-Employment Tax Reduction Strategies
Self-employment tax hits 15.3% on net earnings up to $176,100 in 2026, then 2.9% on all earnings above that threshold. For high-income business owners, this exceeds their income tax liability.
The most effective strategy remains S-Corporation election with reasonable salary planning. But "reasonable" is subjective, and the IRS increasingly challenges low-salary, high-distribution structures.
Reasonable Compensation Analysis
Industry compensation data determines reasonable salary ranges. The IRS expects you to pay yourself what an employee performing your functions would earn.
Factors the IRS considers:
- Training and experience required for your role
- Time and effort devoted to the business
- Dividend history and distributions to shareholders
- Comparable salaries paid by similar businesses
- Compensation paid in prior years
If you pay yourself $40,000 and take $300,000 in distributions, your structure invites scrutiny. Proper documentation requires compensation studies, industry data analysis, and contemporaneous board resolutions supporting your salary decision.
This is planning work, not return preparation. It happens in May, not April.
The Five-Step Planning Process
Tax preparation shouldn't be transactional. It should be systematic.
Strategic planning follows a repeatable process:
- Income and deduction forecasting: Model expected tax liability under current trajectory
- Entity structure optimization: Evaluate whether your current structure minimizes tax at your income level
- Retirement and benefit planning: Maximize tax-deferred contributions and fringe benefits
- Timing strategy execution: Implement expense acceleration and income deferral moves
- Compliance and documentation: Ensure positions taken are substantiated and defensible
This process runs continuously, not once annually. Quarterly reviews catch planning opportunities while you still have time to execute.
Most tax professionals skip steps one through four and call step five "tax preparation." That's why most business owners overpay.
Equipment and Asset Purchase Timing
Section 179 expensing and bonus depreciation create immediate deductions for qualifying property. But these benefits require planning around acquisition and placed-in-service dates.
Property must be acquired and placed in service by December 31 to claim deductions for that year. "Acquired" means ownership transferred. "Placed in service" means ready and available for use.
Qualifying Property Requirements
Section 179 in 2026 allows $1,220,000 in immediate expensing with a phase-out beginning at $3,050,000 in total purchases.
Qualifying property includes:
- Tangible personal property used in business
- Off-the-shelf computer software
- Qualified improvement property
- Some vehicles over 6,000 pounds GVWR
Non-qualifying property:
- Real property (buildings)
- Property held for investment
- Property acquired from related parties
The strategy isn't buying equipment you don't need for tax deductions. It's timing purchases you planned anyway to optimize current-year tax liability.
For help modeling whether accelerating purchases makes sense for your specific situation, planning professionals who understand how to lower your overall tax bill should run multiple scenarios before you commit capital.
Passive Activity Loss Limitations
Rental real estate and passive business interests generate losses that can't offset active business income unless you qualify for real estate professional status or meet material participation tests.
Most business owners don't understand these limitations until they file returns and discover their rental losses don't reduce tax liability.
Real Estate Professional Status Requirements
To qualify as a real estate professional for tax purposes, you must spend:
- More than 50% of your personal service time in real property trades or businesses
- More than 750 hours in real property trades or businesses
Both tests must be satisfied. And you must track contemporaneous time logs that substantiate the hours claimed.
For business owners operating companies outside real estate, this status is nearly impossible to achieve. You'd need to reduce time in your operating business below your real estate activities.
Alternative strategy: Ensure rental properties generate income, not losses, through proper rent-setting and expense timing.
Health Savings Account Maximization
HSAs provide triple tax benefits: deductible contributions, tax-free growth, and tax-free distributions for qualified medical expenses. They're the most tax-efficient savings vehicle available.
2026 HSA contribution limits: $4,150 individual, $8,300 family, plus $1,000 catch-up for those over 55.
HSA as Stealth Retirement Account
Most people use HSAs as spending accounts. Strategic users treat them as supplemental retirement vehicles.
The strategy: pay current medical expenses from taxable accounts, let HSA balances grow tax-free for decades, then reimburse yourself for those expenses in retirement with tax-free distributions.
There's no statute of limitations on medical expense reimbursement. Expenses incurred 30 years ago can be reimbursed tax-free today if you maintained receipts.
This requires discipline and documentation most taxpayers lack. But for business owners who understand how to prepare tax strategically, HSAs become another wealth-building tool disguised as insurance.
Strategic tax preparation isn't about finding deductions your CPA missed-it's about building planning systems your CPA never suggested. The business owners paying the lowest effective rates aren't working with more aggressive preparers; they're executing strategies throughout the year that make April filing a formality. Taxt specializes in this systematic approach, helping business owners implement the five-step planning process that reduces tax liability, eliminates April anxiety, and builds long-term wealth with a money-back guarantee if the savings don't materialize.