Most of what you've read online about IRS problems is wrong, or at least misleading. I'm Darrin Mish. I practice tax law in Tampa and I've been doing this for 32 years. Here's what's actually true.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your pre tax 401k does exactly what it says. It takes money before the IRS touches it. Every dollar you contribute drops your taxable income by exactly one dollar.
Most business owners know this much. What they don't understand is the timing trade. You're not avoiding tax. You're postponing it. The IRS gets its cut later, when you withdraw, at whatever rates exist then.
That's the whole game. Pay tax now or pay tax later. The right answer depends on math most CPAs won't walk you through.
How Pre Tax 401k Contributions Actually Work
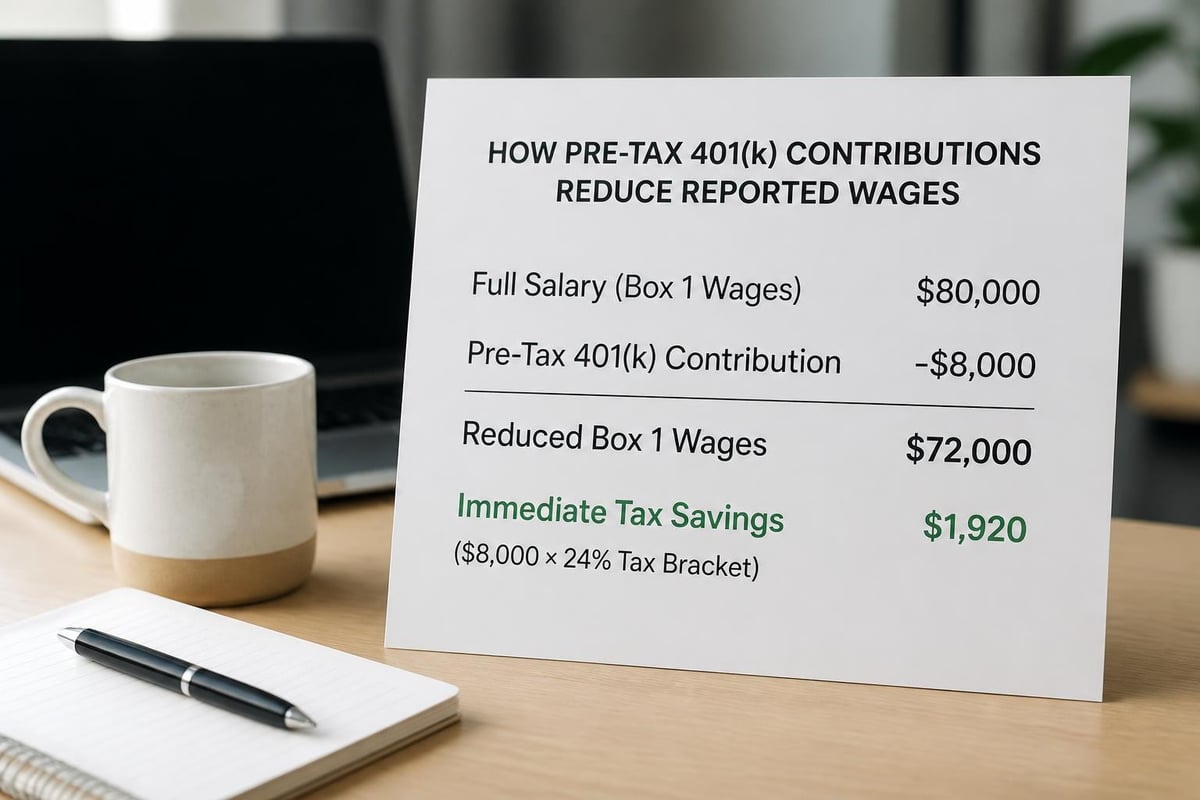
You earn $150,000. You put $23,000 into your pre tax 401k in 2026. The IRS only sees $127,000 of income. That's the immediate benefit, and it's real.
Your employer reports the full $150,000 on your W-2 in Box 1, then subtracts your elective deferrals. Box 1 shows $127,000. That's your taxable wage base. Social Security and Medicare taxes still hit the full $150,000, but federal and state income tax only touch what's left after your contribution.
The IRS overview of 401(k) plans lays out the mechanics. Elective deferrals go in pre-tax unless you specifically choose Roth treatment. Most plans default to pre-tax. You have to opt into Roth.
Contribution Limits and Employer Matching
The 2026 employee contribution limit is $23,000 if you're under 50. Add $7,500 if you're 50 or older. That's the catch-up provision. Total limit including employer contributions is $69,000, or $76,500 with catch-up.
Employer matches don't count against your $23,000 limit. They count against the total $69,000 limit. And here's what matters: employer contributions are always pre-tax, even if you're making Roth employee contributions.
You can't choose how employer money gets taxed. It goes in pre-tax, grows tax-deferred, and comes out taxable. No exceptions.
| Contribution Type | 2026 Limit (Under 50) | 2026 Limit (50+) | Tax Treatment |
|---|---|---|---|
| Employee elective deferrals | $23,000 | $30,500 | Pre-tax or Roth |
| Employer contributions | Counts toward total | Counts toward total | Always pre-tax |
| Total (employee + employer) | $69,000 | $76,500 | Mixed |
Most business owners I work with max employee deferrals but don't think about the employer side. If you control the business, you control both. That's where real planning happens.
The Tax Arbitrage Everyone Misses
Here's the planning question: Will your tax rate be higher or lower when you withdraw than it is today?
If lower, pre-tax wins. If higher, Roth wins. Simple in theory. Impossible to know for certain in practice.
You're guessing at future tax law. You're guessing at your future income. You're guessing at your future deductions. Most CPAs punt and say "diversify between pre-tax and Roth." That's not strategy. That's surrender.
When Pre Tax 401k Makes Sense
You're in your peak earning years. You're a W-2 business owner pulling $300,000 or more. Your marginal federal rate is 35%. California or New York tacks on another 10%-13% state tax. You're paying close to 48% on the top slice of income.
In retirement, you'll have Social Security, maybe a pension, and 401k withdrawals. Let's say you need $120,000 a year. Most of that income sits in the 22% or 24% federal bracket. State tax might drop if you move. You could be looking at a combined 30% rate.
You saved 48% going in. You pay 30% coming out. That's an 18-point spread. The math works even if tax rates rise slightly.
Pre-tax contributions also make sense if you expect large deductions in retirement. Charitable gifts, mortgage interest if you buy late, medical expenses. These reduce taxable income and make room for tax-free or low-tax withdrawals.
When It Doesn't
You're early career. You're in the 22% bracket today. You're building a business that could triple your income in ten years. Your future tax rate will almost certainly exceed your current rate.
Or you're already retired, living on minimal income, and considering a late-career consulting gig. That income could push Social Security taxation and Medicare premiums higher. The marginal cost of additional income in retirement sometimes exceeds 40% when you account for those phase-outs.
In both cases, paying tax now at a known lower rate beats deferring to an unknown higher rate.
Tax-Deferred Growth and Compound Interest
Everything inside your pre tax 401k grows without annual tax. Stock dividends, bond interest, capital gains from rebalancing. None of it triggers a tax bill while it's inside the account.
That's the second benefit after the upfront deduction. And it compounds hard over time.
Outside a 401k, if you earn a 7% return and pay 24% tax on dividends and realized gains each year, your effective after-tax return drops to around 5.3%. Inside the 401k, you keep the full 7%. Over 30 years, that difference is enormous.
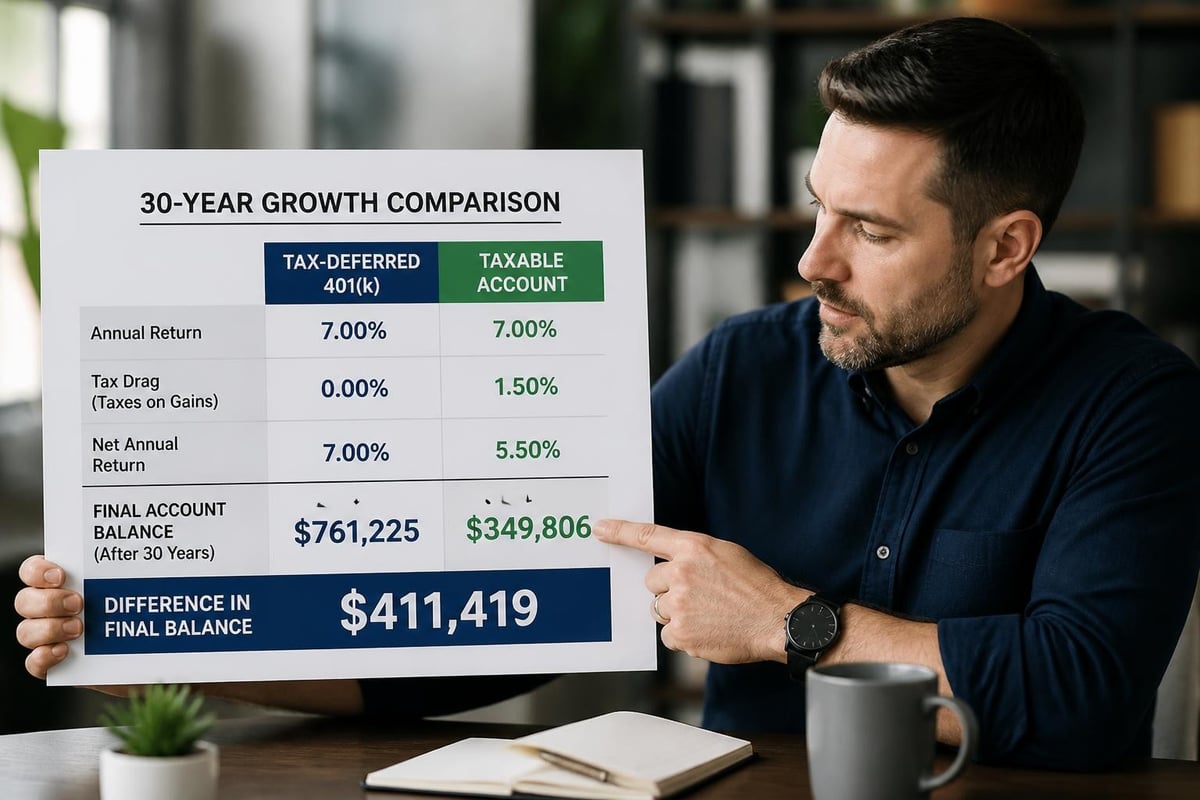
A $10,000 contribution growing at 7% becomes $76,123 in 30 years. The same $10,000 growing at 5.3% after tax becomes $47,609. The deferral added $28,514, and that's before you account for the initial tax deduction.
Vanguard’s explanation of how workplace plans cut taxes walks through these compounding benefits clearly. Most people fixate on the immediate deduction and miss the growth component entirely.
The Back-End Tax Bill
Here's what you owe when you pull money out. Every dollar you withdraw gets added to your taxable income for that year. It's ordinary income, taxed at your marginal rate.
Not capital gains. Not qualified dividends. Ordinary income, the same as wages.
You could contribute at 22%, watch it grow for 30 years, and withdraw at 37% if tax rates rise or your other income is higher than expected. That's the risk.
You also face required minimum distributions (RMDs) starting at age 73 under current law. The IRS forces you to take money out and pay tax whether you need the cash or not. Large pre-tax balances create large forced taxable withdrawals in your 70s and 80s.
Withdrawal Rules and Penalties
Pull money out before age 59½ and you pay a 10% early withdrawal penalty on top of ordinary income tax. There are exceptions, but they're narrow.
The main ones:
- Separation from service at age 55 or later. Applies only to the 401k from that employer.
- Total and permanent disability. Requires IRS definition, not just inability to do your old job.
- Substantially equal periodic payments (SEPP). Locks you into a payment schedule for at least five years or until age 59½, whichever is longer.
- Medical expenses exceeding 7.5% of adjusted gross income. Only the excess qualifies.
Most business owners don't qualify for any of these. If you need the money early, you pay the penalty unless you roll to an IRA and use a SEPP or one of the narrow IRA exceptions.
IRS Publication 525 covers taxable and nontaxable income, including retirement distributions and the taxation of early withdrawals. You'll find the full rule set there, but it doesn't make for light reading.
Loans vs. Withdrawals
Many 401k plans allow loans. You borrow from yourself, pay yourself back with interest, and avoid the 10% penalty. Sounds attractive. Usually isn't.
The loan limit is the lesser of $50,000 or 50% of your vested balance. Repayment term is typically five years, though it extends to 15 years if you're buying a primary residence. If you leave the employer or default, the outstanding balance becomes a taxable distribution plus the 10% penalty if you're under 59½.
Here's the hidden cost: you repay the loan with after-tax money. Then when you withdraw in retirement, you pay tax again on the same dollars. Double taxation on the principal you repaid.
You also lose the tax-deferred growth on the borrowed amount. If the market returns 8% and your loan charges you 5% interest, you're paying yourself 3% less than the account would have earned. That opportunity cost is real and permanent.
Pre Tax 401k vs. Roth 401k
More plans now offer Roth 401k contributions. Same $23,000 limit, but you pay tax going in and take it out tax-free in retirement.
The comparison is straightforward:
| Feature | Pre-Tax 401k | Roth 401k |
|---|---|---|
| Tax on contributions | Deductible now | No deduction |
| Tax on growth | Deferred | Tax-free |
| Tax on withdrawals | Fully taxable | Tax-free (if qualified) |
| RMDs | Required at 73 | Required at 73 (but can roll to Roth IRA to avoid) |
| Best for | High earners expecting lower rates later | Lower earners expecting higher rates later |
Fidelity’s guide to 401(k) taxes breaks down the comparison in detail. The short version: it's a bet on your future tax bracket.
Most high-income business owners I work with split contributions. Max the pre-tax 401k if they're in the top brackets today. Add Roth after-tax contributions if the plan allows and they expect tax rate risk.
After-Tax Contributions and Mega Backdoor Roth
Some plans allow after-tax (not Roth) contributions above the $23,000 limit, up to the total $69,000 limit. You get no deduction. Growth is tax-deferred. Withdrawals are pro-rata taxable.
The planning move is the mega backdoor Roth: make after-tax contributions, then immediately convert them to Roth (either in-plan or by rolling to a Roth IRA). You pay no tax on the conversion because there's no gain yet. Now it grows tax-free forever.
This only works if your plan allows:
- After-tax contributions beyond the $23,000 employee limit
- In-service distributions or in-plan Roth conversions
Most small business 401k plans don't. Large company plans sometimes do. If you control the business and want this feature, you design the plan to allow it.
Business Owner Considerations
If you're self-employed or control your business, you're on both sides of the 401k. You're the employee making elective deferrals. You're also the employer making matching or profit-sharing contributions.
That means you control contribution amounts, vesting schedules, and plan design. You also eat the administrative cost and fiduciary responsibility.
Solo 401k vs. Employer Plans
A solo 401k works if it's just you, or you and a spouse. You can contribute as employee (up to $23,000) and as employer (up to 25% of compensation, subject to the $69,000 total limit). Low cost, minimal administration, full control.
Once you hire employees, you need a full employer plan. Now you have nondiscrimination testing, employee eligibility, vesting, and annual 5500 filings. Costs jump from a few hundred to several thousand per year depending on plan size.
Pre-tax 401k contributions are the same either way. The difference is administrative complexity and cost.
Nondiscrimination Testing
If you have employees, the IRS tests whether your plan favors highly compensated employees (HCEs). HCEs are anyone earning over $155,000 in 2026 or owning more than 5% of the business.
The two main tests:
- Actual Deferral Percentage (ADP) test: compares HCE vs. non-HCE employee contribution rates
- Actual Contribution Percentage (ACP) test: compares HCE vs. non-HCE employer contribution rates
If your plan fails, you have to refund excess contributions to HCEs or make additional contributions to non-HCEs. Both are expensive and annoying.
Safe harbor plans bypass testing by requiring minimum employer contributions (either 3% non-elective or 4% match). You pay more in employer contributions, but you eliminate testing risk.
For business owners who want to max their own pre tax 401k contributions without testing headaches, safe harbor is usually worth the cost.
Common Mistakes and Missed Opportunities
Most business owners set a contribution percentage when they enroll and never revisit it. They leave employer match on the table or under-contribute because they don't understand the limits.
Biggest mistakes I see:
- Contributing just enough for the employer match and stopping there
- Ignoring catch-up contributions after age 50
- Not adjusting contributions when income jumps
- Failing to coordinate 401k strategy with other tax planning (Roth conversions, capital gains harvesting, etc.)
- Treating the 401k as set-it-and-forget-it instead of an active planning tool
The pre tax 401k isn't just a savings account. It's a tax timing device. Use it strategically or you're leaving money on the table.
Rollovers and Consolidation
Old 401k accounts sitting with former employers are a planning liability. You lose control, forget about them, and miss opportunities to convert or reposition.
Roll old 401k balances into your current employer plan or into a traditional IRA. Consolidation gives you visibility and control. It also simplifies required minimum distributions later.
Watch the pro-rata rule if you're doing backdoor Roth IRA contributions. Traditional IRA balances make backdoor Roths partially taxable. But 401k balances don't count. If you're doing backdoor Roths, keep your traditional IRA at zero and roll old 401k money into your current employer plan instead of an IRA.
Real Planning Means Coordinating Everything
Your pre tax 401k doesn't exist in isolation. It sits inside a bigger structure: current income, future income, Social Security timing, Roth conversions, taxable investment accounts, business income, state residency.
Tax planning means looking at the whole board. The move that saves tax this year might cost you more over ten years. The contribution that makes sense in your 30s might be wrong in your 50s.
This is where most CPAs stop. They handle compliance. They file your return. They tell you the rules. They don't show you the second-order effects or walk through the ten-year projection.
That's what planning is. It's scenario modeling. It's "what if we do this now and that in three years." It's making moves today that set up better moves later.
The pre tax 401k cuts your tax bill today and builds tax-deferred wealth. But you're not avoiding tax. You're timing it. The right timing depends on rate arbitrage, future income, and planning moves your CPA probably isn't showing you. If you want a tax strategy that looks past April 15 and actually builds wealth, we should talk. Taxt focuses on planning, not just compliance, and the five-step process is built to find the moves that actually matter for business owners.