Most of what you've read online about IRS problems is wrong, or at least misleading. I'm Darrin Mish. I practice tax law in Tampa and I've been doing this for 32 years. Here's what's actually true.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
You left your job. Rolled your 401(k) into a traditional IRA. Smart move at the time. Now you're wondering if a rollover IRA to Roth IRA conversion makes sense. The answer depends on your current tax bracket, retirement timeline, and how you expect tax rates to change.
The decision isn't complicated, but it's consequential. You're choosing between paying tax now or paying it later. Most business owners miss the strategic window because their CPA never brings it up.
Why Convert a Rollover IRA to Roth
The mechanics are simple. You take money sitting in a traditional rollover IRA and move it to a Roth IRA. The IRS treats this as taxable income in the year you convert. You pay ordinary income tax on the converted amount.
What you get in return: tax-free growth forever. No required minimum distributions at 73. No tax on withdrawals in retirement. Your heirs inherit it tax-free under current law.
The case strengthens when you expect higher tax rates ahead. Either because your income will increase, or because Congress will raise rates. Converting locks in today's rate.
When a Rollover IRA to Roth IRA Makes Strategic Sense
Best conversion years share three characteristics:
- Your taxable income is temporarily lower than usual
- You have cash outside the IRA to pay the tax
- You won't need the money for at least five years
Sold your business and taking a year off? Convert. Between jobs? Convert. First year of retirement before Social Security and RMDs kick in? Convert.
The IRS rules on rollovers allow unlimited conversion amounts. You can convert $10,000 or $1 million. The only limit is your tolerance for the tax bill.
Many business owners convert in chunks. $50,000 this year, another $50,000 next year. You control the timing and the tax hit.
The Tax Bill You Cannot Avoid
You must pay tax on every dollar converted from a rollover IRA to Roth IRA. No exceptions. The converted amount gets added to your ordinary income for the year.
Convert $100,000 while earning $200,000? The IRS sees $300,000 of income. Your effective rate on that conversion will likely exceed your marginal rate because you're pushing income into higher brackets.
| Conversion Amount | Added to Income | Typical Tax Cost (24% bracket) | Typical Tax Cost (32% bracket) |
|---|---|---|---|
| $25,000 | $25,000 | $6,000 | $8,000 |
| $50,000 | $50,000 | $12,000 | $16,000 |
| $100,000 | $100,000 | $24,000 | $32,000 |
| $250,000 | $250,000 | $60,000+ | $80,000+ |
The actual cost varies based on deductions, other income, and state tax. Run the numbers before you convert. Most business owners underestimate the hit.
Pay the Tax From Outside Accounts
Never use IRA money to pay the conversion tax. If you're under 59½ and withdraw money to cover the tax, that withdrawal triggers a 10% early withdrawal penalty on top of the income tax.
You need cash in a taxable account to write the check to the IRS. No cash available? Don't convert. Taking a loan to pay conversion tax is strategic malpractice.
The math only works when you pay the tax from funds that would have been taxable anyway. Using Roth money to pay the tax defeats the entire purpose.
How the Pro-Rata Rule Changes Everything
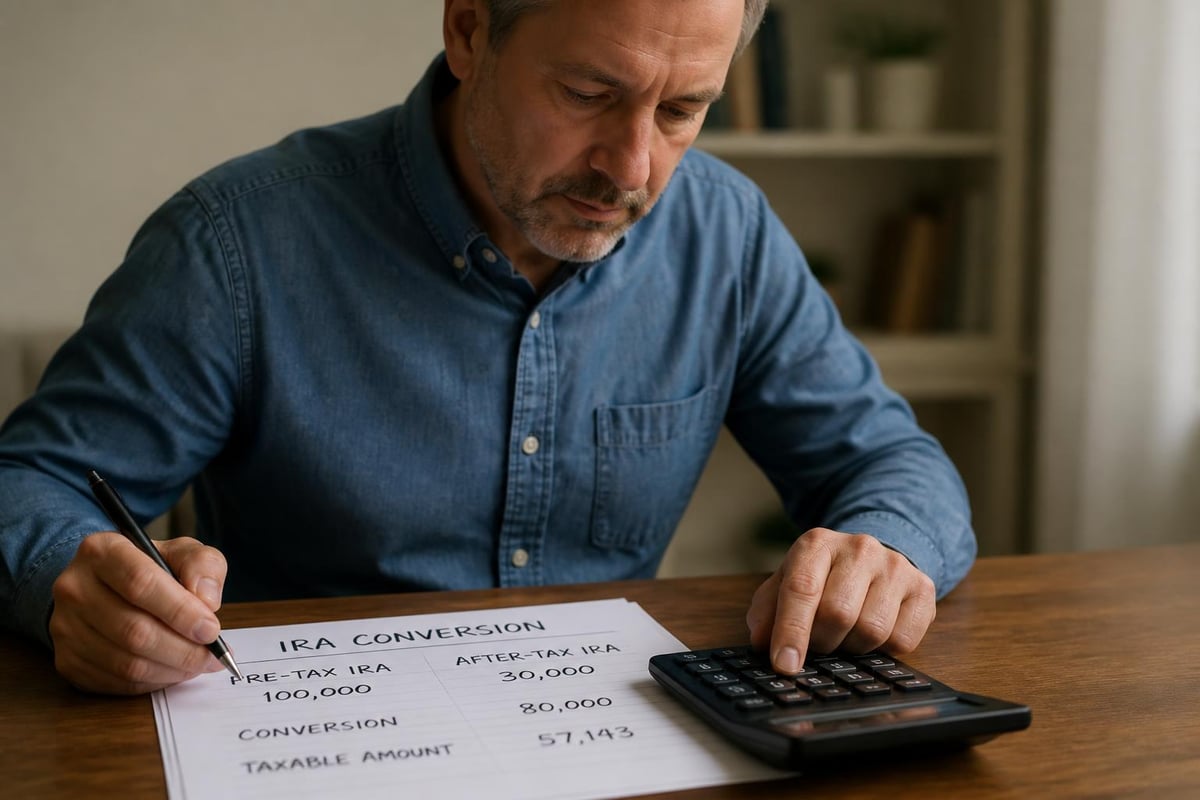
Here's where most conversions get complicated. If you have both pre-tax and after-tax money in traditional IRAs, the IRS makes you convert them proportionally. You cannot cherry-pick the tax-free portion.
The regulatory framework governing conversions treats all your traditional IRAs as one account. Doesn't matter if you have five different accounts at three different brokers. The IRS aggregates them.
Example calculation:
You have $400,000 in traditional IRAs (all pre-tax) and made a $6,000 non-deductible contribution this year. Total IRA balance: $406,000. After-tax basis: $6,000.
You want to convert $50,000 to Roth. The taxable portion is calculated as:
($400,000 ÷ $406,000) × $50,000 = $49,261 taxable
Only $739 converts tax-free. The pro-rata rule killed the benefit of that after-tax contribution.
The Backdoor Roth Strategy
High earners cannot contribute directly to a Roth IRA. Income limits phase out the ability at $161,000 for single filers in 2026, $240,000 for married filing jointly.
The workaround: contribute to a non-deductible traditional IRA, then immediately convert to Roth. Works perfectly if you have no other traditional IRA balances. The pro-rata rule doesn't apply when you have no pre-tax money.
Business owners with large rollover IRAs cannot use this strategy effectively. The pro-rata rule applies to all traditional IRA balances, including rollovers. Converting a $7,000 non-deductible contribution when you have $500,000 in a rollover IRA results in almost all of the conversion being taxable.
Required Minimum Distributions and Conversion Timing
Traditional IRAs force you to start taking required minimum distributions at age 73 under current law. The IRS requires you to withdraw a percentage each year, calculated by your age and account balance.
Roth IRAs have no RMDs during your lifetime. Your money grows tax-free forever if you don't need it. This makes a rollover IRA to Roth IRA conversion particularly valuable if you have other retirement income.
Key timing rule: You must take your RMD before converting in any year you're subject to RMDs. Cannot convert the RMD itself. The IRS requires the RMD to come out first, then you can convert additional amounts.
Business owners in their early retirement years (60-72) have a golden conversion window. No more W-2 income, not yet taking RMDs. Income often drops substantially. Tax brackets open up. Convert aggressively during these years.
State Tax Complications Most CPAs Miss
Every state treats Roth conversions differently. Some have no income tax at all. Others hammer conversions at rates exceeding 10%.
Florida, Texas, Nevada, Washington? No state income tax. Your conversion cost is purely federal. California, New York, New Jersey? Add another 8-13% to the bill.
| State | Top Rate on Conversions | Notes |
|---|---|---|
| Florida | 0% | No state income tax |
| Texas | 0% | No state income tax |
| California | 13.3% | Applies to conversions over $1M |
| New York | 10.9% | NYC adds another 3.876% |
| New Jersey | 10.75% | No deduction for federal tax paid |
Some states let you deduct IRA contributions but tax the back end. Others tax going in and coming out. Moving states before or after conversion can save six figures on large conversions.
Planning a move from a high-tax to no-tax state? Convert after you establish residency. The tax savings often exceed $100,000 on a $1 million conversion.
The Five-Year Rules That Trip Everyone Up
Roth IRAs have two different five-year rules. Most business owners confuse them. Both matter when you convert a rollover IRA to Roth IRA.
Rule One: You must wait five years from January 1 of the conversion year before withdrawing converted amounts penalty-free if you're under 59½. Convert in 2026, you cannot touch those converted dollars until 2031 without a 10% penalty. The tax-free earnings require five years from your first Roth contribution ever.
Rule Two: The account must be open five years before withdrawals are completely tax-free and penalty-free, measured from your first Roth contribution. This applies regardless of your age.
Convert multiple years? Each conversion has its own five-year clock. Convert $50,000 in 2026 and another $50,000 in 2027? Two separate waiting periods.
Strategic Considerations When Converting
Several key factors determine whether a rollover IRA to Roth IRA makes financial sense. You need time for tax-free growth to overcome the upfront tax cost. Convert at 70? The math rarely works. Convert at 45? Much stronger case.
You need lower rates now than later. Converting at a 35% marginal rate hoping to avoid a 24% rate in retirement is backwards.
Consider your estate plan. Heirs inherit Roth IRAs with the same tax-free treatment. Under current law, they must empty the account within 10 years, but pay no income tax on withdrawals. Traditional IRAs force your heirs to pay income tax on every dollar.
Medicare premiums increase at certain income thresholds. Large conversions can push you into higher IRMAA brackets, costing thousands in additional Part B and Part D premiums two years later.
Partial Conversions and Bracket Management
You don't convert everything at once. Smart business owners convert just enough to fill up their current bracket without spilling into the next.
2026 Federal Brackets (Married Filing Jointly):
- 24% bracket tops out at $383,900
- 32% bracket tops out at $487,450
- 35% bracket tops out at $731,200
If your taxable income before conversion is $300,000, you have $83,900 of room in the 24% bracket. Convert that amount. Stop there. The next dollar gets taxed at 32%.
Repeat annually. Convert $80,000 per year for five years instead of $400,000 all at once. You pay 24% on everything instead of pushing half into the 32% or 35% brackets.
Market Timing and Conversion Opportunities
Market drops create conversion opportunities. Your IRA balance is down 30%? Convert the shares while they're cheap. You pay tax on the current depressed value, then capture all the recovery tax-free in the Roth.
This works in reverse too. Never convert at market peaks. You pay tax on inflated values, then watch the account drop after conversion. That's paying tax on gains you never realize.
Business owners with concentrated stock positions face unique challenges. Selling inside a traditional IRA to diversify triggers no immediate tax. Convert to Roth before selling, and the tax bill includes all the appreciation.
Better sequence: sell and diversify inside the traditional IRA first. Then convert the diversified portfolio. Same tax result, but you've eliminated the concentration risk before conversion.
Recharacterization No Longer Available
Prior to 2018, you could reverse a Roth conversion. Converted, watched the account drop, changed your mind? Recharacterize it back to traditional and erase the tax bill.
Congress eliminated this in the Tax Cuts and Jobs Act. Every conversion is now permanent. You cannot undo it. Cannot recharacterize. Cannot take it back.
This makes timing and amount critical. Convert too much and your tax bill is locked in. Account tanks after conversion? You still owe tax on the higher pre-conversion value. No do-overs.
Some strategic considerations before converting include the permanence of the decision and the inability to reverse course if circumstances change.
When Not to Convert
Several situations make a rollover IRA to Roth IRA conversion actively harmful. Current tax rate exceeds retirement rate? Don't convert. Paying 35% now to avoid 22% later destroys wealth.
Need the money within five years? Don't convert. The five-year rule on converted amounts means early access triggers penalties.
Cannot pay the tax from outside funds? Absolutely don't convert. Using IRA money to pay the tax adds a 10% penalty if you're under 59½ and permanently reduces the amount compounding tax-free.
Medicaid planning in your future? Roth conversions count as income and can disqualify you from benefits or trigger look-back penalties. Traditional IRAs receive better protection in many states.
Business owners expecting significant income increases should wait. Your bracket today might be your lowest bracket ever. Converting before a business sale or major liquidity event means paying tax at lower rates.
Converting a rollover IRA to Roth IRA can save substantial tax over decades, but only if the timing and amount align with your specific tax situation. Most business owners miss the opportunity because they never run the analysis. Taxt builds these projections into every planning engagement, modeling conversion scenarios across multiple years to find the strategy that minimizes lifetime tax while maximizing retirement wealth.