Knowledge is protection when the IRS is involved. I'm Darrin Mish, a tax attorney in Tampa with 32 years of experience representing taxpayers nationwide. Here's what I want you to understand.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your CPA probably mentioned a roth 457 option when you started that government job. Then nothing. No strategy, no planning timeline, no conversation about when it makes sense versus when it doesn't. That silence costs you tens of thousands in retirement.
Most people think retirement accounts are all the same. Traditional, Roth, whatever – just pick one and move on. That's exactly how you leave money on the table. The roth 457 option carries specific planning advantages that don't exist in traditional 457(b) plans, and the difference compounds over decades.
What Makes Roth 457 Different From Regular 457(b)
You already know the basic 457(b) setup. Pre-tax contributions lower your taxable income now. Money grows tax-deferred. You pay ordinary income tax on withdrawals. Standard retirement account mechanics.
The roth 457 flips that script entirely. You contribute after-tax dollars now, so no immediate deduction. But qualified distributions come out completely tax-free – contributions, earnings, all of it. Understanding what constitutes a 457(b) plan helps clarify how the Roth option modifies the traditional structure.
Here's what qualified means:
- You've held the account for at least five years
- You're age 59½ or older, disabled, or deceased
- The distribution follows separation from service
Meet those conditions and the IRS never touches another dollar from that account. That's not tax-deferred. That's tax-never.
The Five-Year Clock Nobody Explains
That five-year holding period starts January 1 of the year you make your first roth 457 contribution. Not the actual contribution date – the calendar year. Contribute in December 2026, your clock starts January 1, 2026.
This matters for early retirement planning. If you want tax-free distributions at 59½, you need that first contribution in the account by the time you turn 54½. Most people miss this completely.
The clock runs per plan, not per contribution. One five-year period per roth 457 plan. But if you change employers and start a new plan, you start a new clock.
2026 Contribution Limits and Catch-Up Rules
Standard contribution limits for 2026 hit $23,500. That's the same limit across 401(k), 403(b), and 457(b) plans. But roth 457 plans carry an extra planning layer most CPAs ignore.
The 457(b) special catch-up provision lets you contribute double the normal limit during the three years before normal retirement age. That's $47,000 in 2026 if your plan defines normal retirement as 65 and you're 62, 63, or 64. The 2026 457 contribution limits spell out exactly how much you can shelter.
You can't combine the special catch-up with the regular age-50 catch-up. Choose the bigger number. For most people hitting that three-year window, the special catch-up wins.
| Contribution Type | 2026 Limit | Eligibility |
|---|---|---|
| Standard | $23,500 | All participants |
| Age 50+ catch-up | $7,500 | Age 50 or older |
| Special catch-up | $47,000 | 3 years before retirement |
The 2026 High-Earner Roth Mandate
Starting January 1, 2026, if you earned more than $145,000 in the prior year, all catch-up contributions must go to Roth. Not optional. Mandatory. The catch-up contribution changes for higher earners mean you can't avoid the Roth treatment if you're over the threshold.
This hits government executives and tenured employees hard. You're used to pre-tax contributions reducing your W-2. Now your catch-up dollars face current taxation.
But here's the planning angle: if you're forced into Roth catch-ups anyway, max them out. You're already taking the tax hit. The difference between contributing $7,500 Roth and $0 is 30 years of tax-free compound growth you're leaving behind.
Strategic Timing: When Roth 457 Beats Traditional
Your marginal tax rate today versus retirement determines everything. If you're paying 24% now and expect to withdraw at 12% later, traditional contributions win. The math is simple.
Roth makes sense in three specific situations:
Early career government employees. You're making $60,000, filing single, sitting in the 22% bracket. Your retirement income will likely exceed that once Social Security, pension, and distributions combine. Pay tax at 22% now, avoid 24% or higher later.
Mid-career professionals expecting pension income. You've got 15 years until retirement and a defined benefit pension locking in $50,000 annually. That pension alone might push you into higher brackets than today. Roth distributions give you tax-free income to layer on top.
Anyone in a low-income year. Sabbatical, career transition, unpaid leave – these create temporary tax rate drops. If you're normally in the 32% bracket but taking a year at 22%, that's when you shift maximum dollars to Roth.
The conventional wisdom says contribute traditional while working, then do Roth conversions in retirement. That's fine for private sector 401(k) participants. But 457(b) plans have no early withdrawal penalty after separation from service, even before 59½. You can access that money earlier, which changes the planning timeline entirely.
Combining Traditional and Roth Contributions
Most 457(b) plans let you split contributions between traditional and Roth in the same year. This isn't all-or-nothing.
The sophisticated move: contribute traditional up to the top of your current bracket, then switch to Roth for everything above. If you're single with $100,000 in taxable income, you're in the 24% bracket. The 24% bracket tops out at $191,950 in 2026. You've got $91,950 of headroom.
Contribute traditional dollars to fill that bracket, then flip to Roth once you'd otherwise bump into 32%. You're optimizing both sides – maximizing the deduction where it's valuable, paying tax where the rate is reasonable.
Distribution Rules That Change Everything
The roth 457 distribution rules deviate from Roth IRA mechanics in one critical way: the ordering rules. Roth IRAs let you withdraw contributions first, earnings second. Clean separation.
Roth 457 plans treat every distribution as pro-rata. If your account is 60% contributions and 40% earnings, every dollar you withdraw is 60% contributions, 40% earnings. This matters if you're pulling money before the five-year mark or before age 59½.
The earnings portion of a non-qualified distribution gets taxed as ordinary income plus a 10% penalty. Not the end of the world, but not the tax-free treatment you're expecting.
After separation from service, 457(b) plans waive the 10% early withdrawal penalty entirely. That's the built-in advantage over 401(k)s and IRAs. But the income tax on earnings still applies for non-qualified roth 457 distributions.
Required Minimum Distributions After SECURE 2.0
Prior to SECURE 2.0, roth 457 accounts required minimum distributions starting at age 73. The Roth 401(k) changes under SECURE 2.0 eliminated RMDs for Roth accounts in employer plans starting in 2024, which extends to roth 457 plans.
That's a massive planning shift. You can leave money in the roth 457 indefinitely if you want. No forced withdrawals, no tax bomb in your 70s.
The alternative: roll the roth 457 into a Roth IRA after separation from service. Same no-RMD treatment, but you gain Roth IRA withdrawal flexibility and potentially better investment options. The five-year clock for the Roth IRA starts separately, though. Plan accordingly.
Common Planning Mistakes I See Repeatedly
Mistake one: Contributing to roth 457 while carrying high-interest debt. If you're paying 18% on credit cards, that's your guaranteed return. Pay the debt first. Roth contributions make zero sense when you're bleeding 18% annually.
Mistake two: Ignoring the employer match structure. Some 457(b) plans match contributions, some don't. If yours does, understand whether the match goes traditional or Roth. Employer matches always go traditional, even if your contributions go Roth. Factor that into your tax planning.
Mistake three: Failing to coordinate with other retirement accounts. You might have a 401(k) from a previous employer, an IRA, and now the 457(b). These accounts don't exist in isolation. Your withdrawal strategy needs to sequence across all of them.
The changes to retirement accounts in 2026 affect how you should coordinate between account types, especially with the new Roth catch-up requirements.
The Roth Conversion Question
Can you convert traditional 457(b) money to roth 457? It depends entirely on your plan. Some allow in-plan Roth conversions, most don't.
If your plan allows it, you're paying ordinary income tax on the converted amount in the year of conversion. That's potentially a six-figure tax bill if you're converting a large balance.
The planning strategy: convert during low-income years or spread conversions across multiple years to avoid bracket creep. Converting $30,000 per year for five years beats converting $150,000 in one year and spiking into the 35% bracket.
If your plan doesn't allow in-plan conversions, you're waiting until separation from service. Then you roll the traditional 457(b) to a traditional IRA, and convert that IRA to Roth. Extra step, same tax result.
State Tax Implications Nobody Mentions
Federal tax treatment is only half the equation. State income tax varies wildly on retirement distributions.
Nine states have no income tax at all. If you're working in California paying 9.3% state tax but retiring to Florida, every traditional 457(b) dollar you withdraw in Florida saves 9.3% compared to withdrawing it while working. Roth contributions look less attractive in that scenario.
The reverse also applies. Working in Florida, retiring to California? Roth suddenly looks much better because you're avoiding future California tax on distributions.
Seven states don't tax retirement income. Illinois, Mississippi, Pennsylvania – these states exempt distributions from 401(k)s, IRAs, and 457(b) plans. If you're retiring there, traditional contributions give you the federal deduction now plus state exemption later. Double benefit.
Building the Roth 457 Into Your Wealth Plan
The roth 457 isn't isolated retirement planning. It fits into a broader wealth accumulation system alongside tax planning, business structure, and investment strategy. Taxt’s approach integrates these pieces so they work together instead of competing.
Your business distributions affect your W-2 income, which affects your retirement account limits and Roth mandates. Your estimated tax payments affect cash flow, which affects how much you can contribute. Everything connects.
Most business owners think about retirement accounts in December when the CPA mentions it. That's too late. The planning happens in January when you're setting compensation structure for the year.
If you're running an S-corp and paying yourself W-2 wages, you control that wage level. Set it to optimize retirement contributions. If you want to max the special catch-up provision, you need W-2 wages to support those contributions. If you want to stay under the $145,000 Roth mandate threshold, structure your compensation accordingly.
Coordination With Other Tax-Advantaged Accounts
The roth 457 works alongside Health Savings Accounts, traditional IRAs, and SEP IRAs if you have self-employment income. These accounts don't share contribution limits.
You can contribute $23,500 to the roth 457, $7,000 to an IRA, $4,300 to an HSA, and potentially another $69,000 to a SEP IRA if you have consulting income. These limits stack.
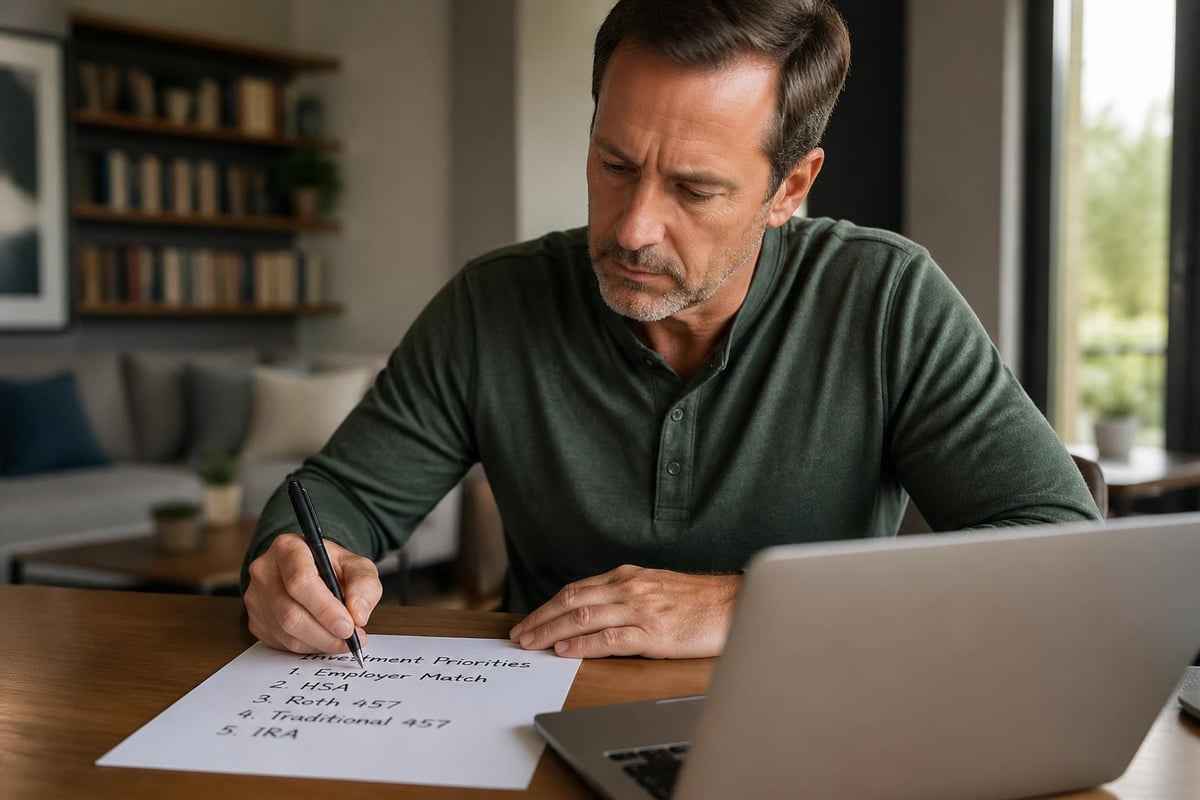
The strategic planning question: which accounts get funded first? Generally, max any employer match first, then HSA, then roth 457 or traditional based on your tax situation, then additional retirement vehicles.
But that's generic advice. Your actual sequencing depends on your specific tax bracket, expected retirement income, state tax situation, and liquidity needs. The planning guidance for catch-up contributions in 2026 gives you a framework for thinking through these decisions.
Documentation and Compliance Requirements
The roth 457 election happens through payroll. You're not making lump-sum contributions like an IRA. You set your deferral percentage and designation (traditional vs. Roth), and payroll processes it.
Change that election any time during the year. Most plans let you adjust monthly or even per paycheck. If you get a bonus and want it to go 100% Roth while your regular salary goes traditional, you can structure that.
Keep documentation of your Roth contribution amounts separately. Your Form W-2 shows total 457(b) deferrals in Box 12, but it doesn't distinguish traditional from Roth. Your payroll records do.
This matters for the five-year clock and for tracking basis. When you take distributions decades from now, you'll need proof of what went in as Roth versus traditional. Your plan recordkeeper maintains this, but keep your own records too.
What Your Plan Document Actually Says
Every 457(b) plan operates under a plan document. That document specifies whether Roth contributions are allowed, what the vesting schedule looks like, whether loans are permitted, and what distribution triggers exist.
Read it. I know that sounds basic, but most participants never look at their plan document. They assume all 457(b) plans work the same. They don't.
Some plans require you to be vested before accessing Roth contributions. Some allow hardship withdrawals, some don't. Some permit in-service distributions at 59½, some require separation from service. The plan document controls everything.
If your plan doesn't allow roth 457 contributions, ask why. Many government employers added Roth options after SECURE 2.0 made them more attractive. If yours hasn't, pressure HR to amend the plan. You're leaving tax planning flexibility on the table.
The Math on Tax-Free Versus Tax-Deferred
Let's make this concrete. You're 40 years old, contributing $10,000 annually to either traditional or roth 457 for 25 years until age 65. Your money compounds at 7% annually.
Traditional scenario: You save $2,200 in taxes each year (22% bracket), so the contribution only costs you $7,800 in actual cash. After 25 years at 7%, you've got $632,000. You withdraw it in retirement at a 12% effective rate, netting $556,000 after tax.
Roth scenario: The $10,000 contribution costs you the full $10,000 since there's no deduction. After 25 years at 7%, you've got the same $632,000. But you withdraw it completely tax-free. You keep the full $632,000.
The difference: $76,000 in your pocket. That's assuming your retirement rate is only 12%. If it's higher – say 22% because of pension income, Social Security taxation, and required minimum distributions from other accounts – the Roth advantage jumps to $138,000.
This is why the retirement tax rate assumption matters so much. Underestimate it by even 5%, and you cost yourself six figures over a career.
Why This Planning Happens in January, Not December
You can't make up retirement contributions after year-end. Once December 31 passes, that year's limit is gone. No extensions, no retroactive elections.
The planning calendar works backwards from that deadline. If you want to max your roth 457 in 2026, you need the cash flow to support $23,500 in after-tax contributions. That means planning your business distributions, estimated tax payments, and personal spending to free up that money.
Most business owners don't have $23,500 sitting around in January. They earn it across the year through business profits. Which means setting up the payroll deferrals in January to capture those earnings as they come in.
Wait until November to think about it, and you've missed 11 months of contributions. You can't catch up in one month without serious cash flow disruption.
The roth 457 creates tax-free retirement income if you plan it correctly, but most government employees and business owners treat it as an afterthought instead of a strategic wealth-building tool. The 2026 rule changes make Roth planning even more critical for high earners. Taxt builds these retirement account strategies into our comprehensive tax planning process – we map out exactly which accounts to fund, when to make Roth conversions, and how to structure your compensation to maximize every available dollar of tax-advantaged savings. If your current advisor hasn't walked you through this level of retirement account optimization, we should talk.