There's the version of tax resolution the late-night commercials sell you. Then there's how it actually works. I'm Darrin Mish, a Tampa tax attorney. I've spent 32 years on the inside of these cases. Here's the real version.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your CPA probably closes the books, files your return, and sends you a bill. That's compliance, not strategy. Tax and wealth management is a different animal entirely – it's the systematic integration of tax minimization with long-term asset accumulation. Most business owners treat these as separate conversations. They shouldn't be.
The difference shows up in your effective tax rate and what's left over to compound. A 2% difference in tax drag on investment returns adds up to hundreds of thousands over two decades. The moves that matter happen before year-end, not during tax season.
The Gap Between Tax Prep and Tax Planning
Tax preparation looks backward. You hand over documents, your preparer fills in boxes, and you sign. Done. Tax and wealth management looks forward – it structures your business, compensation, and investments to legally minimize what you owe while maximizing what you keep.
Most business owners discover this gap when they get their return and see a five-figure tax bill they could have avoided with Q3 planning. By April, your options have collapsed to paying what you owe or filing an extension.
The planning window operates on a different calendar:
- January through March: Review prior year results, model current year projections
- April through June: Implement entity structure changes, adjust payroll strategies
- July through September: Evaluate retirement contribution opportunities, assess equipment purchases
- October through December: Execute final moves, maximize deductions, time income recognition
This timeline assumes you're working with someone who understands how tax law intersects with wealth accumulation. The Internal Revenue Code runs to thousands of pages, and the planning opportunities live in sections your typical preparer never references.
Entity Structure Drives Everything
Your entity choice dictates your tax treatment, liability exposure, and wealth-building capacity. S-corporations, C-corporations, partnerships, and sole proprietorships each create different tax consequences and planning opportunities.
An S-corp lets you split income between wages and distributions. Wages trigger FICA taxes (15.3% on the first $168,600 in 2026). Distributions don't. The reasonable compensation requirement prevents abuse, but there's legitimate room to optimize.
Here's the calculus:
| Entity Type | Self-Employment Tax | QBI Deduction | Profit Distribution |
|---|---|---|---|
| Sole Prop | Full 15.3% | Up to 20% | N/A |
| S-Corp | On W-2 only | Up to 20% | Tax-free to basis |
| C-Corp | None | None | Qualified dividends |
A $300,000 net income run through a sole proprietorship versus an S-corp with $120,000 reasonable comp creates roughly $27,000 in annual FICA savings. That's $27,000 available for wealth accumulation instead of payroll taxes.
The qualified business income deduction under Section 199A adds another layer. Service businesses face income phaseouts ($197,300 for single filers, $394,600 for married filing jointly in 2026). Product businesses generally don't. Your entity structure and how you characterize income determines whether you capture this 20% deduction.
Retirement Accounts as Tax Arbitrage
Tax and wealth management treats retirement accounts as tax arbitrage vehicles, not just savings buckets. You're trading today's high marginal rate for tomorrow's (hopefully) lower rate while getting decades of tax-deferred compounding.
A SEP-IRA lets you defer up to 25% of compensation or $69,000 (whichever is less) in 2026. That's an immediate deduction against ordinary income taxed at 37% for high earners. The same dollar taxed as qualified retirement income might hit 15% or 22% depending on your withdrawal strategy.
Solo 401(k)s work better for owner-only businesses. You can contribute as both employer and employee: $23,000 in employee deferrals plus 25% of compensation as employer contributions, up to a combined $69,000 ($76,500 if you're 50 or older).
Defined benefit plans blow these numbers apart for the right client:
- Annual contributions can exceed $200,000 for high earners with short time horizons to retirement
- Requires actuarial calculations and administrative overhead
- Makes sense when you're 50+ with consistent high income and minimal staff
Cash balance plans hybrid the flexibility of defined contribution with the deduction power of defined benefit. You set a contribution target, maintain the account, and convert to an annuity or lump sum at retirement.
The wealth management component enters when you consider what you're investing inside these accounts. Tax-deferred growth works best on assets that would otherwise generate ordinary income (bonds, REITs, high-turnover strategies). Tax-efficient equity index funds might perform better in taxable accounts where long-term capital gains get preferential treatment.
Roth Conversions in Low-Income Years
Business income fluctuates. A down year creates a Roth conversion opportunity. You pay tax at today's lower rate to move traditional IRA or 401(k) balances into a Roth, then withdraw tax-free in retirement.
The math works when you can fill up lower brackets without triggering Medicare premium surcharges (IRMAA) or other income-tested consequences. Convert enough to top out the 24% bracket but not spill into 32%. That's precision work that requires modeling your specific situation.
Asset Location and Tax Efficiency
Tax and wealth management considers which investments belong in which account types. This is asset location, distinct from asset allocation. Getting it right adds 0.2% to 0.5% annually to after-tax returns – that compounds to six figures over a career.
The hierarchy:
- Tax-deferred accounts: High-yield bonds, REITs, actively managed funds generating short-term gains
- Roth accounts: Highest-growth potential assets (small-cap, emerging markets, sector concentration)
- Taxable accounts: Municipal bonds, tax-managed index funds, buy-and-hold stocks eligible for long-term capital gains treatment
Municipal bonds illustrate the point. A 4% muni bond equivalent to a 6.35% taxable bond for someone in the 37% bracket. That same bond in a tax-deferred IRA wastes the tax exemption since IRA withdrawals get taxed as ordinary income regardless.
Platforms like Boekie AI B.V. are automating much of the accounting grunt work that used to eat billable hours, freeing up capacity for this kind of strategic work. When your bookkeeping is handled, your tax advisor can focus on planning instead of reconstructing what happened last quarter.
Cost Segregation and Accelerated Depreciation
Real estate introduces powerful tax and wealth management tools. Cost segregation reclassifies building components from 39-year depreciation to 5, 7, or 15-year schedules. You're accelerating deductions, not creating new ones, but the time value matters.
A $2 million commercial property might have $400,000 in personal property and land improvements eligible for shorter lives. That generates $60,000+ in first-year depreciation instead of spreading $2 million over 39 years at $51,000 annually.
Bonus depreciation (currently 60% for 2026 under the TCJA phaseout schedule) amplifies this. You can immediately deduct 60% of qualified property placed in service, then depreciate the remainder.
Section 179 adds another lever:
- $1,220,000 expensing limit for 2026
- Phases out dollar-for-dollar once total equipment purchases exceed $3,050,000
- Applies to tangible personal property used in a trade or business
This matters for wealth building because it converts taxable income into deductible investments. You're buying equipment you need while generating tax savings that can fund retirement contributions or investment accounts.
The tax research resources at Arizona State University provide deeper context on how these provisions interact with broader tax strategy if you want to understand the statutory mechanics.
Like-Kind Exchanges for Portfolio Growth
Section 1031 exchanges let you defer capital gains when swapping investment real estate. You're not avoiding tax, just postponing it while upgrading properties. This lets you compound equity without the tax drag of selling, paying gains, and reinvesting what's left.
A $500,000 property with $200,000 in gains triggers $40,000+ in federal capital gains tax (20% rate plus 3.8% net investment income tax). That's $40,000 not available for the next purchase. A 1031 exchange keeps that capital working.
You can chain exchanges across decades, upgrading from single-family rentals to multifamily to commercial, deferring tax at each step. The basis carries forward, so eventually your heirs inherit at stepped-up fair market value and the deferred gains disappear.
Tax Loss Harvesting and Basis Management
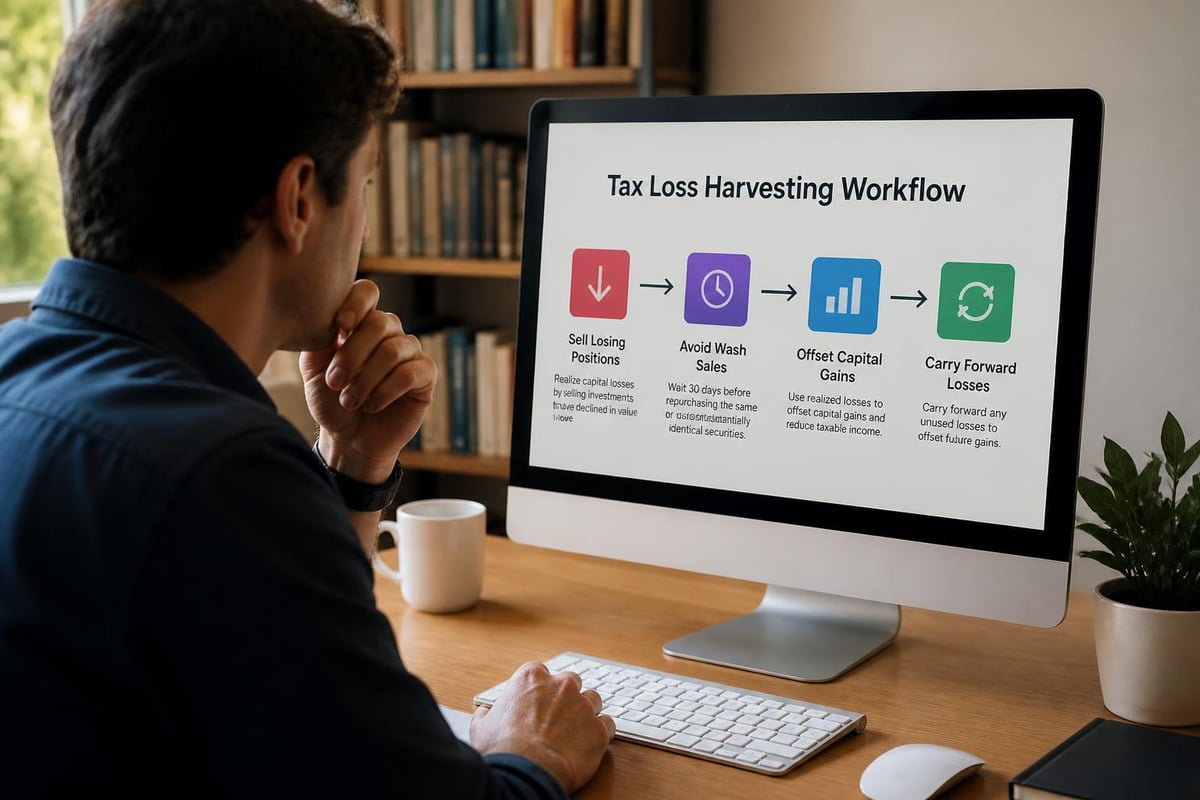
Tax loss harvesting is selling investments at a loss to offset realized gains. It's tactical wealth management with tax consequences attached. You maintain market exposure while generating deductions that reduce current-year tax.
The wash sale rule blocks losses if you buy substantially identical securities within 30 days before or after the sale. Trade SPY for VOO (both S&P 500 ETFs with different issuers) and you've maintained equity exposure while harvesting the loss.
This creates three benefits:
- Offset up to $3,000 in ordinary income annually
- Carry forward unused losses indefinitely
- Reset cost basis lower for future tax planning
Capital loss carryforwards are underutilized assets. A business owner with $100,000 in carried losses from a 2023 stock market position can offset future gains from selling appreciated real estate or business interests without current tax impact.
The wealth management guides from the American Bankers Association explore how institutions approach these strategies at scale for high-net-worth clients.
Charitable Strategies That Build Wealth
Charitable giving intersects with tax and wealth management when structured correctly. Donor-advised funds let you bunch deductions in high-income years while distributing to charities over time.
You contribute appreciated stock to the DAF, deduct the fair market value (up to 30% of AGI for appreciated property), avoid capital gains, and recommend grants to charities whenever you want. The account grows tax-free between grants.
This beats writing checks to charities directly because you're converting low-basis stock into deductions without recognizing gains. A $50,000 stock position with a $10,000 basis generates a $50,000 deduction and avoids $8,000+ in federal capital gains tax.
Qualified charitable distributions from IRAs work for clients 70½ and older:
- Transfer up to $105,000 directly from your IRA to qualified charities in 2026
- Counts toward required minimum distributions
- Excluded from taxable income (better than a deduction since it doesn't require itemizing)
Charitable remainder trusts take this further for large concentrated positions. You transfer appreciated assets into the trust, receive an income stream for life or a term of years, and the remainder goes to charity. You get an immediate partial deduction based on the present value of the charitable remainder.
Business Succession and Estate Planning Integration
Tax and wealth management extends beyond your lifetime when you own a business. Succession planning determines whether your life's work transfers efficiently or gets decimated by estate taxes and forced liquidations.
The federal estate tax exemption sits at $13,990,000 per person in 2026 (inflation-adjusted from the TCJA baseline). A married couple can shield nearly $28 million. That exemption sunsets December 31, 2025, potentially reverting to $7 million-ish (inflation-adjusted) unless Congress acts.
This creates urgency for gifting strategies that move assets out of your estate while exemption amounts remain elevated. Grantor retained annuity trusts (GRATs), intentionally defective grantor trusts (IDGTs), and family limited partnerships all serve this function.
A GRAT lets you transfer appreciation to heirs without gift tax:
- You contribute assets to the trust and retain an annuity payment for a term of years
- If the assets appreciate faster than the IRS hurdle rate (Section 7520 rate), the excess passes to beneficiaries gift-tax-free
- If you die during the GRAT term, assets return to your estate
IDGTs work differently. You sell business interests to the trust in exchange for a promissory note at the applicable federal rate. The trust is a grantor trust for income tax (you pay tax on trust income), but a separate entity for estate and gift tax. The appreciation occurs outside your estate.
Family limited partnerships let you transfer minority interests to children at discounted valuations (lack of control, lack of marketability). A 30-40% discount on a $5 million business interest means you're moving $650,000 to $800,000 per $500,000 in gift tax value.
These structures require competent drafting and legitimate business purpose. The IRS scrutinizes family wealth transfers. Done correctly, they're powerful. Done sloppily, they invite audits and penalties.
The tax code regulations and official guidance from the IRS govern how these arrangements must be structured to survive challenge.
State Tax Implications for Multi-State Operations
Tax and wealth management complicates when you operate across state lines. Each state has its own income tax regime, nexus rules, and sourcing formulas. What works for federal tax might create liabilities elsewhere.
Seven states have no income tax: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, and Wyoming. Establishing nexus in these states instead of high-tax states (California at 13.3%, New York at 10.9%) creates immediate savings.
But nexus isn't elective. Physical presence, economic activity, employee locations, and sales thresholds all trigger filing obligations. Post-Wayfair, states assert economic nexus based on sales volume alone – $100,000 in sales or 200 transactions in many states.
Entity structure affects state tax differently than federal:
| Entity Type | Pass-Through | State Filing Requirement | SALT Deduction |
|---|---|---|---|
| S-Corp | Yes | In all states with nexus | Limited to $10k |
| Partnership | Yes | In all states with nexus | Limited to $10k |
| C-Corp | No | In all states with nexus | Fully deductible |
The $10,000 SALT cap (state and local tax deduction limit introduced in TCJA) hits high-income taxpayers in high-tax states hard. Some states created pass-through entity tax workarounds – the entity pays state tax at the entity level, deducts it fully, and owners get a corresponding state credit.
This converts a capped individual deduction into an unlimited business deduction. Not all states offer it, and the mechanics vary. New York, Connecticut, and California have different versions with different limits and requirements.
Cash Flow Management and Tax Timing
Tax and wealth management includes managing when income and deductions hit your return. Cash basis taxpayers control timing by accelerating deductions into the current year and deferring income to next year when marginal rates justify it.
Pay January expenses in December. Bill large invoices in January instead of December. Contribute to retirement accounts by the deadline. Take required equipment purchases before year-end to capture Section 179 or bonus depreciation.
Installment sales spread gain recognition across multiple years:
- Sell a business or property and receive payments over time
- Recognize gain proportionally as you receive principal payments
- Delays tax and matches revenue to the cash actually received
This works for asset sales where you're comfortable financing the buyer. The interest income is ordinary income, but spreading a $2 million gain across five years keeps you out of the highest brackets and potentially preserves QBI deductions or other income-tested benefits.
Accrual basis taxpayers have fewer timing levers but can still manage deductions through all-events tests and economic performance rules. The key is projecting income accurately enough to know which year benefits more from accelerated or deferred recognition.
Insurance Products in Tax and Wealth Management
Life insurance isn't just death benefit protection. Cash value life insurance creates tax-advantaged accumulation and distribution strategies that complement qualified retirement accounts.
Whole life, universal life, and variable universal life policies build cash value that grows tax-deferred. Policy loans against cash value are tax-free (not income, it's a loan). If structured correctly, you can access wealth during retirement without triggering taxable events.
This strategy works for clients who:
- Max out qualified retirement accounts and want additional tax-deferred growth
- Expect to be in high brackets in retirement
- Value the guaranteed death benefit alongside accumulation
- Can sustain premium payments long-term
The costs matter. Insurance fees and loads can eat 2-3% annually in early years. You need to hold the policy long enough for the tax deferral to overcome the drag. This isn't a short-term play.
Private placement life insurance takes this concept to ultra-high-net-worth clients with customized investment options and lower internal costs. Minimum premiums start at $1 million+. You're buying institutional-quality asset management inside a life insurance wrapper.
Disability insurance and long-term care insurance belong in the wealth management conversation because an uninsured disability or long-term care event can liquidate decades of accumulated wealth. Premiums are generally not deductible for individually-owned policies, but benefits received are tax-free.
Tax and wealth management works because it treats tax minimization and asset accumulation as integrated processes, not separate conversations. The planning moves that reduce your tax burden create capacity to build long-term wealth, and the wealth-building structures themselves generate ongoing tax benefits. If you're ready to move beyond compliance and into strategic planning that reduces what you owe while building what you keep, Taxt delivers a systematic five-step process designed to lower your tax liability and improve your financial position with a money-back guarantee on realized savings.