I'm Darrin Mish. For 32 years I've practiced federal tax litigation — routine audits, Tax Court cases, and everything in between. If you're facing an IRS issue, here's what you need to know first.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your CPA files your return every April. They reconcile last year's numbers. But that's compliance, not strategy. Real tax planning advice happens before you earn the dollar, not after you've already spent it. Most business owners operate in this reactive cycle, hoping deductions materialize while actual planning opportunities slip past unmarked.
The gap between what you pay and what you should pay isn't about aggressive positions or creative interpretations. It's about timing, structure, and decisions made twelve months before your accountant sees a single receipt. The business owners who consistently pay less aren't cheating. They're planning.
The April Problem Most Business Owners Face
You hand your accountant a shoebox in March. They tell you what you owe in April. Then you scramble to find deductions that don't exist anymore because the tax year closed three months ago.
This isn't tax planning. It's tax reporting with a side of hope.
The fundamental flaw in this approach is temporal. Tax law rewards proactive decisions, not retroactive wishes. When your accountant reviews 2025 in March 2026, every opportunity to reduce that liability vanished on December 31st. Retirement contributions, equipment purchases, entity structure changes – these moves require time and timing.
Why December 31st Is Actually Your Deadline
Consider the qualified business income deduction under IRC Section 199A. Your eligibility depends on your taxable income, your business structure, and whether you're in a specified service trade or business. You can't restructure your LLC on April 10th and apply it to last year's income. The entity choice needed to be made and operational before the tax year ended.
The same timing constraint applies to:
- Retirement plan contributions (establishment deadlines vary by plan type)
- Cost segregation studies on property purchases
- Like-kind exchanges under Section 1031
- Bonus depreciation elections under Section 168(k)
Each strategy carries specific deadlines, qualification requirements, and implementation windows. Miss the window, lose the deduction. This is why proactive tax planning is essential for business owners seeking to maximize legitimate tax advantages.
The Five Tax Planning Conversations Your CPA Isn't Starting
Good accountants are meticulous. Great ones are proactive. But even great CPAs operate under time constraints that limit how deeply they can dig into planning versus preparation. These five conversations rarely happen in typical CPA relationships, yet they represent the highest-value planning opportunities for business owners.
1. Entity Structure Optimization
You formed your LLC five years ago. Revenue has tripled. Your tax situation hasn't been reevaluated since formation.
S-corporations can deliver significant self-employment tax savings once your profit exceeds roughly $60,000 to $80,000 annually. The specific threshold depends on your industry, reasonable compensation requirements, and state tax considerations. But many business owners continue paying 15.3% self-employment tax on every dollar of profit because nobody suggested reviewing entity structure.
C-corporation treatment might make sense now if you're reinvesting most profits back into growth. The flat 21% corporate rate under IRC Section 11 can beat individual rates for retained earnings. Again, timing matters: you can't retroactively elect corporate status.
2. Retirement Plan Design
Most business owners know about SEP IRAs and solo 401(k)s. Fewer know about cash balance plans, which can enable six-figure annual contributions for high-income owners in their 50s. Even fewer have run the numbers to determine which plan structure optimizes the balance between tax deduction, contribution flexibility, and administrative cost.
| Plan Type | Max Contribution (2026) | Administrative Complexity | Best For |
|---|---|---|---|
| SEP IRA | $69,000 | Low | Simple, variable income |
| Solo 401(k) | $69,000 + $7,500 catchup | Medium | Consistent high income |
| Cash Balance | $200,000+ | High | Ages 50+, stable business |
| Defined Benefit | $275,000+ | Very High | Pre-retirement, max savings |
The contribution limits shown reflect 2026 figures and assume sufficient compensation to support the maximum. These aren't just retirement vehicles – they're current-year tax deductions that double as wealth transfer mechanisms when structured properly.
3. Equipment and Property Acquisition Timing
Section 179 expensing and bonus depreciation create immediate deductions for qualifying property. But the strategy isn't "buy stuff in December to lower taxes." It's "accelerate planned purchases to the tax year where deductions provide maximum value."
A $100,000 equipment purchase in December 2026 could generate:
- $100,000 Section 179 deduction if you have sufficient income
- Or 60% bonus depreciation ($60,000 first year) under current law
- Or MACRS depreciation spread over the asset's recovery period
The optimal choice depends on your current year income, expected future income, and whether you're phasing out of deductions due to income limitations. This requires modeling, not guessing. It also requires purchasing and placing the asset in service before December 31st, which means planning in October, not March.
4. Income and Deduction Timing Strategies
Cash-basis businesses control timing of some income and expenses. Accrual-basis businesses face different rules but still have planning levers.
High-income year ahead? Consider:
- Prepaying state and local taxes (subject to $10,000 SALT cap for individuals)
- Accelerating planned equipment purchases
- Maximizing retirement contributions
- Bunching charitable contributions (donor-advised funds enable multi-year strategies)
- Harvesting investment losses to offset gains
Low-income year expected? Reverse the strategy. Defer deductions, accelerate income, convert traditional retirement funds to Roth accounts while you're in lower brackets.
None of this works in April when you're looking backward. As high-net-worth individuals recognize, tax planning must be forward-looking and continuous.
5. Family Employment and Income Shifting
Employing your children isn't just about teaching work ethic. It's a tax arbitrage opportunity when structured properly.
A child employed in your sole proprietorship or partnership (if both partners are parents) can earn up to the standard deduction ($14,600 in 2026) tax-free. That's income shifted from your potentially 37% bracket to their 0% bracket. The business gets a deduction. The child gets earned income that can fund a Roth IRA.
Requirements are strict: genuine work, reasonable compensation, proper documentation. But the strategy is explicit in tax law, not a loophole.
The Research Gap Between What You Know and What Exists
Tax planning advice isn't a static checklist. It's an evolving landscape of statutes, regulations, revenue rulings, and case law. The IRS guidance page updates weekly with notices, announcements, and proposed regulations that affect planning strategies.
Most business owners, and frankly many accountants, don't track these changes in real time. That's understandable – you're running a business, not a tax research department. But the gap between current tax law and what your planning reflects can cost tens of thousands annually.
Primary sources matter. The Internal Revenue Code is the law. Treasury Regulations interpret it. Revenue rulings and private letter rulings show how the IRS applies it. Court cases reveal where taxpayers have successfully challenged IRS positions. Secondary sources like treatises and planning guides synthesize this material into actionable strategies, but they're only as current as their last update.
Professional tax research databases update daily. Tax research platforms provide access to primary sources, annotations, and analysis that translate complex law into planning opportunities. Your CPA likely subscribes to these services, but they're researching hundreds of clients' questions, not just yours.
This is where specialized tax planning advice enters. It's not about replacing your accountant – it's about adding a strategic layer focused specifically on minimizing your tax liability through proactive planning rather than reactive compliance.
The Entity Structure Decision Tree
Your business entity isn't just a legal formality. It's your first and most fundamental tax planning decision. Yet most business owners chose their structure based on formation cost or what their neighbor's LLC looked like, not on tax optimization.
Sole Proprietorship to Multi-Member LLC
A sole proprietorship reports on Schedule C. All net profit faces both income tax and 15.3% self-employment tax. Simple to operate, expensive on taxes once profit exceeds $50,000.
Converting to an S-corporation creates a salary-dividend split. You pay yourself reasonable compensation (subject to payroll taxes), then take remaining profit as distributions (not subject to self-employment tax). The savings start the moment your profit exceeds reasonable compensation by $30,000 or more.
But S-corporation status requires:
- Only one class of stock
- U.S. citizen or resident shareholders
- No more than 100 shareholders
- Reasonable compensation documentation
- Payroll processing and quarterly filings
The administrative burden increases. The tax savings must justify that burden. This calculation changes as your business grows.
When C-Corporation Status Makes Sense
C-corporations face double taxation: corporate income tax, then dividend tax when distributed. This sounds terrible until your situation shifts:
- You're reinvesting 80% of profits in growth (distributions aren't imminent)
- You want to offer equity incentives to employees (stock options work better in C-corps)
- You're targeting acquisition or institutional investment (preferred stock structures require C-corp)
- You're in a high-margin service business that can justify retained earnings
The 21% flat corporate rate under IRC Section 11 beats individual rates above roughly $190,000 for single filers or $380,000 for joint filers (2026 brackets). If you're not distributing that income immediately, the corporate structure defers the second layer of tax while providing benefits S-corporations can't match.
| Consideration | Sole Prop | S-Corp | C-Corp |
|---|---|---|---|
| Self-employment tax on all profit | Yes | No (only salary) | No |
| Double taxation | No | No | Yes (if distributed) |
| Equity structure flexibility | N/A | Limited | Full |
| Administrative complexity | Minimal | Moderate | High |
| Optimal for | <$60K profit | $60K-$500K profit | >$500K retained earnings |
These thresholds are generalizations. Your specific situation – state taxes, industry, growth trajectory, exit strategy – changes the math. That's why cookie-cutter advice fails and customized analysis matters.
The Quarterly Planning Rhythm That Prevents Surprises
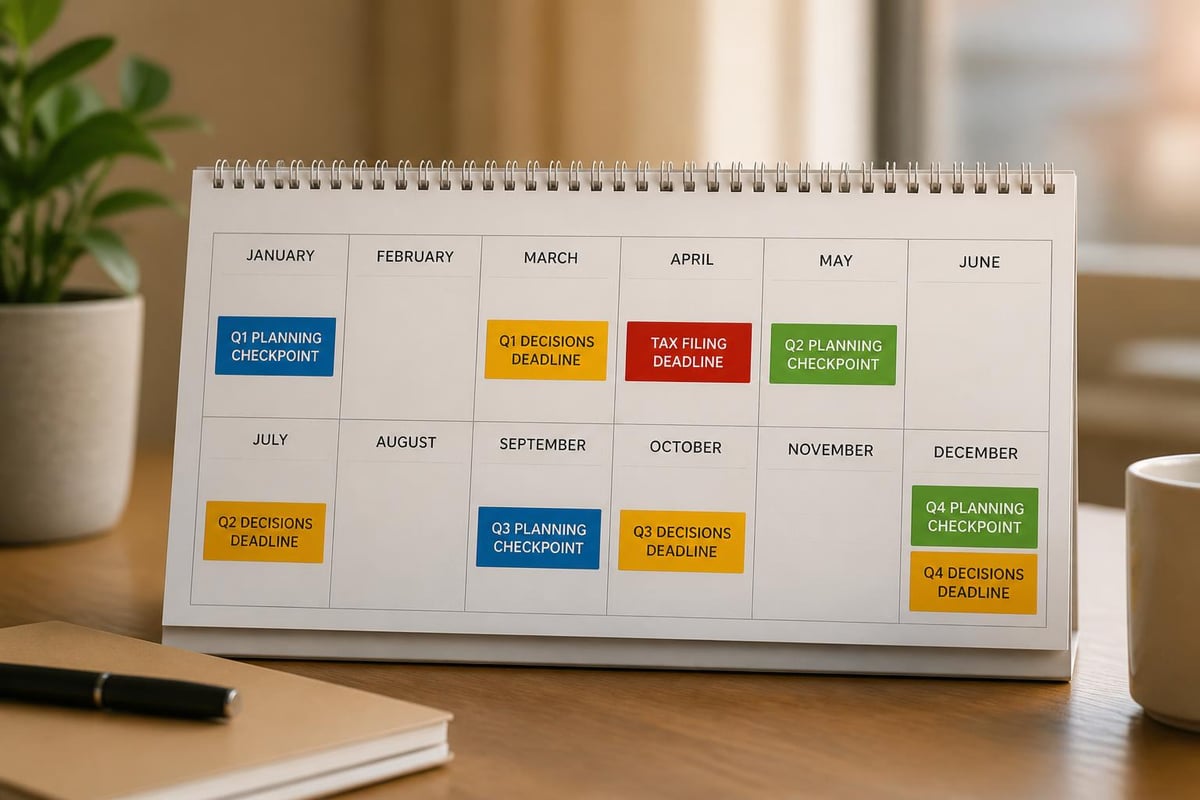
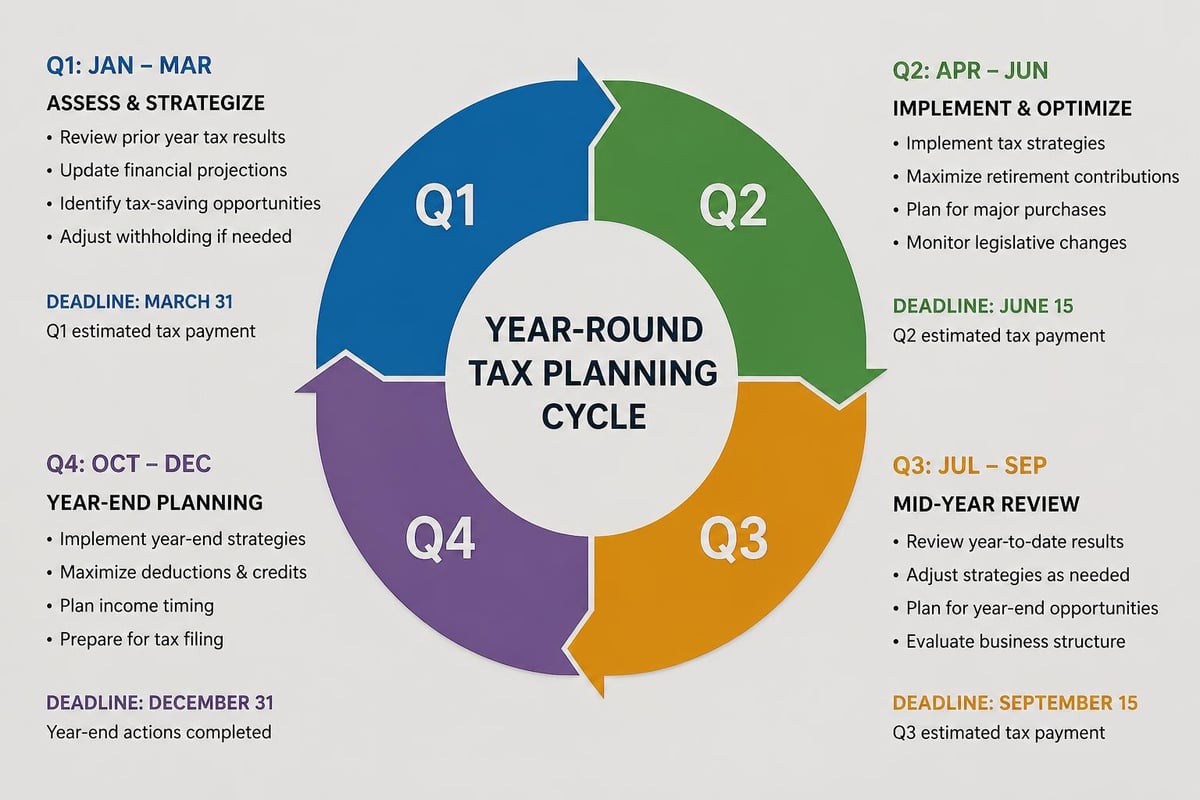
Tax planning advice shouldn't arrive once annually in a March phone call. It should operate on a quarterly rhythm that aligns planning moves with business realities and tax deadlines.
Q1 (January-March): Review prior year results, finalize retirement contributions for prior year if extended, project current year income, and establish quarterly estimated payment baseline.
Q2 (April-June): Assess first quarter actuals against projections, adjust estimated payments if income tracking differently than expected, and evaluate mid-year strategy adjustments.
Q3 (July-September): Review first half results, update annual projections, and identify planning opportunities that require Q4 implementation. This is your critical planning window.
Q4 (October-December): Execute planned strategies: equipment purchases, retirement contributions, entity structure changes for following year, income/expense timing, and year-end tax moves.
This rhythm creates four checkpoints instead of one. It catches problems while you can still fix them and identifies opportunities while you can still execute them. It transforms tax planning from an annual event into an operational discipline.
Business owners operating digital product ventures, like those building on CreateSell, benefit particularly from quarterly planning because product launches and revenue can vary dramatically month to month, making annual projections unreliable. Regular check-ins allow strategy to flex with reality.
The Documentation Practice That Saves Deductions
The IRS doesn't deny deductions because they're illegitimate. It denies them because you can't prove they're legitimate. Documentation isn't about creating evidence for deductions you shouldn't take. It's about preserving evidence for deductions you absolutely should take but might lose to poor recordkeeping.
What Actually Needs Documentation
Business use percentage of your vehicle requires a mileage log. "I drove about 80% business miles" doesn't survive audit. A contemporaneous log showing date, destination, business purpose, and miles driven does.
Home office deductions require exclusive and regular use of a specific space. Photos showing a dedicated office help. A space that's also the guest bedroom doesn't qualify, regardless of how often you work there.
Travel expenses need both proof of payment and business purpose. The credit card statement proves you spent $300 at a hotel. Your calendar showing the client meeting the next morning proves business purpose. One without the other leaves you exposed.
The Receipt Isn't Enough
You bought a $5,000 laptop. You have the receipt. Is it deductible?
- If it's used 100% for business: yes
- If it's used 60% business, 40% personal: 60% deductible
- If you can't prove the percentage: potentially zero deductible
The receipt proves purchase. It doesn't prove business use. Your documentation system needs to capture both.
Modern businesses generating content for platforms like RankPill or creating video ads through AdsRaw accumulate substantial equipment and software expenses. These are legitimate business deductions when properly documented and substantiated. They're wasted opportunities when receipts sit in an unsorted folder with no business purpose notation.
The State Tax Layer Your Federal Planning Might Ignore
Federal tax planning advice dominates most conversations. But you don't just pay federal tax. You also pay state income tax, and state strategies don't always align with federal strategies.
State Conformity Issues
Some states conform to federal tax law automatically. Others pick and choose provisions. Still others operate under entirely separate structures.
Section 199A qualified business income deduction? It's a federal deduction. Many states don't conform, meaning you calculate QBI for federal purposes but add it back for state purposes. Your effective tax rate might not drop as much as federal-only analysis suggests.
Bonus depreciation? Same issue. Federal law allows 60% first-year depreciation on qualifying property in 2026. But if your state doesn't conform, you're depreciating that asset over its normal recovery period for state purposes while expensing it federally. This creates a timing difference you'll track for years.
The SALT Deduction Cap Strategy
The $10,000 state and local tax deduction cap (IRC Section 164(b)(6)) hits high-income taxpayers in high-tax states hard. But business owners have a workaround many employees don't: pass-through entity tax elections.
More than 30 states now allow pass-through entities (S-corps, partnerships, LLCs) to pay state income tax at the entity level. This converts non-deductible personal SALT into a fully deductible business expense at the federal level. The math works because federal law treats state taxes paid by the business as ordinary business expenses, not subject to the SALT cap.
Your business pays 5% Massachusetts tax on $500,000 of income ($25,000 tax). Normally, only $10,000 would be deductible on your federal return due to SALT cap. With the PTET election, all $25,000 becomes a business deduction, reducing federal taxable income by $25,000 and saving you roughly $9,250 in federal tax (assuming 37% bracket).
This strategy requires state-specific analysis and proper election timing. It's the kind of planning move that doesn't emerge from general tax advice but does emerge from customized analysis of your specific situation.
The Retirement Account as Tax Planning Tool
You probably think of retirement accounts as savings vehicles. They are. But they're also powerful tax planning tools that shift income across time and across tax brackets.
Traditional vs. Roth: The Bracket Arbitrage
Traditional contributions reduce current-year taxable income. Roth contributions don't. That seems straightforward until you model it across decades.
High-income business owner in the 37% bracket contributes $69,000 to a traditional 401(k). Current-year tax savings: $25,530. That money compounds tax-deferred until withdrawal, when it's taxed at ordinary income rates.
Same business owner contributes $69,000 to a Roth 401(k). No current deduction. No current savings. But decades of growth and all future withdrawals are tax-free.
Which is better? It depends entirely on your current bracket versus your expected retirement bracket. If you're in the 37% bracket now and expect to be in the 24% bracket in retirement, traditional wins (save 37% now, pay 24% later). If you're in the 24% bracket now and expect to be in the 32% bracket in retirement (possibly due to RMDs from large traditional accounts), Roth wins.
Most business owners don't project retirement tax brackets. They should. Required minimum distributions from traditional accounts can push retirees into higher brackets than they experienced during working years, especially when combined with Social Security income, rental income, and investment income.
The Backdoor Roth Strategy
High-income taxpayers can't contribute directly to Roth IRAs. Income limits phase out eligibility at $153,000 for single filers and $228,000 for joint filers in 2026.
But there's no income limit on converting traditional IRA funds to Roth. The strategy:
- Contribute $7,000 to a non-deductible traditional IRA
- Immediately convert to Roth IRA
- Pay tax only on earnings between contribution and conversion (minimal if immediate)
- Result: $7,000 in Roth IRA despite being over income limits
This works cleanly if you have no other traditional IRA balances. If you do, the pro-rata rule under IRC Section 408(d)(2) applies, potentially triggering tax on a portion of the conversion. Again, strategy requires customization to your specific situation.
The Audit Defense Your Planning Should Build In
Aggressive tax planning and defensible tax planning aren't opposites. The most effective strategies are both aggressive in minimizing tax and conservative in legal foundation.
Every planning decision should pass a simple test: Can I defend this position if questioned? Not with arguments or interpretations, but with documentation, statute citations, and clear business purpose.
The Business Purpose Doctrine
Courts consistently strike down transactions that lack economic substance beyond tax benefits. Form a subsidiary in Delaware to license intellectual property back to your main business, claim deduction for royalty payments, but the subsidiary serves no purpose except creating a deduction? That's getting challenged and likely disallowed.
Legitimate business purposes create defensible positions. You formed the Delaware entity to hold IP because you're planning to sell that division separately, it limits liability exposure, and it facilitates licensing to third parties? Much stronger position.
Documentation of business purpose at the time of decision protects you later. Board meeting minutes explaining strategic rationale, emails discussing business considerations, and contemporaneous legal advice create a paper trail that demonstrates legitimate planning, not tax gamesmanship.
The Reasonable Compensation Challenge
S-corporation owners face ongoing scrutiny on reasonable compensation. Pay yourself too little salary (to minimize payroll tax), and the IRS will reclassify distributions as wages, adding tax, penalties, and interest.
What's reasonable? It's a facts-and-circumstances test considering:
- Your duties and responsibilities
- Time and effort devoted to the business
- Compensation paid to comparable positions in comparable businesses
- Your experience and qualifications
- The business's size and complexity
Document these factors. Use compensation surveys. Get professional valuation if your situation is complex. The goal isn't to minimize compensation to the absolute lowest defensible number – it's to establish reasonable compensation that balances tax savings with audit risk.
Strategic tax planning advice turns on timing, documentation, and personalized analysis of your specific situation – not generic tips pulled from last year's playbook. The business owners paying the least tax aren't finding loopholes; they're making informed decisions twelve months before those decisions hit a tax return. If you're ready to shift from reactive compliance to proactive strategy, Taxt delivers the five-step planning process that reduces tax anxiety, lowers liabilities, and builds wealth – with a money-back guarantee if we don't find meaningful savings in your situation.