Knowledge is protection when the IRS is involved. I'm Darrin Mish, a tax attorney in Tampa with 32 years of experience representing taxpayers nationwide. Here's what I want you to understand.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Most business owners think they're doing tax planning and tax management when their CPA prepares their return in March. They're not. They're doing tax reporting. The money was already spent, the income already recognized, the deductions already missed.
Real tax planning happens before the transaction. Real tax management means tracking what matters throughout the year.
The Difference Between Planning and Management
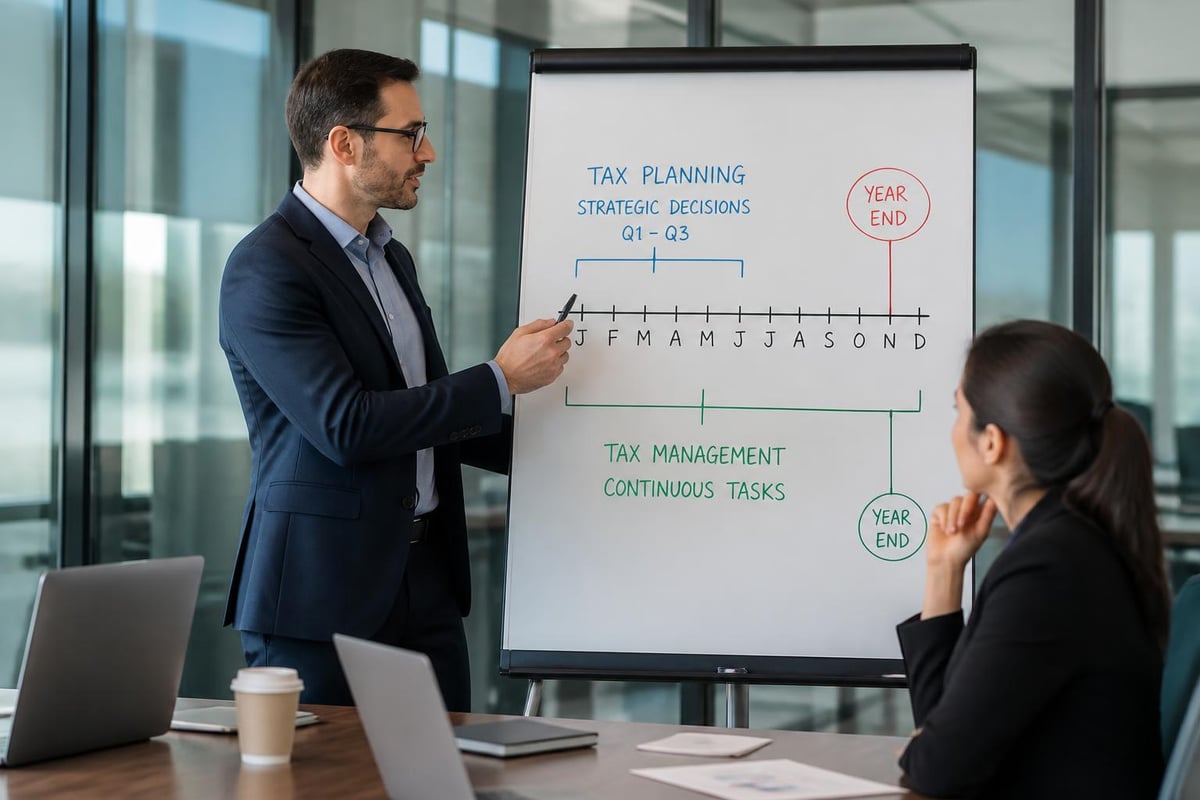
Tax planning is strategic. You structure deals, time income, choose entity types, design retirement contributions. All before December 31.
Tax management is operational. You track receipts, categorize expenses, file quarterly estimates, maintain books. The daily mechanics.
You need both. But most business owners only get one, and it's usually the wrong one.
Why Your CPA Probably Isn't Planning
Compliance firms prepare returns. They enter data, apply current law, minimize audit risk. Solid work, necessary work.
But they're not looking at your business model and asking whether an S-corp election saves $15,000 annually. They're not modeling whether bunching deductions into alternate years cuts your effective rate. They're not comparing defined benefit plans against solo 401(k) contributions.
The incentive structure doesn't reward it. You pay for the return. Planning takes time, requires projections, demands difficult conversations about what you actually want to accomplish.
So it doesn't happen.
The Five Components of Effective Tax Planning
Entity Structure Decisions
Your choice between sole proprietorship, LLC, S-corp, or C-corp determines your self-employment tax exposure. The difference isn't trivial.
A sole proprietor earning $200,000 pays self-employment tax on the full amount. An S-corp owner taking $100,000 salary and $100,000 distribution pays it only on the salary. That's roughly $15,300 in annual savings.
But the structure needs to fit your facts:
- Service businesses with one owner often benefit from S-corps
- Real estate holding companies usually prefer LLCs taxed as partnerships
- Businesses raising outside capital might need C-corps
- International operations complicate everything
The Internal Revenue Code provisions governing entity taxation run to thousands of pages. Your accountant should be reading them before you sign formation documents.
Retirement Plan Design
Most business owners think 401(k) means they're maxing out retirement savings. They're leaving six figures on the table.
In 2026, a standard 401(k) allows $23,500 in deferrals if you're under 50. Add profit sharing, you might hit $70,000 total.
A defined benefit plan can shelter $200,000 or more annually if you're over 50 with steady income. Cash balance plans split the difference.
| Plan Type | 2026 Max Contribution | Best For |
|---|---|---|
| Solo 401(k) | $70,000 | Single owner, no employees |
| SEP IRA | $70,000 | Simple setup, proportional contributions |
| Cash Balance | $150,000+ | Owners 45+, stable income |
| Defined Benefit | $250,000+ | Owners 50+, high income, few employees |
The setup costs matter. Defined benefit plans need annual actuarial certifications. But when you're paying 37% federal plus state tax, sheltering an extra $130,000 saves $50,000 annually.
Income and Deduction Timing
You control more than you think. December consulting income can shift to January with a delayed invoice. Equipment purchases can accelerate into the current year or defer to the next.
This only works if you're tracking projected income monthly. Not in December. In July.
Cash basis taxpayers have the most flexibility. Accrual basis businesses have less, but depreciation timing still matters. Bonus depreciation phases down after 2026, making equipment purchases particularly valuable now.
Construction companies, medical practices, and professional services firms all see massive swings in annual income. A doctor who bills $400,000 one year and $600,000 the next pays far more total tax than one who smooths to $500,000 both years.
Progressive tax brackets punish volatility.
Business Expense Classification
The tax code distinguishes between capital expenses and operating expenses. Get it wrong, you're depreciating something you could have deducted immediately.
Software as a service? Deductible. Custom software you own? Capitalized over 36 months under Section 167. Office furniture? Bonus depreciation might expense it fully, or you might depreciate over seven years.
Repairs versus improvements:
- Fixing a leaky roof: repair, immediately deductible
- Replacing the entire roof: improvement, capitalized
- Repainting an office: repair
- Expanding the office: improvement
The IRS tangible property regulations changed this landscape in 2014. Many CPAs still haven't adjusted. You can find detailed analysis in tax research databases that track regulatory changes and case law developments.
State and Local Considerations
Federal planning drives most decisions, but state tax structures vary wildly. Florida has no income tax. California tops out at 13.3%. Nevada has no corporate income tax. New York City adds another 4% on top of New York State's 10.9%.
Where you locate matters. Where your employees work matters. Where you store inventory matters. Nexus rules determine whether you file in a state, and getting it wrong means back taxes, penalties, and interest.
Remote work since 2020 created compliance nightmares. Your Tampa-based business with an employee working from Colorado now has Colorado income tax withholding obligations, unemployment insurance requirements, and potentially corporate income tax exposure.
Tax planning and tax management converge here. You need to plan your footprint strategically and manage compliance in each jurisdiction monthly.
Tax Management Systems That Actually Work
Monthly Financial Close Process
You can't plan what you can't measure. Monthly closes force discipline.
By the 10th of each month, you should know last month's revenue, expenses by category, profit margin, and cash position. Not estimates. Reconciled actuals.
This reveals problems while you can still fix them. You're trending toward $500,000 income instead of the projected $400,000? You have eight months to maximize retirement contributions, prepay expenses, or time equipment purchases.
Quarterly reviews only give you one chance to adjust before year-end.
Separate Business and Personal Finances
Commingled accounts kill deductions. The IRS sees mixed transactions and disallows everything that isn't clearly documented as business.
You need:
- Dedicated business checking account
- Business credit card for all company expenses
- Payroll system if you have employees (including yourself in an S-corp)
- Clear process for reimbursing personal funds used for business expenses
Sole proprietors resist this. They're leaving money on the table and increasing audit risk.
Document Retention and Organization
The IRS has three years to audit most returns, six if you underreported income by 25%, and forever if you didn't file. You need records that match.
Digital storage works. Paper works. Shoeboxes don't work.
Every deduction needs support: invoice, receipt, proof of payment, business purpose. The $50 dinner receipt without notes about who attended and what you discussed? Not deductible.
Common documentation failures:
- Mileage logs with gaps (start every January, track contemporaneously)
- Travel expenses without business purpose (conference attendance, client meetings)
- Home office deductions without photos and square footage calculations
- Vehicle expenses without allocation between personal and business use
Tax and accounting practice resources provide standard documentation templates that satisfy IRS requirements.
Quarterly Estimate Discipline
Underpayment penalties accrue at 8% annually when you miss estimates. That's an expensive loan you didn't want.
Safe harbor rules protect you if you pay 100% of last year's tax (110% if your adjusted gross income exceeded $150,000). But that might mean massive overpayment if this year's income drops.
Better approach: project annual tax liability in January, divide by four, adjust in June and September based on actual results. You'll land within 10% of actual liability and avoid penalties.
Payroll Compliance
If you have employees, payroll tax mistakes trigger immediate IRS attention. Trust fund penalties make business owners personally liable, piercing any corporate shield.
Critical deadlines:
- Federal payroll deposits: monthly or semi-weekly depending on liability
- Quarterly Form 941 filings
- Annual Form W-2 and W-3 by January 31
- State unemployment and income tax withholding (varies by state)
Miss a deposit and the IRS moves fast. These aren't negotiable like income tax debts.
Integrating Planning and Management
Tax planning and tax management work together when your systems feed planning decisions with real data.
January Tax Planning Session
Review last year's return. Identify missed opportunities. Project current year income and major purchases. Evaluate whether entity structure still fits. Model retirement contribution scenarios.
This is planning mode.
Monthly Management Reviews
Close books. Compare actuals to projections. Adjust quarterly estimates if needed. Address any compliance gaps. Update planning assumptions if income trajectory changed materially.
This is management mode.
Quarterly Strategy Adjustments
April, July, and October: revisit annual projections, model year-end scenarios, decide whether to accelerate or defer income and expenses. Confirm retirement plan contributions are on track.
Planning informed by management.
Year-End Execution
December: execute the plan you built all year. Buy equipment if bonus depreciation helps. Make retirement contributions. Pay bonuses. Bill clients or delay invoicing. Prepay expenses if you're cash basis.
Management executing planning.
You can review comprehensive approaches to federal tax research that explain how planning and compliance interact throughout the tax year.
Common Planning Mistakes
Waiting Until December
By year-end, most planning opportunities closed. Income was earned, deductions were spent, entity elections missed their deadlines.
S-corp elections require Form 2553 by March 15 for that year's treatment. Miss it, wait until next year. That's $15,000 in self-employment tax you can't recover.
Retirement plan adoptions need to happen by December 31 for defined benefit and cash balance plans. Solo 401(k) plans can adopt by year-end but contributions can occur until the return due date plus extensions.
Ignoring State Tax Consequences
A strategy that saves federal tax might trigger state tax problems. The reverse also happens.
Some states don't recognize S-corp elections. Others add back certain federal deductions. A few have separate entity-level taxes regardless of federal structure.
Nevada and Wyoming attract business formations because of no state income tax. But if your operations and customers are in California, you're filing California returns anyway. The Nevada LLC added cost and complexity without benefit.
Overlooking Estimated Tax Penalties
You saved $30,000 through smart planning but paid $2,400 in underpayment penalties because you didn't adjust estimates. That's wasteful.
The penalty compounds quarterly. Underpayment in Q1 accrues interest for nine months by April 15. Later quarters accrue less.
Front-loading estimates or using the annualized income method can eliminate penalties even with uneven income. But that requires monthly income tracking and quarterly calculations.
Missing Documentation Requirements
The Augusta Rule lets you rent your home to your business for up to 14 days annually, tax-free to you and deductible to the business. Powerful planning tool for board meetings and strategy sessions.
But you need fair market rent comparisons, meeting agendas, attendance records, and contemporaneous documentation. Without it, the IRS disallows everything.
Accountable plans for employee reimbursements, home office deductions, vehicle expenses – every aggressive position needs documentation that predates an audit.
Failing to Communicate with Advisors
Your attorney structures an LLC for asset protection. Your CPA doesn't know about it until tax time and discovers the default partnership taxation creates self-employment tax problems.
Your financial advisor recommends municipal bonds for tax-free income. Your CPA knows you're in alternative minimum tax territory where muni bond interest gets added back.
Tax planning and tax management require coordination between legal, accounting, and financial professionals. When they don't talk, you pay for the gaps.
When to Hire Specialized Help
Your CPA Is Sufficient When:
- Your business structure is simple (sole proprietor or single-member LLC)
- Annual income stays below $100,000
- You have no employees
- You operate entirely within one state
- Retirement savings fit within standard 401(k) limits
For businesses in this range, solid tax management through a competent accountant handles most needs. Planning opportunities exist but the dollar savings don't justify specialized fees.
You Need Advanced Planning When:
- Business income exceeds $200,000 annually
- You employ staff (including family members)
- You operate across state lines
- You're considering entity changes or major transactions
- Required retirement contributions exceed standard plan limits
- You face audit or collection issues
At this complexity level, the gap between basic compliance and strategic tax planning and tax management reaches five or six figures annually. The specialized fees pay for themselves immediately.
Building Your Tax Planning Team
Lead Tax Advisor
Either a CPA with significant planning experience or a tax attorney. This person coordinates strategy, identifies opportunities, and ensures compliance across federal and state jurisdictions.
Bookkeeper or Controller
Handles daily transaction recording, bank reconciliations, payroll processing, and monthly closes. Feeds clean data to the tax advisor for planning decisions.
Business Attorney
Structures entities, drafts operating agreements, handles employment matters, and reviews contracts for tax implications. Works with tax advisor on major transactions.
Financial Advisor
Manages investments, coordinates retirement plan funding, and integrates personal and business tax strategies. Particularly important when business exit planning begins.
Payroll Service
Processes payroll, handles deposits and filings, stays current on employment tax law changes. Takes federal and state compliance off your plate.
The team structure varies with business size, but separation of functions prevents gaps. When your CPA does bookkeeping, prepares returns, and handles payroll, something gets missed under deadline pressure.
Measuring Tax Planning Success
Effective Tax Rate
Total tax paid divided by total income. This is your scorecard.
A business owner earning $300,000 who pays $90,000 in total federal and state tax has a 30% effective rate. Through planning, that might drop to $70,000 (23.3% effective rate) – a $20,000 annual savings.
Track this annually. Flat or declining effective rates while income grows means your planning works.
Cash Flow Impact
Tax planning that reduces liability but destroys cash flow fails. Maxing retirement contributions cuts taxes but might leave insufficient operating capital.
The goal is keeping more money in your control, not minimizing tax at all costs. A strategy that defers $50,000 in tax but requires $200,000 in current spending isn't smart planning.
Compliance Cost Reduction
Better tax management systems reduce accounting fees, eliminate penalties, and prevent costly fixes after year-end. When your books are clean monthly, tax prep takes hours instead of days.
Measure total professional fees as a percentage of revenue. For small businesses, this should run 1-2%. If you're paying 4-5%, your systems need work.
Planning Horizon Extension
Success in tax planning and tax management means thinking in years, not quarters. When you can project three-year scenarios and structure transactions accordingly, you're capturing opportunities others miss.
Multi-year planning matters most with: equipment purchases and depreciation strategies, retirement plan design, entity structure changes, expansion timing, and ownership transitions.
You can find detailed planning frameworks in tax research materials that cover both current compliance and forward-looking strategy.
Tax planning and tax management separate businesses that thrive from those that merely survive. One is strategic, one is operational, and you need both working in concert throughout the year, not just in March. Taxt builds that integrated approach with a five-step process that reduces your tax anxiety, lowers your actual liability, and improves your financial records – with a money-back guarantee if the savings don't materialize.