Stop losing sleep over your tax situation. I'm Darrin Mish — a tax attorney in Tampa who's spent 32 years handling exactly this kind of problem. Here's what you need to know.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your CPA files your returns. That's compliance work. High net worth tax planning is different. It's the proactive moves you make in January through November that determine what you owe in April. Most business owners with seven-figure incomes pay more tax than necessary because they confuse the two.
The difference compounds. One client came to us paying 43% effective rate. Within eighteen months, we restructured entities, optimized retirement contributions, and implemented charitable strategies. New effective rate: 28%. Same income, $180,000 less to the IRS annually.
Why High Net Worth Tax Planning Differs From Standard Filing
Standard tax preparation looks backward. You made money, the preparer reports it, you pay the bill. High net worth tax planning looks forward and sideways. What entity holds this asset? Which state taxes that income? When does the gain recognize?
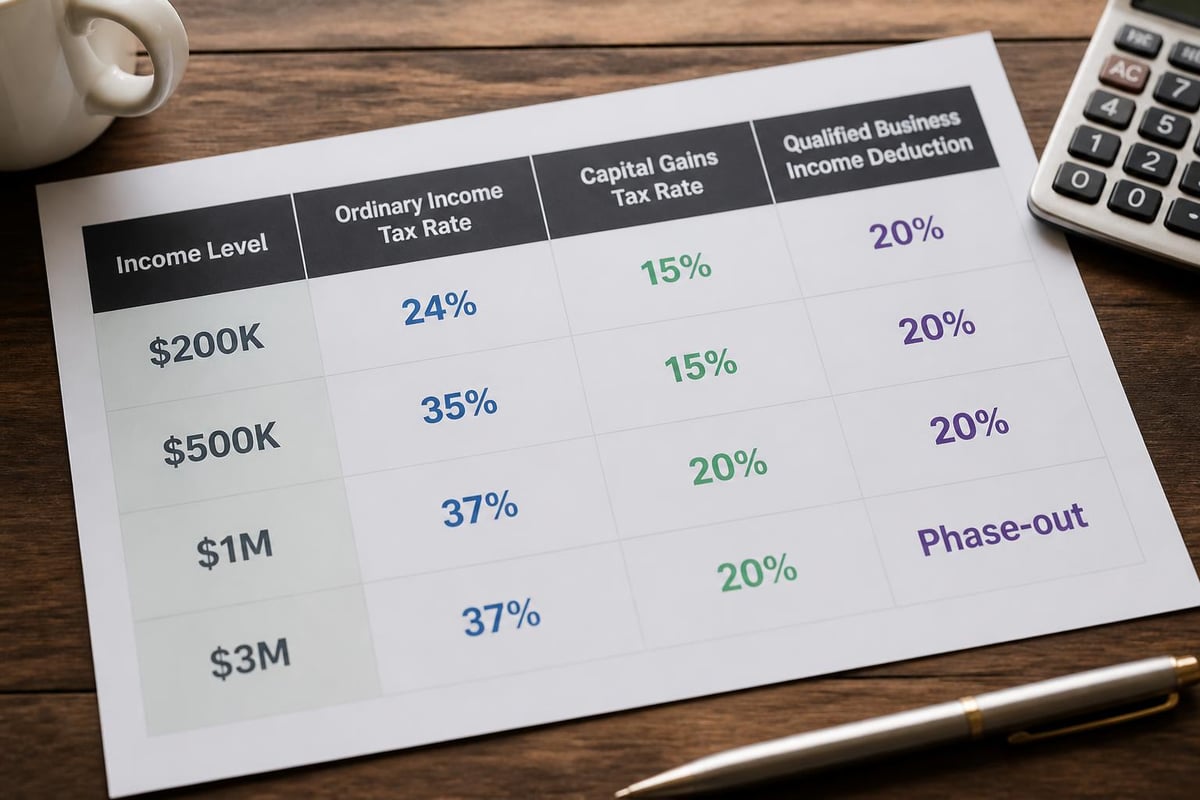
The tax code isn't neutral at higher income levels. Phase-outs, AMT triggers, net investment income tax, and qualified business income limitations create marginal rates most people never see. Your first dollar and your millionth dollar face completely different treatment.
Consider these threshold effects:
- 3.8% net investment income tax kicks in at $250,000 married filing jointly
- Qualified business income deduction phases out starting at $383,900 in 2026
- Social Security wage base creates a 6.2% cliff at $176,100
- State tax brackets compress wealth into top tiers faster than federal
Traditional advice says max out your 401(k) and call it done. At high net worth levels, that's leaving six figures on the table. You need layered strategies that stack deductions, defer income across years, and convert ordinary income into capital gains.
Entity Structure: The Foundation Most CPAs Overlook
Your business entity determines your tax outcome before you earn dollar one. S-corps, C-corps, partnerships, and disregarded LLCs each trigger different rules. Most business owners pick one at formation and never revisit. That's expensive.
S-corporation status lets you split income between wages and distributions. You pay payroll tax only on the wage portion. A business owner taking $500,000 as W-2 wages pays $13,794 in payroll taxes. Split that into $150,000 wages and $350,000 distributions? Payroll tax drops to $4,138. That's $9,656 saved annually.
The IRS requires "reasonable compensation" as wages. What's reasonable? There's no safe harbor. Industry standards, time invested, comparable salaries, and profitability all factor in. Set wages too low, expect an audit adjustment. Set them too high, you're volunteering money.
Multi-Entity Structures for Real Estate Investors
Real estate creates different income types. Rental income, capital gains, 1031 exchanges, depreciation recapture. One LLC holding everything mixes these streams and limits your planning flexibility.
Better approach: separate entities for property holding, property management, and development activities. The management company pays you wages (retirement plan contributions allowed). The holding LLCs pass through rental income (offset by depreciation). Development income can route through entities in states with favorable treatment.
| Entity Type | Best Use Case | Tax Treatment | Key Benefit |
|---|---|---|---|
| S-Corp | Active business operations | Pass-through, payroll tax savings | Wage/distribution split |
| C-Corp | Retained earnings, fringe benefits | Double taxation but lower initial rate | 21% federal rate |
| Partnership | Multiple owners, flexibility | Pass-through, special allocations | Disproportionate distributions |
| Disregarded LLC | Single member, simplicity | Reported on personal return | Liability protection |
Many high-net-worth individuals benefit from an unbundled advisory model that separates tax planning from investment management. This creates clearer accountability and often better outcomes.
Retirement Account Strategies Beyond the 401(k)
Qualified retirement plans do more than defer tax. They remove assets from your estate, protect against creditors, and create Roth conversion opportunities. But the conventional "max out your 401(k)" advice caps you at $23,500 in 2026 for employee deferrals.
Add a cash balance pension plan. Contributions up to $300,000 annually depending on age and compensation. That's real money. A 55-year-old earning $500,000 can often contribute $225,000 to a cash balance plan on top of 401(k) contributions.
These plans work best when:
- You have consistent high income
- Your business has stable cash flow
- You employ few or no other employees
- You're within 10-15 years of retirement
The contribution formulas favor older, higher-paid participants. If you're 50+ with income exceeding $400,000, run the numbers. The tax deduction alone often covers the administrative costs.
Backdoor Roth Conversions and Mega Backdoor Strategies
Direct Roth IRA contributions phase out at $246,000 for married couples in 2026. But there's no income limit on conversions. Fund a non-deductible traditional IRA, convert it immediately to Roth. No tax, no penalty, Roth assets growing tax-free.
The mega backdoor Roth uses after-tax 401(k) contributions. Total 401(k) contributions (employer and employee) can reach $70,000 in 2026. Max out pre-tax and employer match, then add after-tax dollars. Convert those after-tax contributions to Roth. You've moved another $30,000-$40,000 into tax-free growth.
Your plan document must allow after-tax contributions and in-service distributions or conversions. Most off-the-shelf plans don't. Custom plan design required.
Charitable Giving That Reduces Tax Without Reducing Wealth
Writing checks to charity gives you a deduction. Using appreciated assets transfers the gain without tax and gives you fair market value deduction. The difference matters at scale.
You bought stock ten years ago for $50,000. It's worth $300,000 today. Sell it, pay 23.8% capital gains and net investment income tax on $250,000 gain. That's $59,500 to the IRS, $240,500 to charity.
Donate the stock directly. Charity receives $300,000. You deduct $300,000 (subject to AGI limitations). No tax paid on the gain. You've transferred 25% more to the cause and increased your deduction by the same amount.
Donor-Advised Funds for Bunching Deductions
Standard deduction in 2026: $30,000 married filing jointly. If your itemized deductions hover near that amount, you get little benefit from charitable giving. The solution: bunch multiple years of donations into one.
Contribute $150,000 to a donor-advised fund in year one. Take the full deduction. In subsequent years, claim the standard deduction. You've collapsed five years of $30,000 donations into one large deduction that exceeds the standard deduction threshold.
The funds sit in the donor-advised account growing tax-free. You recommend grants to charities over time. You've preserved your giving pattern while maximizing tax benefit.
Donor-advised funds offer:
- Immediate tax deduction when you contribute
- No deadline for distributing to charities
- Investment growth on undistributed funds
- Simple annual reporting
- Privacy in your grant-making
Qualified charitable distributions from IRAs work differently but serve similar goals. After age 70½, you can transfer up to $105,000 annually directly from your IRA to charity. It doesn't count as income, satisfies required minimum distributions, and doesn't require itemizing.
Estate Tax Planning That Protects Generational Wealth
Federal estate tax exemption sits at $13.99 million per person in 2026. But that number sunsets December 31, 2025, reverting to roughly $7 million indexed for inflation. If you're married with $20 million in assets, you're suddenly facing exposure.
State estate taxes complicate this further. Twelve states and D.C. impose their own estate taxes with much lower thresholds. Massachusetts starts at $2 million. Dying there with $5 million? Your estate owes state tax even with full federal exemption remaining.
High net worth tax planning addresses both concerns through gifting, trusts, and entity planning. The annual gift exclusion ($19,000 per recipient in 2026) lets you transfer wealth continuously without using lifetime exemption. A married couple with three children and six grandchildren can gift $342,000 annually free of gift tax.
Grantor Retained Annuity Trusts and Intentionally Defective Grantor Trusts
GRATs transfer future appreciation to beneficiaries while you retain an annuity for a term of years. Structure it correctly, and you move growth out of your estate with minimal gift tax cost.
You transfer $5 million in rapidly appreciating assets to a GRAT. It pays you $1.05 million annually for five years (structured using IRS rates). If the assets grow above that 7520 rate (2.8% in May 2026), the excess passes to beneficiaries gift-tax-free.
The assets return $8 million in five years. You've received your $5.25 million back. The remaining $2.75 million transferred to heirs using almost no lifetime exemption.
IDGTs work differently. You're treated as the owner for income tax purposes but not estate tax purposes. You pay tax on the trust's income (further removing wealth from your estate), while the assets and growth stay outside your taxable estate.
Many of these strategies appear in a comprehensive checklist for high-net-worth individuals that covers asset assessment and long-term planning considerations.
| Strategy | Primary Benefit | Best Candidate | Complexity Level |
|---|---|---|---|
| Annual Exclusion Gifts | Continuous wealth transfer | Anyone with heirs | Low |
| GRAT | Transfer appreciation tax-free | Appreciating assets | Medium |
| IDGT | Remove assets from estate | Substantial estates | High |
| Family Limited Partnership | Valuation discounts | Real estate, business interests | High |
| Charitable Lead Trust | Reduce estate, support charity | Philanthropic goals | High |
Business Succession Planning That Minimizes Tax Impact
Selling your business creates a tax event. Structure matters more than sale price in determining what you keep. Stock sales, asset sales, installment sales, and earnouts each trigger different timing and character of income.
Asset sales let buyers step up basis. They want this. It generates depreciation deductions. You pay ordinary income tax on depreciation recapture and goodwill at capital gains rates. Total combined rate can hit 40% when state tax factors in.
Stock sales give you capital gains treatment on the entire amount. Lower rate, simpler structure. But buyers don't get basis step-up. They'll pay less or demand indemnification clauses. You're trading rate for price.
Installment Sales and Private Annuities
Spreading gain recognition across years reduces the tax hit and keeps you in lower brackets. Sell for $10 million in one year, you're paying top rates on the entire amount. Structure it as an installment sale, recognize $2 million annually for five years.
Each year's income gets taxed at potentially lower rates. You've deferred tax on $8 million, earning interest on money that would otherwise have gone to the IRS. The buyer gets easier financing, you get tax deferral.
Private annuities remove the asset from your estate entirely. You transfer the business in exchange for unsecured annuity payments for life. Done correctly, you've removed a $10 million business from your taxable estate and converted it to income stream.
The annuity payments include return of basis (tax-free), capital gain, and ordinary income portions. You've spread the tax impact across your remaining life expectancy while eliminating estate tax exposure.
Key considerations in business succession:
- Character of gain (ordinary vs. capital)
- Timing of recognition (lump sum vs. installment)
- Estate tax implications of retained interests
- Employment agreements for ongoing involvement
- Non-compete payments (ordinary income)
- Covenant not to compete allocations
Estate planning and business succession often overlap. Advanced estate planning strategies designed for high-net-worth individuals can preserve business value across generations while minimizing transfer taxes.
Tax Loss Harvesting and Basis Management
Investment portfolios generate gains. That's the goal. But realizing those gains creates tax. High net worth tax planning manages when and how gains recognize.
Tax loss harvesting captures losses to offset gains. You hold a position down 30%. Sell it, recognize the loss, buy back a substantially identical security after 31 days. You've captured the loss for tax purposes while maintaining market exposure.
Better yet, buy a correlated but not identical security immediately. You've avoided the wash sale rule and stayed invested. The loss offsets current year gains or carries forward indefinitely.
Step-Up at Death Planning
Assets you hold until death receive step-up in basis. Your heirs inherit at fair market value on date of death. Decades of appreciation disappear for tax purposes.
You bought Amazon in 2002 for $10,000. It's worth $2 million today. Sell it, you owe tax on $1,990,000 gain. Die holding it, your heirs' basis resets to $2 million. They sell immediately, zero tax.
This influences hold-versus-sell decisions at high net worth levels. If you're 70+ with low basis stock and life expectancy under 15 years, holding often beats selling and paying tax.
Exchange-traded funds offer more tax efficiency than mutual funds. They rarely distribute capital gains. Mutual funds distribute gains annually whether you sell or not. Over decades, that difference compounds significantly.
The habits wealthy individuals follow often include disciplined tax loss harvesting and strategic asset location across taxable and tax-deferred accounts.
State Tax Residency and Income Sourcing
You control where you're taxed more than you think. Residency rules vary by state. Most count days, but factors like where you vote, license your car, and maintain professional licenses all matter.
High-tax states like California, New York, and New Jersey push residents toward Florida, Texas, Nevada, and Tennessee. No state income tax saves 10%+ on high incomes. On $2 million annual income, that's $200,000 annually.
Establishing new domicile requires:
- Physical presence in new state (183+ days often safe)
- Changing voter registration
- Obtaining new state driver's license
- Filing homestead exemption if available
- Moving financial accounts and professional registrations
But leaving high-tax states isn't simple. California pursues former residents aggressively. New York has a "convenience of the employer" rule that taxes income if you work remotely for a New York employer. Moving your residence doesn't always move your income.
Income sourcing rules determine where business income gets taxed. S-corp income sources to your state of residence. Partnership income can source to the state where earned. If you're a New York resident with partnership interests in Florida real estate, some states will tax you, some won't.
Multi-state businesses need apportionment planning. Sales factor, property factor, and payroll factor determine what percentage of income each state taxes. Moving operations, employees, or nexus points can shift significant income between jurisdictions.
The Cost of Waiting
Every year without proper high net worth tax planning compounds the damage. The $100,000 you overpay in 2026 invested at 8% becomes $466,000 over 20 years. That's real wealth transferred from your family to the government.
Most business owners wait until year-end to think about taxes. By December, your options narrow. Income earned, entities set, retirement contributions maxed or missed. High net worth tax planning works in January, not December.
The five-step planning process we use starts with baseline assessment. What are you paying now? Where's it coming from? What entity holds what asset? You can't improve what you don't measure.
Step two: identify opportunities. Entity restructuring, retirement plan design, charitable strategies, whatever fits your situation. We're looking for $50,000+ in annual savings, not $5,000 adjustments.
Implementation comes third. Forming entities, establishing plans, executing documents. This is where most planning dies, intention without execution.
Monitoring ensures the strategies work as designed. The tax code changes, your business changes, income fluctuates. Strategies effective in 2024 might fail in 2026 without adjustment.
Review happens annually, with quarterly check-ins. We're measuring actual tax paid against projected, ensuring savings materialized, adjusting for next year.
High net worth tax planning separates business owners who build lasting wealth from those who earn well but accumulate slowly. The strategies exist, the savings are real, but they require proactive implementation and ongoing management. Taxt specializes in exactly this process: the five-step tax planning framework that identifies opportunities your CPA misses, implements the strategies that matter, and guarantees measurable savings. If you're paying six figures in tax annually, you owe it to yourself to know what you're leaving on the table.