Stop losing sleep over your tax situation. I'm Darrin Mish — a tax attorney in Tampa who's spent 32 years handling exactly this kind of problem. Here's what you need to know.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
You don't need another article explaining what a Roth 457b is. You need to know whether you're using it correctly, and whether your current advisor is missing the layering strategy that government and nonprofit employees should be running.
Most tax planning focuses on business owners and W-2 professionals at private companies. The Roth 457b sits in a different corner of the tax code, one that conventional advisors often overlook because they're not working with enough state, local, or nonprofit clients to build real pattern recognition.
The Roth 457b Isn't a Roth IRA With a Different Name
The IRS treats 457(b) plans differently than the retirement accounts most people know. This matters more than you think.
A Roth 457b accepts after-tax contributions like a Roth IRA. But that's where the similarities end. You're not subject to the income limits that lock high earners out of direct Roth IRA contributions. You're also not dealing with the 10% early withdrawal penalty that applies to most retirement accounts before age 59½.
Who Actually Qualifies for a Roth 457b
Eligibility for 457(b) plans runs through two tracks. Government employees at state and local levels can access governmental 457(b) plans. Tax-exempt organizations under IRC 501(c) can offer non-governmental 457(b) plans.
You won't find a Roth 457b at a private corporation. This is an account type built specifically for public sector and nonprofit workers.
The Roth feature within these plans became available when the IRS published guidance on designated Roth accounts. Not every employer immediately added the option. Some governmental entities and nonprofits still only offer traditional pre-tax 457(b) deferrals.
The Triple-Layer Contribution Strategy Nobody Mentions
Here's where most advisors miss the planning opportunity. You can run three separate contribution streams simultaneously if your compensation supports it.
The three layers:
- Roth 457b contributions up to $23,500 in 2026 (or $31,000 if you're 50 or older with catch-up contributions)
- Roth IRA contributions up to $7,000 in 2026 (or $8,000 age 50+) if your income permits
- 401(k) or 403(b) contributions if your employer offers both a 457(b) and another retirement plan
The 457(b) contribution limit operates independently. You're not sharing contribution space with your 401(k) or 403(b) the way you would if you had two 401(k) plans. This creates room for serious wealth accumulation.
A 52-year-old municipal employee making $120,000 could theoretically contribute $31,000 to a Roth 457b, $23,500 to a governmental 401(k), and $8,000 to a Roth IRA in the same year. That's $62,500 in total retirement contributions, with $39,000 going into Roth accounts that will never be taxed again.
Most people don't max this out. But knowing the ceiling matters because it defines what's possible when you're building a tax planning structure.
The Age 50 Catch-Up Math
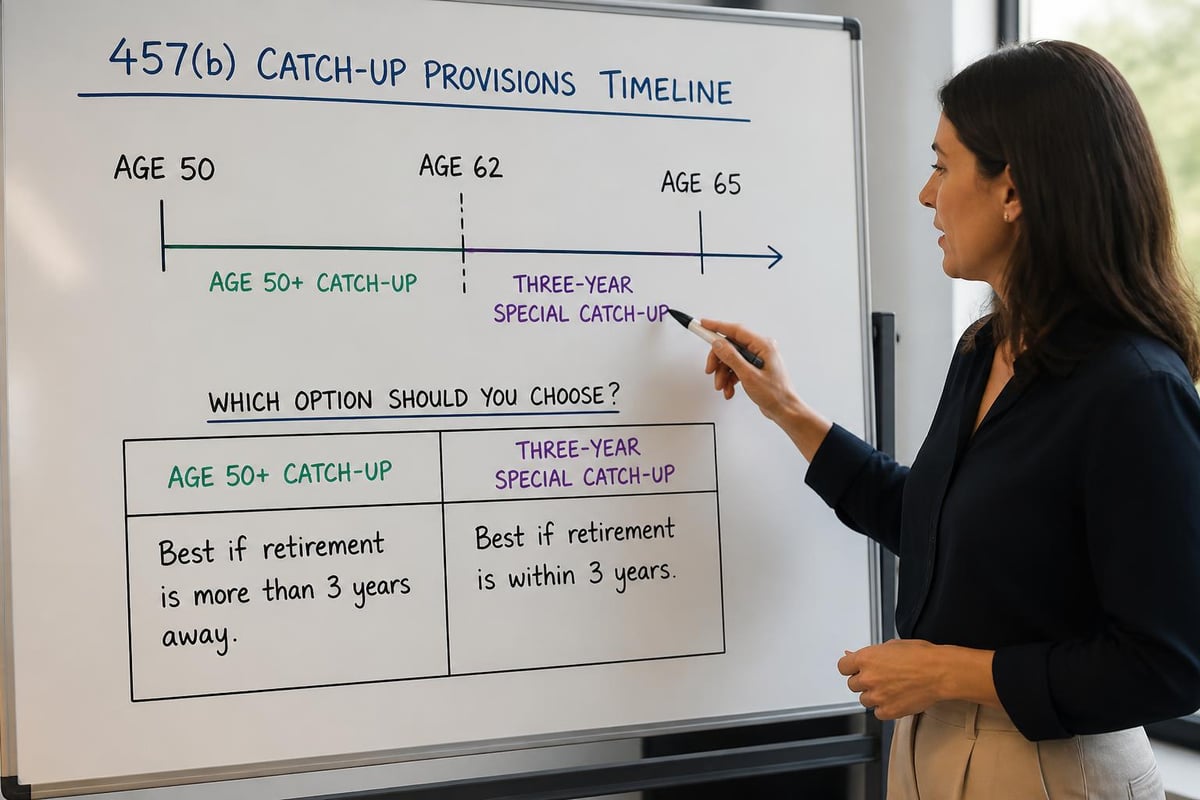
Standard catch-up contributions add $7,500 to your 457(b) limit once you hit 50. But governmental 457(b) plans have a special catch-up provision that conventional retirement accounts don't offer.
In the three years before normal retirement age (as defined by your plan), you can contribute double the standard limit. For 2026, that means $47,000 instead of $23,500. You can't use both the age-50 catch-up and the three-year catch-up simultaneously. You pick the larger number.
This creates a planning window. If you're 52 and your plan's normal retirement age is 55, you could be looking at three years of $47,000 contributions to your Roth 457b. That's $141,000 in tax-free bucket contributions in a compressed timeframe.
| Catch-Up Type | Age Requirement | 2026 Maximum Contribution | Best Use Case |
|---|---|---|---|
| Standard Age 50+ | 50 or older | $31,000 | General retirement saving |
| Three-Year Special | Within 3 years of plan retirement age | $47,000 | Accelerated final-years contribution |
| Under 50 | Younger than 50 | $23,500 | Long-term wealth building |
The Tax-Free Distribution Timeline You Need to Track
Your Roth 457b distributions come out tax-free if you meet the qualified distribution rules. This requires a five-year holding period and one of these triggering events: reaching age 59½, death, or disability.
The five-year clock starts January 1 of the year you make your first Roth contribution to any Roth account in the plan. Not the date of the actual contribution. This is a planning point worth noting.
If you make your first Roth 457b contribution in December 2026, your five-year clock starts January 1, 2026. You'd satisfy the time requirement on January 1, 2031, assuming you've also met one of the triggering events.
The No-Penalty Separation Rule
Here's where the Roth 457b diverges from Roth IRAs and Roth 401(k)s in a meaningful way. Governmental 457(b) plans don't impose the 10% early withdrawal penalty when you separate from service.
You can access your Roth 457b at any age after you leave your employer. No penalty. This creates liquidity that other retirement accounts don't provide.
The distributions still need to meet the five-year rule to come out entirely tax-free. But if you separate from service at 52, you can start distributions immediately without the penalty that would hit you on a Roth IRA distribution.
This matters for early retirement planning. You're building a tax-free income stream that doesn't trap you until age 59½.
Pre-Tax or Roth: The Decision Your CPA Isn't Modeling
The traditional versus Roth decision in a 457(b) plan follows the same math as any retirement account. But most advisors make this call based on your current tax bracket without running the actual numbers on what your retirement distributions will look like.
You want Roth contributions when:
- Your current marginal rate is lower than your expected retirement rate
- You anticipate significant taxable income in retirement from pensions, rental properties, or other sources
- You're young enough that tax-free compounding has decades to work
- You've already maxed traditional contributions and want additional Roth space
You want traditional pre-tax contributions when:
- Your current marginal rate is high and you expect a drop in retirement
- You need the current-year deduction to manage taxable income
- You're close to retirement and won't benefit significantly from long-term Roth growth
- You plan to relocate to a state with no income tax in retirement
The mistake is making this choice once and never revisiting it. Your optimal contribution mix changes as your income changes, as tax law changes, and as your retirement timeline compresses.
A 35-year-old making $75,000 might lean Roth. The same person at 55 making $140,000 might shift to traditional deferrals to reduce current taxes, especially if they've already built a substantial Roth balance.
The Partial Roth Strategy
You're not locked into all-or-nothing. Most plans let you split contributions between traditional and Roth in whatever percentage you want.
Running a 60/40 split (60% Roth, 40% traditional) creates tax diversification. You're building a tax-free bucket and a tax-deferred bucket. This gives you control over your taxable income in retirement because you can choose which account to draw from based on your tax situation each year.
This is advanced planning. Most people don't think this way. But if you're working with Taxt or another proactive planning firm, this is the kind of structure you should be discussing.
The Rollover Rules That Catch People Off Guard
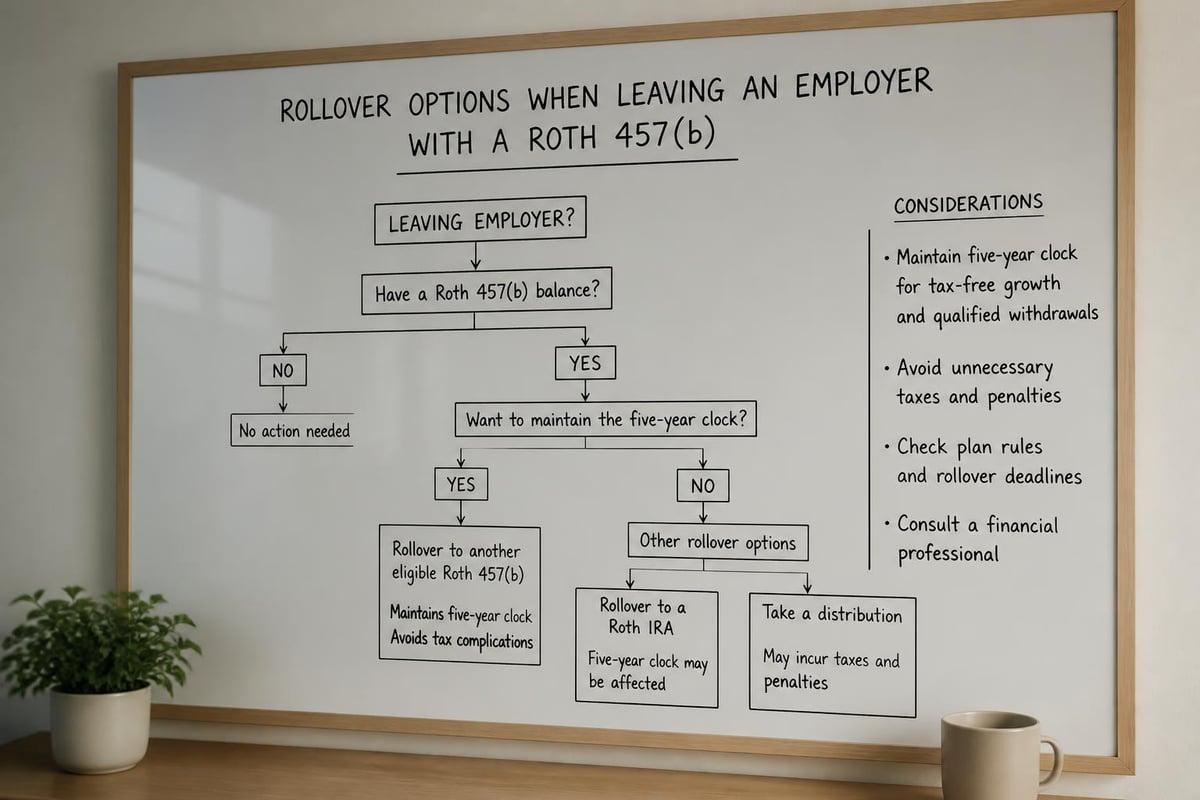
When you leave your employer, your Roth 457b can roll into a Roth IRA or another employer's Roth 457(b) if they accept transfers. You cannot roll a Roth 457b into a traditional IRA. The Roth designation follows the money.
Rollover options:
- Roth 457b → Roth IRA
- Roth 457b → Another employer's Roth 457b (if permitted)
- Roth 457b → Roth 401k/403b (if permitted)
- Traditional 457b → Traditional IRA
- Traditional 457b → Another employer's traditional 457b (if permitted)
The five-year clock for the Roth IRA doesn't restart if you're rolling from a Roth 457b that already satisfied its own five-year requirement. But if you're rolling into a Roth IRA that you've never contributed to before, you start a new five-year clock for that Roth IRA.
This gets technical fast. The point is that you need to track these clocks separately and understand which distributions come from which source.
Non-Governmental 457b Plans Are Different
If you work for a nonprofit with a non-governmental 457(b), your rollover options narrow. These plans face different rules under IRC Section 457(b) because the assets remain property of the employer until distribution.
Non-governmental 457(b) plans can only roll into another non-governmental 457(b). You cannot roll these into an IRA or governmental 457(b). The assets are always at risk if your nonprofit employer faces creditor claims.
This is a meaningful limitation. It's why governmental 457(b) plans are generally more valuable than their nonprofit counterparts, even though the contribution limits match.
The Roth Conversion Opportunity Within Your 457b
Some plans allow in-plan Roth conversions. This lets you convert your traditional 457(b) balance to Roth without leaving your employer or rolling to an IRA.
You pay tax on the converted amount in the year of conversion. But once converted, that money grows tax-free and comes out tax-free.
This makes sense when:
- You're in an unusually low-income year (sabbatical, leave, business loss)
- You expect tax rates to increase
- You want to accelerate Roth contributions beyond the annual limit
- You're managing future required minimum distributions
The conversion creates a taxable event. That's the cost. But if you're strategic about timing, you can fill up the bottom of your tax bracket with conversion income without jumping into a higher bracket.
A married couple with $80,000 in taxable income in 2026 has room up to $96,950 before hitting the 22% bracket (assuming standard deduction). They could convert $16,950 from traditional 457(b) to Roth 457b and pay tax at 12% instead of the 22% or higher rate they might face in retirement.
Required Minimum Distributions and the Roth Advantage
Traditional 457(b) accounts face required minimum distributions starting at age 73 (for those born 1951-1959) or age 75 (for those born 1960 or later). Roth 457(b) accounts also face RMDs, which is different from Roth IRAs.
Roth IRAs don't have RMDs during the owner's lifetime. But designated Roth accounts in employer plans do. This includes Roth 401(k), Roth 403(b), and Roth 457b accounts.
However, you can avoid RMDs on your Roth 457b by rolling it to a Roth IRA before RMDs begin. Once in the Roth IRA, no lifetime RMDs apply.
This is a planning step. You don't leave the Roth 457b sitting in your former employer's plan indefinitely if you want to avoid RMDs. You move it when you separate from service.
RMD comparison:
| Account Type | Lifetime RMDs? | Workaround |
|---|---|---|
| Traditional 457b | Yes | Cannot avoid |
| Roth 457b | Yes | Roll to Roth IRA |
| Traditional IRA | Yes | Cannot avoid |
| Roth IRA | No | Not needed |
The State Tax Treatment You Might Be Missing
Federal tax law treats Roth 457b contributions as after-tax and distributions as tax-free. State tax treatment varies.
Most states follow federal treatment. But some states don't recognize Roth contributions or impose their own rules. If you contribute to a Roth 457b while working in one state and retire to another, you need to understand both states' treatment.
Some states tax retirement distributions regardless of source. Pennsylvania taxes all retirement income except Social Security. California generally follows federal Roth treatment but has higher income tax rates that make the Roth advantage more valuable.
This is granular. But if you're building a seven-figure Roth 457b balance, state tax treatment can swing the numbers by tens of thousands of dollars over a retirement.
Your tax planning should account for where you'll be living when you start distributions, not just where you live now.
The Documentation and Compliance Your Plan Administrator Handles
The written plan requirements for 457(b) plans fall on your employer and plan administrator. You're not responsible for maintaining compliance documentation.
But you should understand what's required because plan failures can affect your tax treatment. If your employer's plan loses its qualified status, your deferrals could become immediately taxable.
This rarely happens with governmental plans. It's more common with non-governmental 457(b) plans at smaller nonprofits that don't maintain proper documentation.
Ask your HR department or plan administrator when the plan was last amended and whether it's been updated for recent law changes. Resources like those provided by MissionSquare and state programs like Nevada’s deferred compensation program often include educational materials about Roth options and plan compliance.
If you get vague answers or pushback, that's a yellow flag. Well-run plans have clear documentation and regular compliance reviews.
The Coordination With Social Security and Pension Income
Your Roth 457b distributions don't count as income for Social Security taxation thresholds. This is a real advantage.
Social Security benefits become taxable when your combined income (adjusted gross income plus nontaxable interest plus half of Social Security) exceeds $25,000 for single filers or $32,000 for married filing jointly. Up to 85% of your Social Security can become taxable once you cross higher thresholds.
Roth distributions don't add to combined income. Traditional 457(b) distributions do.
If you're pulling $40,000 from a traditional 457(b) and receiving $30,000 in Social Security, a significant portion of your Social Security becomes taxable. If you pull the same $40,000 from a Roth 457b instead, your Social Security faces less tax.
This compounds over a 30-year retirement. The Roth advantage isn't just the tax-free growth. It's the way Roth distributions keep your other income sources from becoming taxable.
The Roth 457b is one of the cleanest tax-free wealth tools available to government and nonprofit employees, but only if you're layering contributions strategically and timing conversions to fill low-income years. Most conventional advisors don't build planning around these accounts because they're not common in the private sector. Taxt specializes in multi-year tax planning that integrates retirement accounts like the Roth 457b with broader wealth strategies, helping you structure contributions and distributions to minimize lifetime taxes. If you're ready to move beyond basic compliance and into real planning, we'll show you what you've been missing.