Most people I talk to about their IRS problem have already built the worst-case scenario in their head. The reality is usually much more manageable. I'm Darrin Mish, and I've been representing taxpayers before the IRS for 32 years. Here's what actually tends to happen.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. That's my resolution practice. What follows is the other side of the desk – the planning moves that keep you from ever needing it.
Your Roth IRA sits there year after year. No 1099. No tax reporting. Then one February, you get a roth ira 1099 in the mail and wonder what changed.
Most business owners don't realize Roth IRAs are invisible to the IRS until money moves out. Contributions don't generate forms. Growth doesn't trigger reporting. But take a distribution, process a conversion, or recharacterize a contribution, and your custodian sends forms to both you and the IRS.
Understanding which transactions trigger a roth ira 1099 keeps you from overpaying taxes or missing required reporting. The codes on these forms tell the IRS whether your distribution is taxable, penalized, or completely tax-free.
When Your Roth IRA Generates a 1099 Form
You won't receive a form for simply owning a Roth IRA. Your custodian doesn't report your account balance or annual growth. The IRS doesn't track your contributions through a 1099 either.
The form appears when money leaves your Roth IRA. Any distribution, regardless of amount or reason, triggers a Form 1099-R from your custodian. That includes qualified distributions, early withdrawals, conversions from traditional IRAs, and returned excess contributions.
Distribution Scenarios That Require Forms
Your custodian must report every dollar that exits your Roth IRA. This includes situations most business owners don't consider distributions.
Common triggers include:
- Direct withdrawals you request
- Automatic distributions you've scheduled
- Amounts rolled to another retirement account
- Traditional IRA conversions to Roth
- Excess contribution returns
- Required corrections for prohibited transactions
Understanding why you received a 1099-R helps you verify the form matches your actual transactions. Custodians make errors. Codes get miscoded. Amounts get doubled.
I've seen business owners receive 1099-R forms showing taxable amounts on qualified distributions. The custodian coded it wrong. Filing without catching that error costs thousands.
Form 1099-R Structure and Key Information
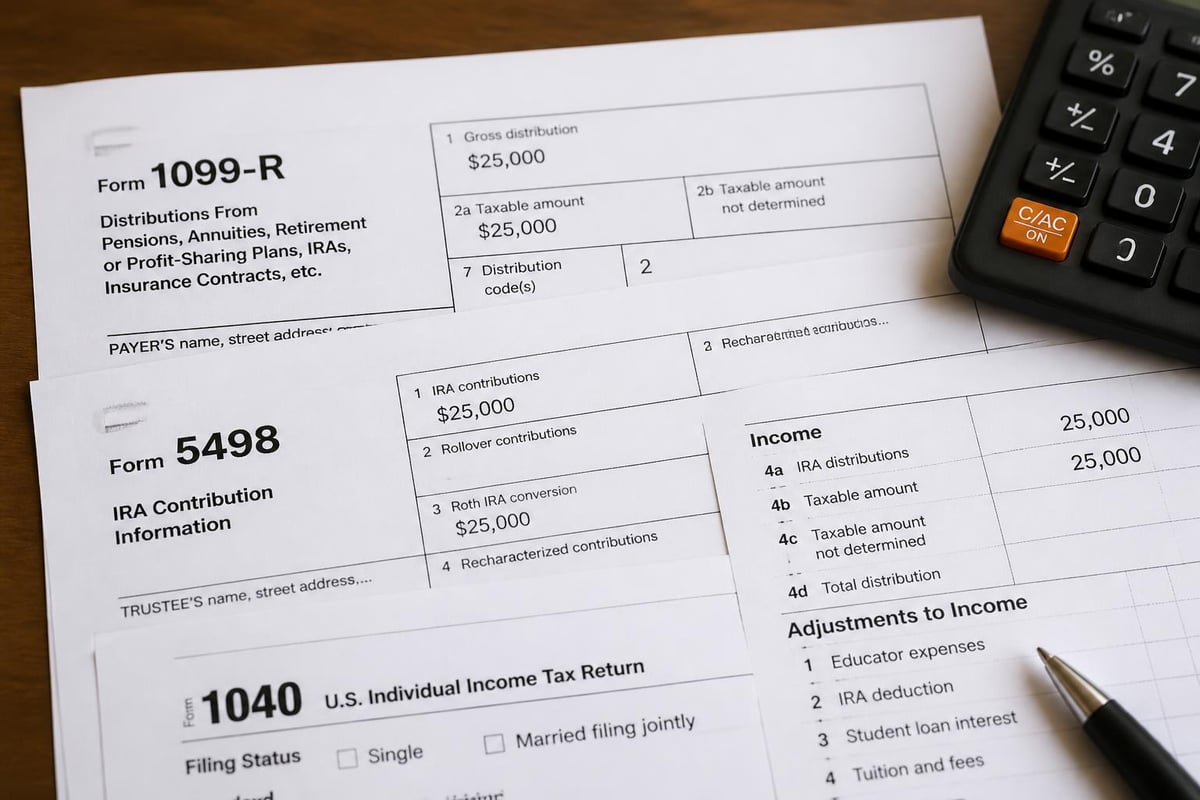
The roth ira 1099 arrives as Form 1099-R, identical to the form reporting traditional IRA and 401(k) distributions. Box layout matters because each box tells a different part of your tax story.
Box 1 shows gross distribution. This is every dollar that left your Roth IRA, regardless of whether it's taxable. Box 2a shows the taxable amount, which for qualified Roth distributions should be zero.
Critical Boxes to Verify
Box 7 contains the distribution code. This single letter or number combination determines whether the IRS expects you to pay tax and penalties. The IRS provides detailed instructions for interpreting each code.
| Box Number | What It Reports | Why It Matters |
|---|---|---|
| 1 | Gross distribution amount | Total dollars withdrawn |
| 2a | Taxable amount | What you owe tax on |
| 2b | Taxable amount not determined checkbox | Custodian doesn't know your basis |
| 5 | Employee contributions or designated Roth | Your after-tax contributions |
| 7 | Distribution code | Determines tax treatment |
| 11 | First-year Roth contributions | Amount in first distribution year |
Box 2b sometimes shows a checkmark indicating the custodian couldn't determine the taxable amount. Common with Roth IRAs because custodians don't track whether you've met the five-year rule or age requirements. That falls on you.
Box 5 should match your total Roth contributions. This box helps prove which portion of your distribution represents returned contributions versus earnings. Contributions always come out tax-free and penalty-free.
Distribution Codes That Determine Tax Treatment
Code Q in Box 7 means qualified distribution. No tax. No penalty. You met both the five-year holding requirement and one qualifying reason: age 59½, disability, first-time home purchase, or death.
Code J indicates early distribution from a Roth IRA with no known exception. The IRS expects you to pay the 10% early withdrawal penalty on any earnings portion unless you qualify for an exception.
What Each Common Code Signals
Business owners converting traditional IRAs to Roth see different codes. Code 2 means early distribution with an exception, often used for conversions before age 59½.
Distribution code guide:
- Code T: Roth IRA distribution, exception applies
- Code J: Early Roth distribution, no exception
- Code Q: Qualified Roth distribution (tax-free)
- Code 8: Excess contribution returned
- Code N: Recharacterized IRA contribution
Your reporting obligations for Roth IRA distributions depend entirely on which code appears. File Form 8606 with code J or T to track basis and calculate any taxable earnings.
Code errors happen frequently. I've reviewed dozens where custodians marked qualified distributions as early withdrawals. You're 62, owned the Roth for eight years, took $30,000 out. Form shows code J instead of Q. The difference: $3,000 in unnecessary penalties.
Reporting Your Roth IRA 1099 on Your Tax Return
Your Form 1040 requires reporting all 1099-R forms, even qualified distributions showing zero tax. Line 4a captures the total distribution from Box 1. Line 4b shows the taxable amount from Box 2a.
For qualified distributions, you'll see the full amount on 4a and zero on 4b. This tells the IRS you took money out but owe nothing. Leaving line 4a blank triggers matching problems.
Required Supporting Forms
Non-qualified distributions require Form 8606 to calculate the taxable portion. This form separates your contributions from earnings because contributions exit tax-free regardless of timing.
The five-year rule complicates this calculation. Your Roth IRA starts its five-year clock January 1 of the year you made your first contribution. Not when you opened the account. Not when you made this year's contribution.
Form 8606 calculates:
- Total Roth IRA basis (your contributions)
- Ordering rules for distributions
- Taxable earnings portion
- Applicable penalties
Financial institutions explain how Form 1099-R connects to your tax return, but they can't tell you whether your distribution qualifies. That requires knowing your contribution history and meeting both age and timing requirements.
Business owners with multiple Roth conversions from different years face additional complexity. Each conversion starts its own five-year clock for penalty-free access to converted amounts.
Forms You Won't Receive for Roth Contributions
Contributions to your Roth IRA don't generate a roth ira 1099 or any tax form you file. The IRS doesn't require reporting Roth contributions the way they track traditional IRA deductions.
Your custodian sends Form 5498 to the IRS showing contribution amounts, but you don't file this form with your return. It's informational only, confirming you stayed within contribution limits.
Why Contribution Tracking Falls on You
IRA contributions aren’t reported on a 1099 form you file, creating a documentation gap. You need records proving when you contributed and how much. Critical for calculating basis and determining qualified distributions years later.
| Form | Who Gets It | What It Shows | Do You File It? |
|---|---|---|---|
| 5498 | You and IRS | Contributions made | No |
| 1099-R | You and IRS | Distributions taken | Yes |
| 8606 | You file it | Basis tracking | Yes (if needed) |
Custodians issue Form 5498 by May 31, covering the prior tax year plus contributions made through the April deadline. That's why it arrives after you've already filed. The IRS uses it to verify you didn't exceed limits.
Business owners maximizing retirement contributions across multiple accounts need these forms. Total Roth IRA contribution limits apply across all your Roth accounts combined: $7,000 in 2026, or $8,000 if you're 50 or older.
Conversions and Recharacterizations Trigger Multiple Forms
Converting a traditional IRA to Roth generates a roth ira 1099 showing the conversion amount. The form reports it as a distribution from your traditional IRA and a rollover to your Roth.
Box 7 typically shows code 2 for early conversion or code 7 for normal conversions. The entire converted amount appears taxable in Box 2a because traditional IRA funds include pre-tax contributions and earnings.
How Multi-Step Transactions Get Reported
Recharacterizations create confusing paper trails. You contribute to a Roth, later decide to undo it by recharacterizing to a traditional IRA. Your custodian issues a 1099-R showing the transfer.
Code N in Box 7 indicates recharacterization. The taxable amount should be zero because you're not actually withdrawing funds. You're reclassifying the contribution type.
Conversion reporting shows:
- Form 1099-R from traditional IRA (distribution)
- Form 5498 to Roth IRA (contribution)
- Full amount reported as taxable income
- No early withdrawal penalty if you follow rollover rules
Strategic conversion timing reduces lifetime taxes for business owners expecting higher future rates. But each conversion starts a new five-year penalty clock on the converted amount. Take that converted money out before five years pass, and you'll pay the 10% penalty even if you're over 59½.
I've worked with business owners who converted $200,000 across five years, took an emergency distribution in year three, and paid penalties on conversions that hadn't aged five years. The code on their roth ira 1099 showed the distribution but didn't indicate which conversion years were accessed.
Common Errors That Cost Business Owners Money
Custodians mark qualified distributions as non-qualified regularly. You're 65, owned the Roth for 15 years, took $50,000 out. Form 1099-R shows code J instead of Q.
File as-is and you'll calculate tax on earnings and potentially pay the 10% penalty. The error adds thousands to your bill. Contact your custodian immediately when codes don't match your situation.
Box 2a Mistakes Create Tax Nightmares
Some custodians leave Box 2a blank or check "taxable amount not determined" even for clearly qualified distributions. They're protecting themselves from liability but creating work for you.
Frequent errors include:
- Wrong distribution codes for age-qualified withdrawals
- Showing taxable amounts on qualified distributions
- Failing to report recharacterizations correctly
- Double-reporting rollovers as both distributions and contributions
- Incorrect basis reporting in Box 5
Request corrected forms before filing. Custodians issue 1099-R corrected versions, but processing takes weeks. Filing with known errors and explaining them later invites IRS scrutiny and potential audits.
Business owners taking substantially equal periodic payments under Section 72(t) need code 1 in Box 7. Wrong codes trigger automated penalty assessments. The IRS computer sees an early distribution without the exception code and bills you.
Record-Keeping Requirements for Future Distributions
Your current roth ira 1099 might be correct, but future forms depend on records you keep today. The IRS requires you to prove when you made contributions and met the five-year rule.
Keep every Form 5498 you receive. These show contribution dates and amounts. Track rollovers and conversions separately because each has distinct rules. Your custodian only knows what happened at their institution.
Documentation That Protects You Years Later
Custodians merge. Systems change. Records disappear. I've seen business owners with 20-year-old Roth IRAs unable to prove their initial contribution date. That first year determines when qualified distributions start.
| Document | What It Proves | Keep Until |
|---|---|---|
| Form 5498 (all years) | Contribution dates and amounts | Permanently |
| Form 1099-R (all years) | Distribution history | Permanently |
| Form 8606 (all years) | Basis calculations | Permanently |
| Conversion documentation | Traditional to Roth transfers | Permanently |
| Account statements | Balance verification | 7 years minimum |
The burden falls on you, not your custodian. Prove you've owned the Roth for five years. Prove your contributions total what you claim. Prove you properly reported past distributions.
Business owners with Roth IRA accounts at multiple custodians must aggregate records across institutions. Your total basis includes all contributions to all Roth IRAs you've ever owned. Distributions come from that combined basis regardless of which account you tap.
Excess Contributions and Their Tax Forms
Contribute more than the annual limit and you'll receive a roth ira 1099 when you withdraw the excess. Code 8 or P in Box 7 indicates excess contribution removal.
The excess itself isn't taxable because you used after-tax dollars. But earnings on that excess are taxable and subject to the 10% penalty if you're under 59½. Box 2a shows those earnings separately.
Correcting Overcontributions Before Penalties Stack
You have until your tax return deadline plus extensions to withdraw excess contributions without owing the 6% excess contribution penalty. Miss that deadline and you pay 6% annually until you remove it.
Excess removal reporting:
- Box 1: Total distribution (excess plus earnings)
- Box 2a: Taxable earnings only
- Box 7: Code 8 (early distribution, excess removed)
- Special code P for designated Roth accounts
The 6% penalty applies each year the excess remains. Contribute $1,000 over the limit, ignore it for three years, and you've paid $180 in penalties plus the amount still sits there subject to more penalties.
Business owners whose income unexpectedly exceeded Roth IRA limits during the year face this constantly. You contributed $7,000 in January based on projected income. Year-end numbers put you over the phase-out range. Now that entire $7,000 is excess requiring removal.
Forms for Inherited Roth IRAs Work Differently
Inherit a Roth IRA and distributions follow different rules but still generate a roth ira 1099. The form shows code 4 indicating death distribution. These are always penalty-free regardless of beneficiary age or account age.
Tax treatment depends on whether the original owner met the five-year rule. Their clock transfers to you. They owned it for seven years before death, your distributions are qualified even if you're 30 years old.
Beneficiary Distribution Requirements
Non-spouse beneficiaries must empty inherited Roth IRAs within 10 years under current rules. Each required distribution generates a 1099-R. Code 4 prevents the 10% penalty, but taxable earnings still apply if the five-year rule wasn't met.
Spouses electing to treat inherited Roth IRAs as their own see different codes. No distribution code because it's not technically a distribution. The account becomes yours as if you'd owned it originally.
Business owners inheriting Roth IRAs from parents need to know the original contribution date. That determines whether distributions are fully tax-free or include taxable earnings. The 1099-R won't tell you. The deceased owner's records will.
Your roth ira 1099 tells the IRS what happened but leaves verification to you. Wrong codes, incorrect taxable amounts, and missing basis information create tax bills you don't owe. Review every form against your records before filing. Taxt helps business owners develop tax planning strategies that minimize distributions triggering unnecessary forms while building retirement wealth efficiently, backed by our money-back guarantee if we don't find you savings.